Posted on 15 November 2026
Free Business Loan Documents Checklist for Nigeria in Excel, Word and PDF
- Available to download for free in Excel, Google Sheets, Word and PDF formats.
- Tests your bank statement turnover against published rules from 7 lenders, including Access Bank, Sterling, LSETF and BOI.
- Turns monthly loan rates into a yearly cost and shows when repayments jump.
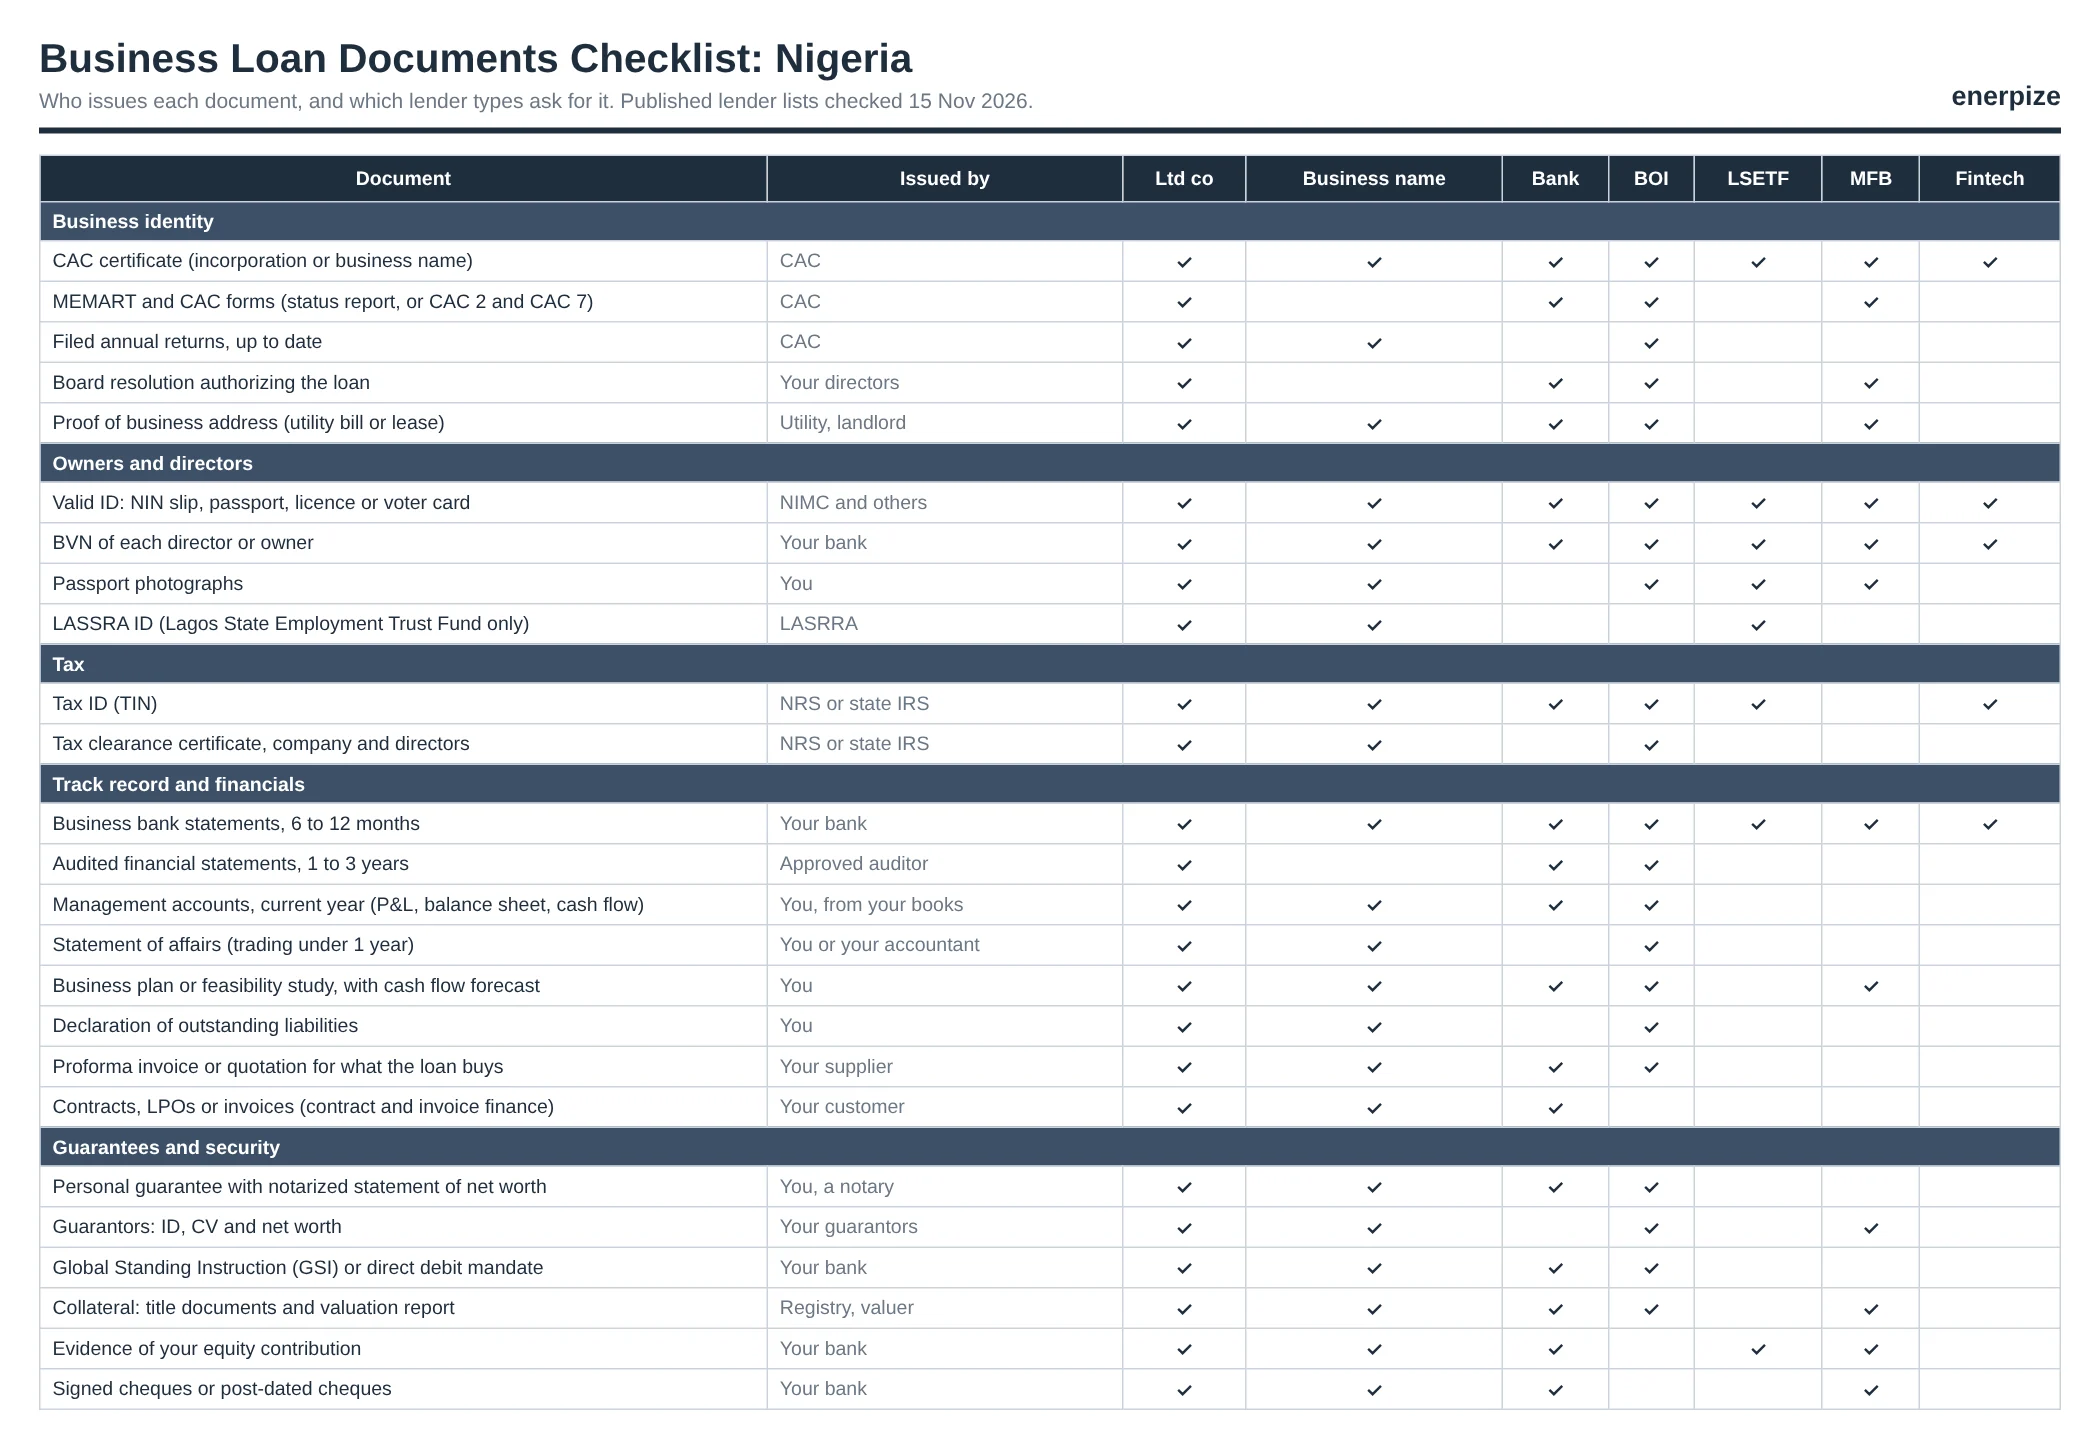
- Lists 25 documents Nigerian lenders ask for and who issues each one.
Business loan documents in Nigeria are the CAC papers, IDs and BVN, tax records, bank statements, financial statements, business plan and guarantees a lender uses to decide whether you can repay. Requirements differ between banks, the Bank of Industry, LSETF, microfinance banks and fintechs, so start with your lender’s list.


Last updated: November 15, 2026
What it is
A business loan documents pack for Nigeria: a checklist of what lenders ask for, a business plan for a loan, and a workbook that prepares and tests your numbers.
When you need it
Before you walk into a bank, apply on the BOI portal, or fill in an LSETF, microfinance or fintech application.
What's inside
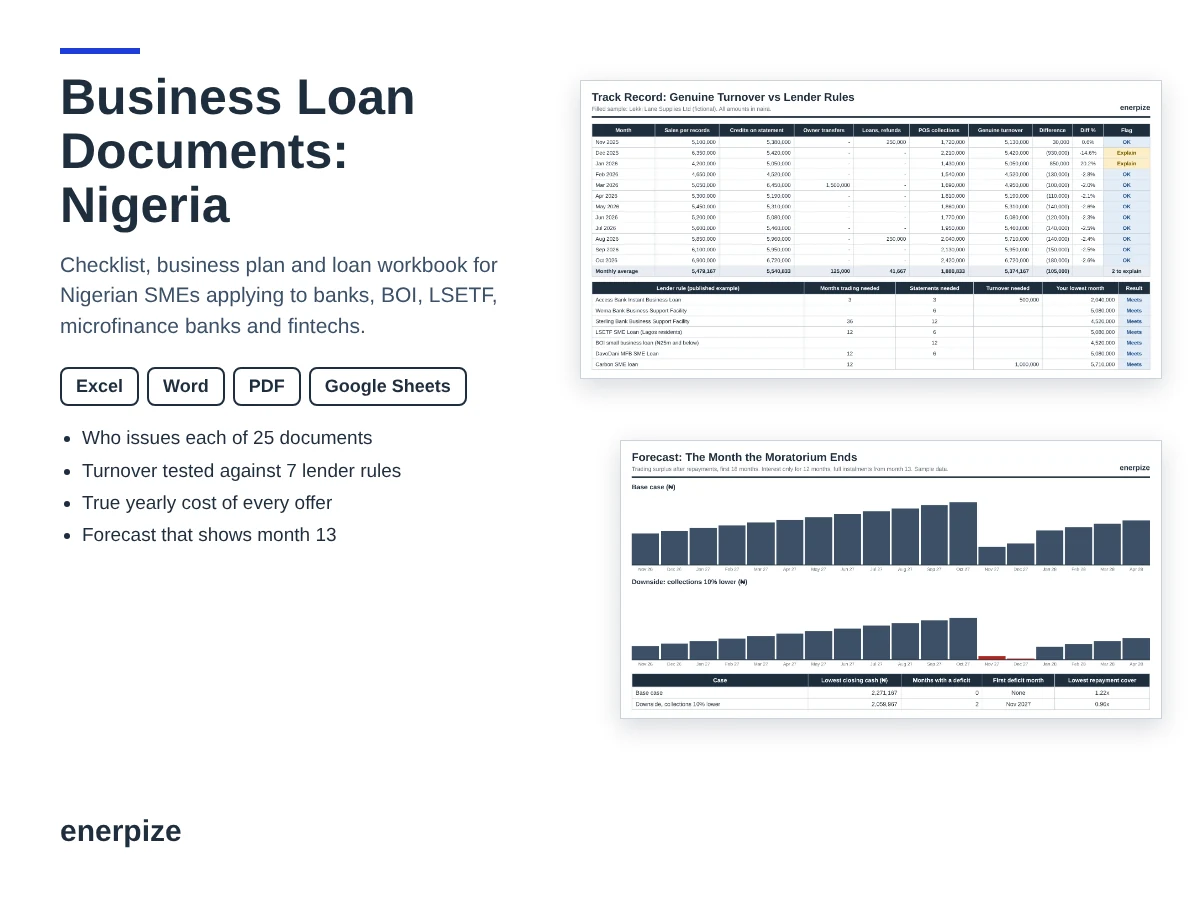
A 25-document checklist, a 10-section business plan, and an 11-sheet workbook: track record, P&L, balance sheet, cash flow, loan cost, forecast, liabilities, net worth and review checks.
Formats
Excel, Google Sheets, Word and PDF, blank and filled, in one free ZIP.
Want to see it filled in first?
Make your own copy of the filled sample in Google Sheets.
What Are Business Loan Documents in Nigeria?
The relationship manager smiles, slides a list across the desk and says, "Bring these, then we can talk."
Twenty items. Some you have. Some you have never heard of. And one of them, the tax clearance certificate, takes weeks if you start late.
Business loan documents in Nigeria are the registration papers, IDs, tax records, bank statements, financial statements, plans and guarantees a lender uses to decide whether your business can repay. Banks, the Bank of Industry, state funds, microfinance banks and fintechs each ask for a different mix, so the list always starts with the lender.
People search for it as documents required for a business loan in Nigeria, SME loan requirements or business loan requirements in Nigeria. It is the same pile of paper, sorted by who issues it.
your pack
bank, BOI or fund
statements and visit
letter and terms
after conditions
It is not an application form, an offer letter or a promise of approval. The pack gets you ready. The lender decides.
Loan Pack vs Business Plan vs Application Form vs Offer Letter
Four documents get mixed up in every loan conversation. Each one comes from a different person, at a different stage.
| Document | Its job | Who prepares it | When it appears |
|---|---|---|---|
| Loan document pack | Gathers and checks everything the lender asks for | You, with your accountant | Before you apply |
| Business plan for a loan | Explains the amount, its use and how it is repaid | You | With the application |
| Loan application form | Captures your details in the lender's format | You, on the lender's form | At application |
| Offer letter | States the rate, fees, tenor, security and conditions | The lender | After appraisal |
The pack proves your past, the plan argues your future, and the offer letter sets the price.
Writing the plan from scratch? The business plan template covers the full version. The loan plan in this pack is the shorter one lenders actually read.
Which Business Loan Document List Fits You?
Two businesses can ask for the same ₦5 million and get two different lists. Your legal form, your age and your lender decide which one you get.
| If your situation is... | What changes | Start here |
|---|---|---|
| A limited company asking a commercial bank | CAC forms, board resolution, audited or management accounts | Checklist, "Ltd co" and "Bank" columns |
| A business name (sole proprietor) | No MEMART or board resolution; personal and business accounts often read together | Checklist, "Business name" column |
| Trading for less than a year | Statement of affairs and a forecast instead of past accounts | Balance Sheet sheet, last column |
| A Lagos resident asking LSETF | LASSRA ID, LIRS tax ID, 5% equity | LSETF section below |
| A manufacturer or processor asking BOI | Feasibility study, proforma invoices, accredited auditor | BOI section below |
| A trader on 30-day terms needing stock money | Turnover and POS history carry the decision | Track Record sheet |
| Invoicing big customers who pay late | Invoices and LPOs as evidence of sales | The Nigeria invoice template |
What Documents Do Nigerian Lenders Ask For?
Most lists of the business loan documents Nigeria lenders ask for stop at the names. The useful question is who issues each one, because that decides how long it takes.
| Document | Who issues it | Why it matters |
|---|---|---|
| CAC certificate, MEMART and status report | Corporate Affairs Commission | Proves the business exists and who owns it |
| Board resolution to borrow | Your directors | Shows the company, not one person, agreed to the loan |
| ID and BVN of each director | NIMC and your bank | Credit bureau checks run on BVN |
| Tax ID and tax clearance certificate | Nigeria Revenue Service or your state IRS | Shows you are tax compliant |
| Business bank statements, 6 to 12 months | Your bank | The lender's main evidence of turnover |
| Audited accounts, 1 to 3 years | An approved auditor | Required by some lenders above set amounts |
| Management accounts, current year | You, from your books | Covers the months since the last audit |
| Business plan and cash flow forecast | You | Explains the amount and the repayment source |
| Declaration of outstanding liabilities | You | Lists what you already owe |
| Personal guarantee and statement of net worth | You, notarized | Puts the owner's assets behind the loan |
| Collateral papers and valuation | Lands registry and a valuer | Needed for secured loans |
The document that decides most applications is the one you can't edit: your bank statement. Everything else either explains it or backs it up. That is why the workbook starts with your turnover, not your plan.
One update catches people out. The Federal Inland Revenue Service became the Nigeria Revenue Service from January 1, 2026. A tax clearance certificate request today goes to NRS or your state service, not "FIRS".
What the Enerpize Business Loan Documents Pack Includes
We started from our Australian loan pack and rebuilt it around Nigerian lenders. We read the published requirements of eight Nigerian lenders and programmes and built the workbook to test your figures against them. Formulas only, no macros; yellow cells are the only ones you type in.
A Bank Statement That Tells the Truth
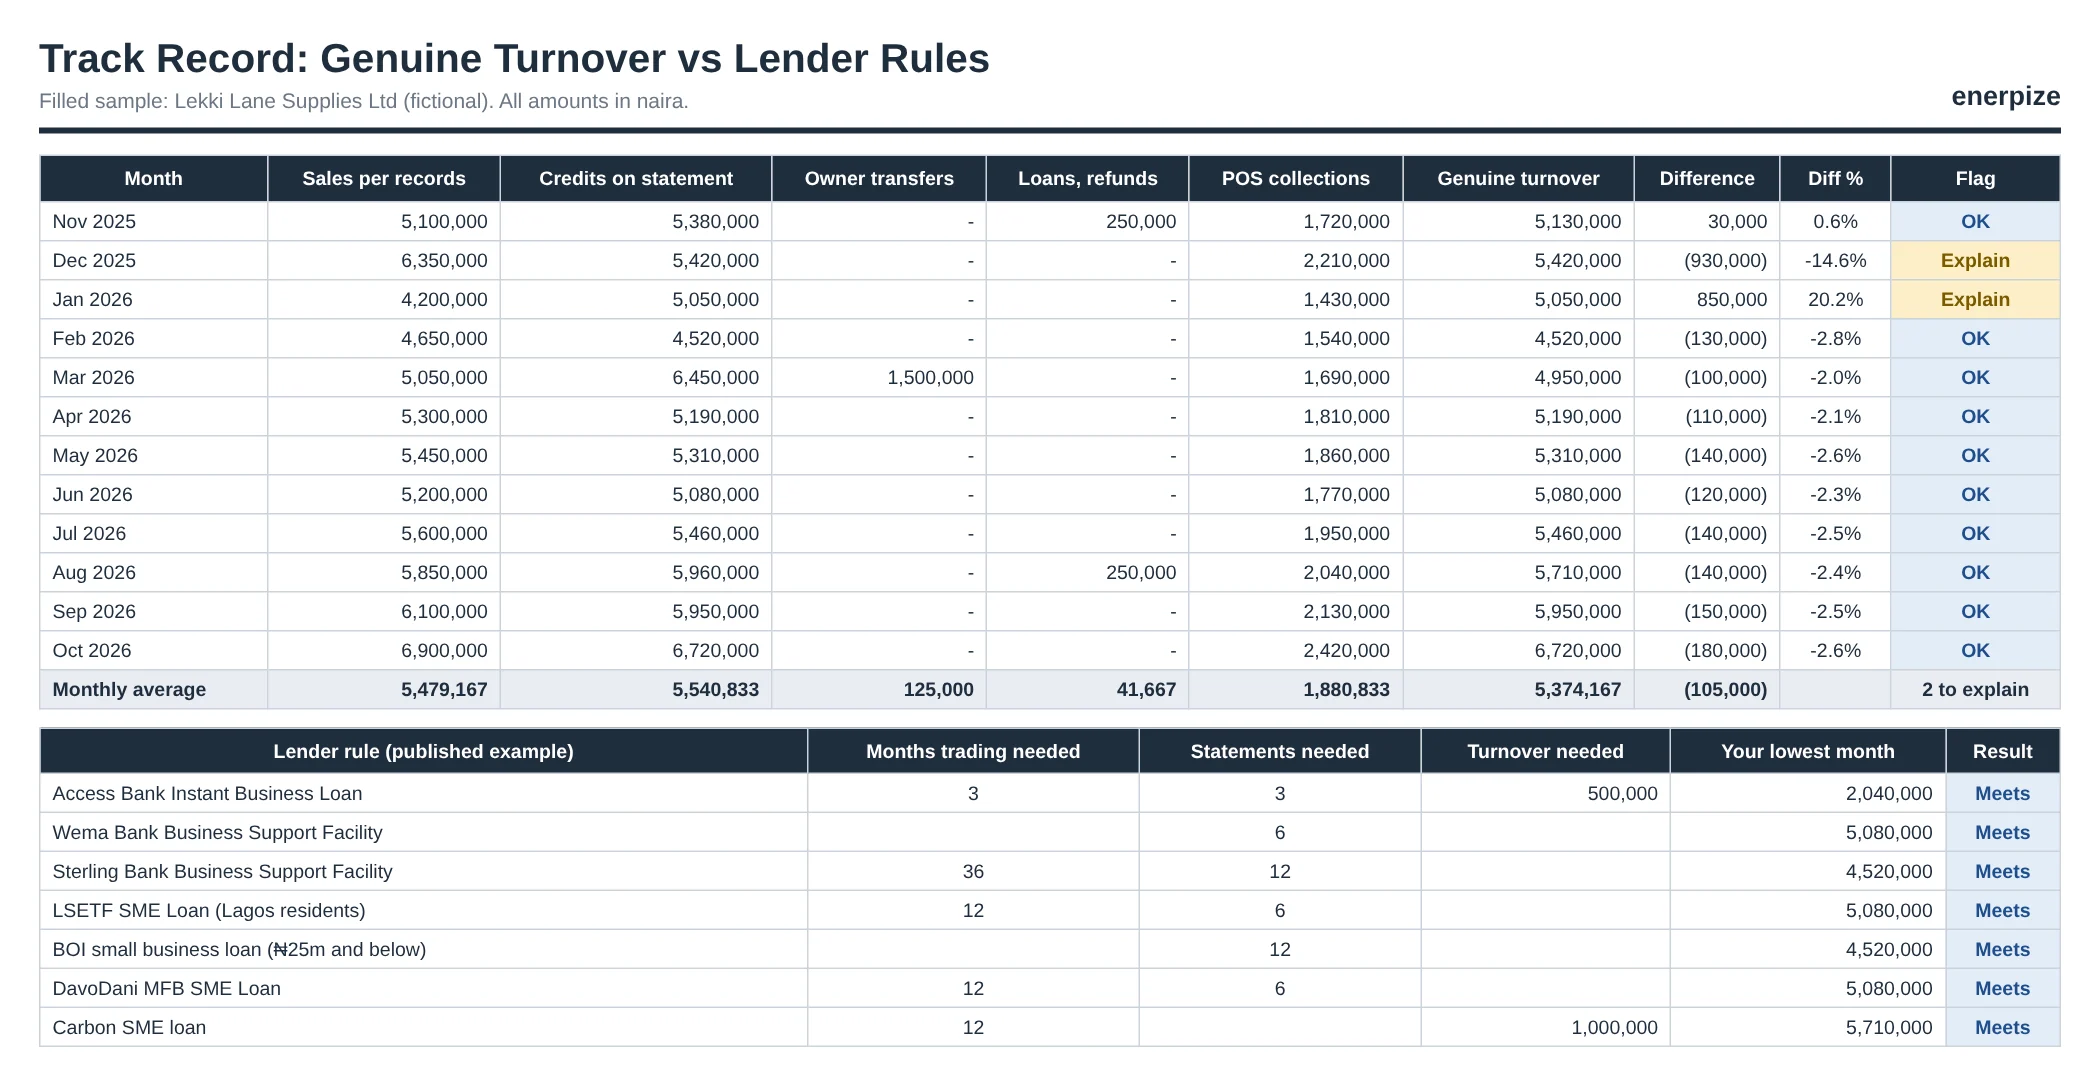
Credits on your statement are not turnover. Owner top-ups, loan money and supplier refunds all land in the same account. Track Record strips them out, compares what is left with your sales records, and flags any month more than 10% apart, so you can explain it before the lender asks.
Seven Lenders, One Pass or Fail
The same sheet tests your months of trading, months of statements and lowest monthly turnover against published rules from Access Bank, Wema, Sterling, LSETF, BOI, a microfinance bank and a fintech. Each rule sits in Settings with its source, so you can edit it when your lender quotes something different.
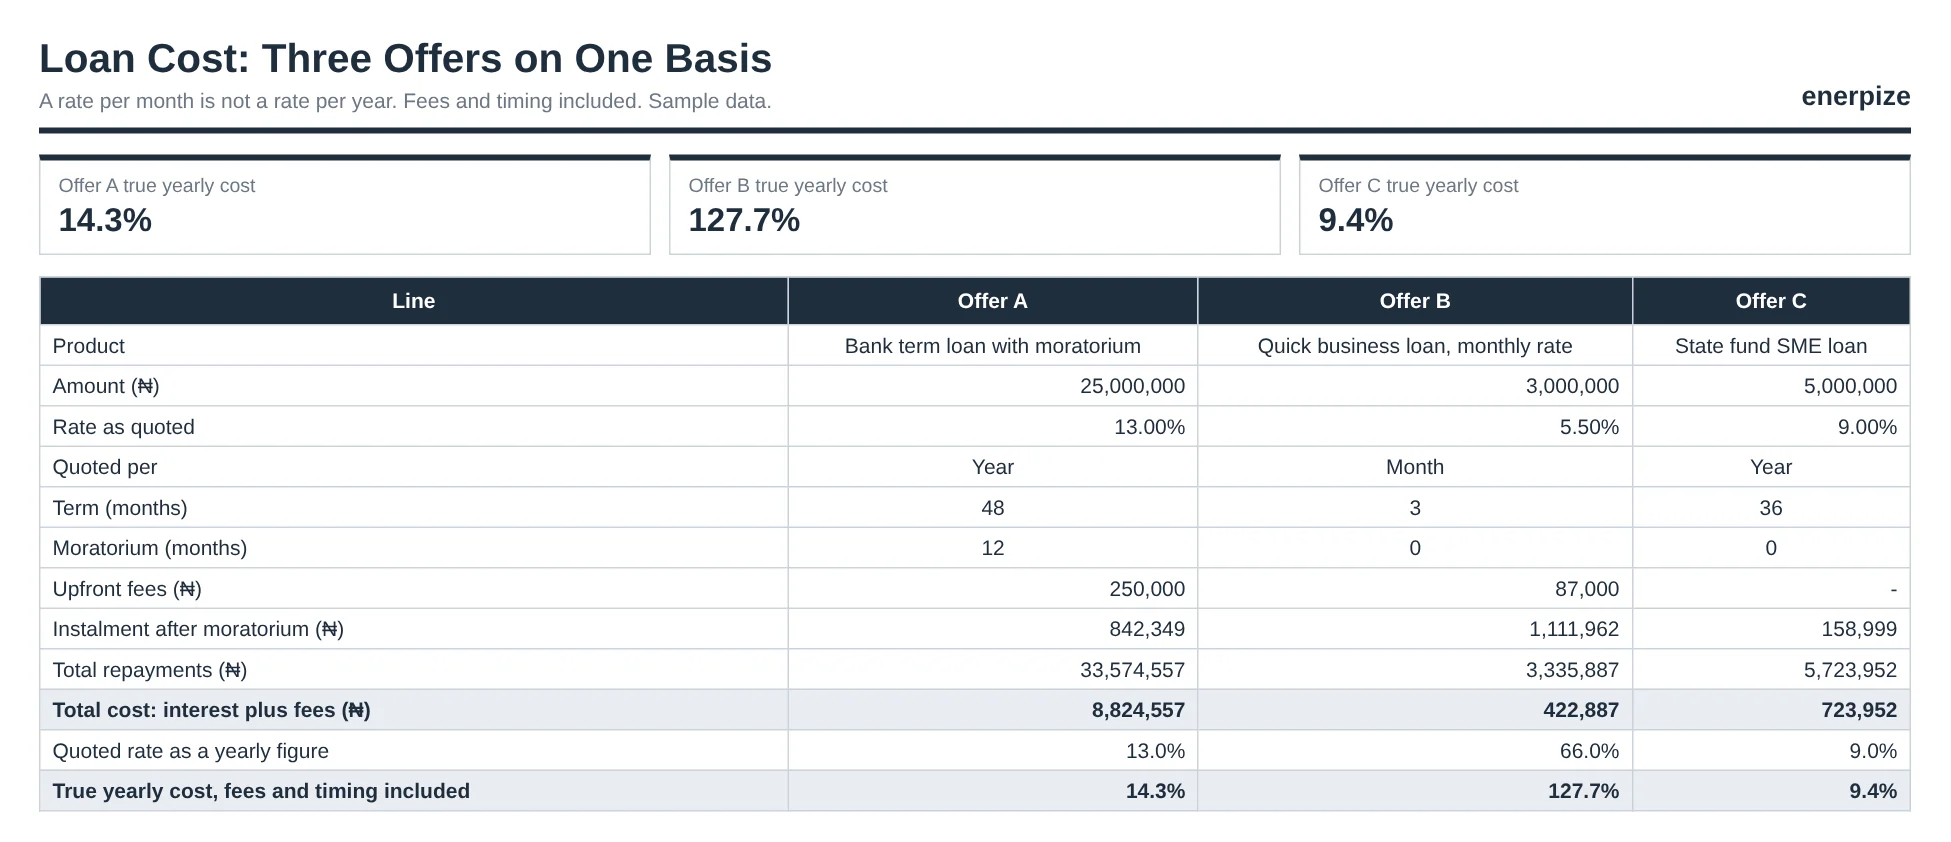
Three Offers, One Honest Number
Enter offers exactly as quoted, per month or per year, with fees. Loan Cost works out the true yearly cost from the cash you actually receive and repay. In the sample, 5.5% a month becomes 127.7% a year once fees and a three-month term are counted.
The Month the Moratorium Ends
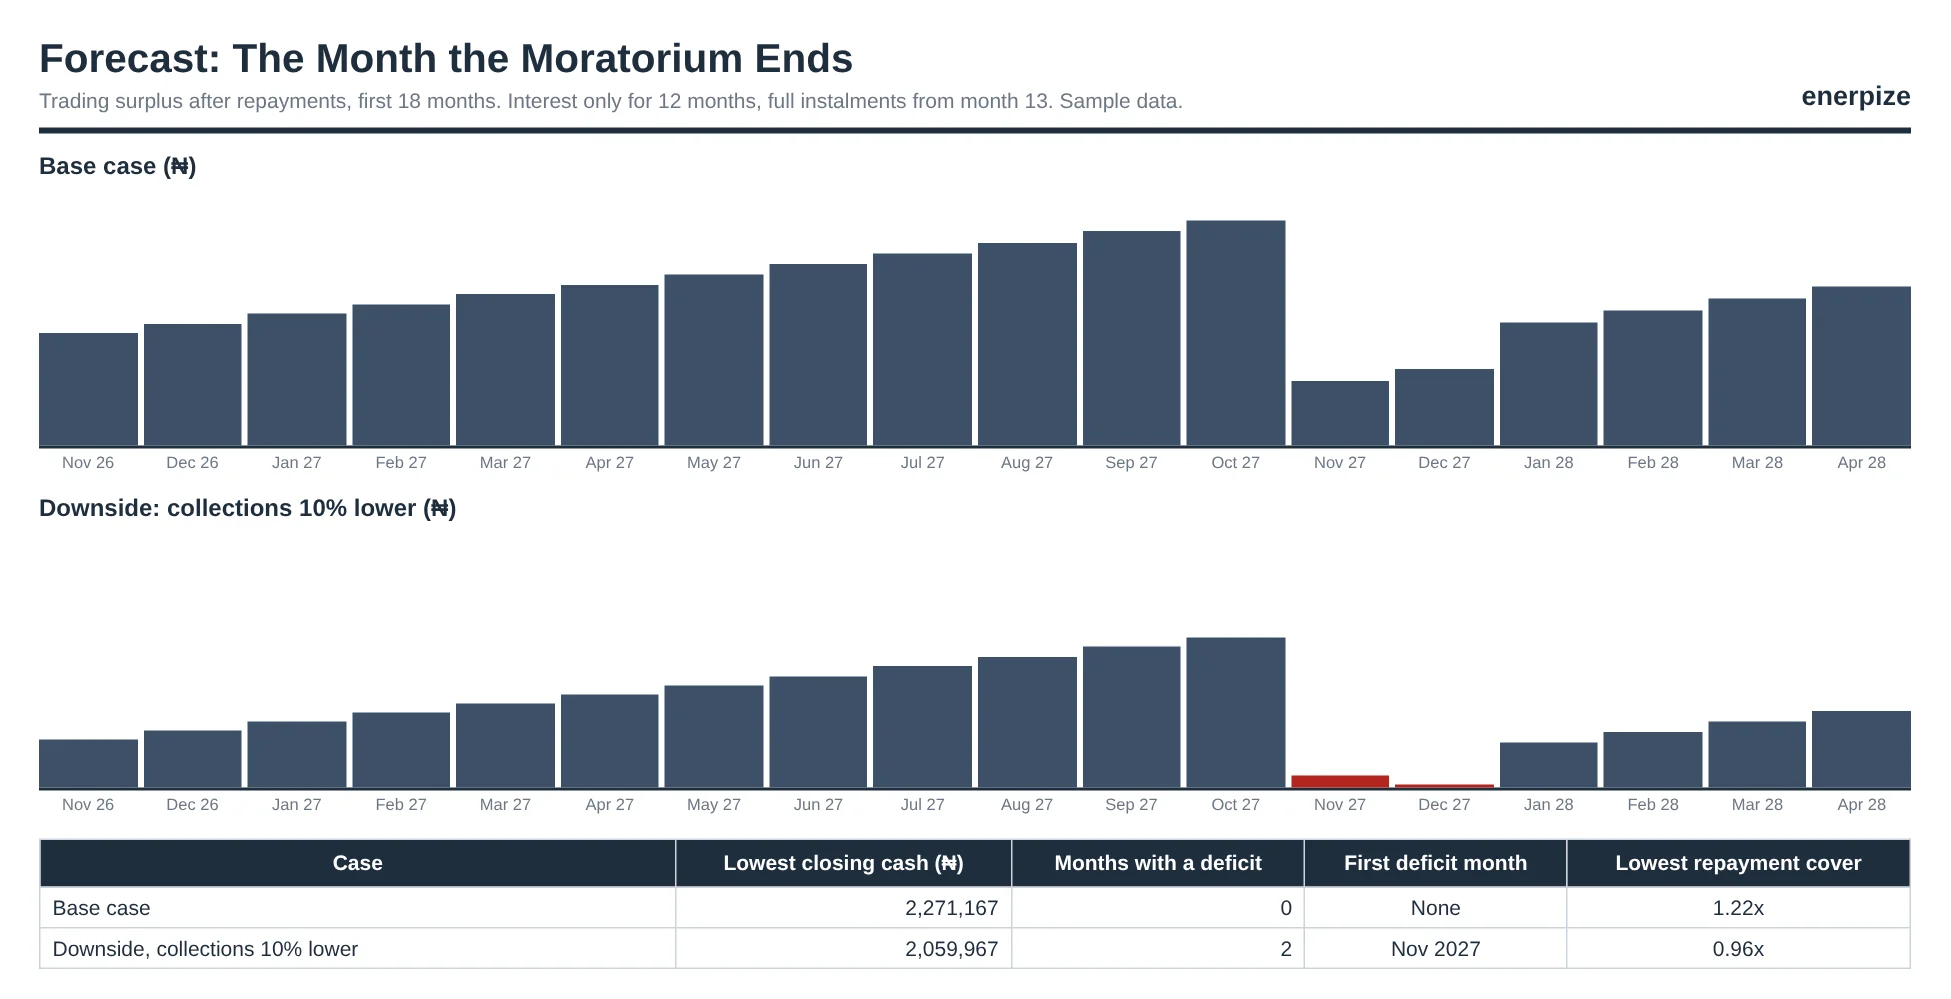
A 12-month moratorium feels like breathing room. Then month 13 arrives and the repayment triples. The Forecast runs 24 months in a base case and a downside case, so you can see that month before you sign.
Management Accounts That Tie Out
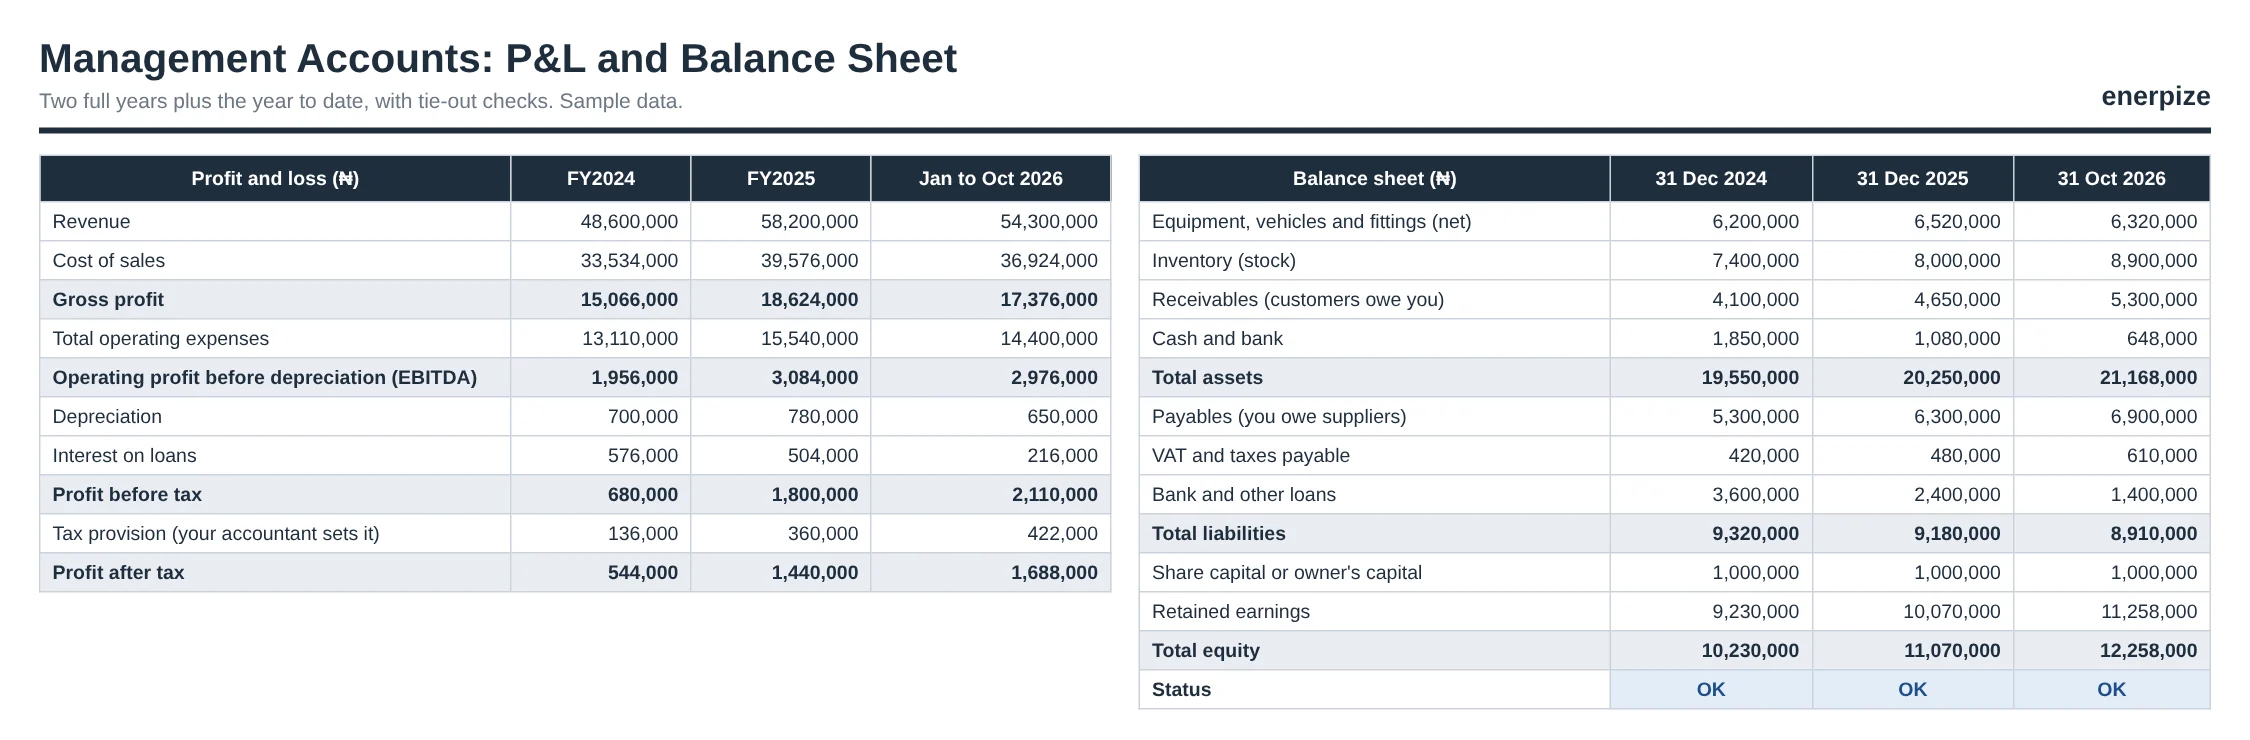
P&L, balance sheet and cash flow for two full years and the current year to date. The Review sheet checks that the balance sheet balances, cash ties to cash, loans tie to the liabilities declared and profit moves retained earnings. Eleven checks, each with what to fix. New to reading a P&L? Our profit and loss statement guide walks through every line.
The Numbers Behind a Personal Guarantee
Access Bank, Wema and BOI all ask for a statement of net worth behind a guarantee. The Net Worth sheet lists what the guarantor owns and owes, and shows net worth as a multiple of the loan. The lender's own form still gets signed and notarized; this is where you prepare its numbers.
Track Record Requirements by Lender
"How long must I have been in business?" Each lender gives a different answer, and some test your turnover as well. These are the published examples built into the workbook, checked on November 15, 2026.
| Lender and product | Trading history | Statements | Turnover or other test |
|---|---|---|---|
| Access Bank Instant Business Loan | 3 months of consistent turnover | Active corporate account | ₦500,000 POS collections in each of the last 3 months |
| Wema Bank Business Support Facility | Not stated | 6 months | Regular credit and debit transactions |
| Sterling Bank Business Support Facility | 3 years of operation | 6 months with Sterling, or 12 elsewhere | 3 years audited accounts above ₦25m |
| LSETF SME Loan | At least 1 year | 6 months corporate statement | 5% equity; Lagos residents |
| BOI small business loan, ₦25m and below | Statement of affairs if under 1 year | 1 year | 1 year audited accounts for existing businesses |
| DavoDani MFB SME Loan | At least 1 year | 6 months | 10% equity and two guarantors |
| Carbon SME loan | 1 year or more | Not stated | ₦1,000,000 or more in monthly revenue |
Notice the spread: business loan requirements in Nigeria differ by 33 months of trading history between two banks.
Example: A Filled Business Loan Documents Pack
Want to see it working before you type anything? Make your own copy of the filled sample in Google Sheets. It follows Lekki Lane Supplies Ltd, a fictional Ikeja distributor of food packaging and cleaning supplies, trading since March 2021. Every name and figure is invented, and the screens on this page use the same sample.
How to Read the Sample
Lekki Lane asks for ₦25,000,000 over 48 months, with 12 months of interest only, to buy a van and bulk stock. The owner adds ₦2,500,000.
₦5.37m a month
₦1.43m
₦270,833
₦842,349
1.22x lowest
Now look at December 2025 and January 2026. Both are flagged: festive cash sales reached the bank on 5 January, so one month looks weak and the next inflated. One line in the note column saves a long conversation at appraisal.
Then switch Settings to the downside case. Collections drop 10%, and months 13 and 14 show small deficits of ₦37,718 and ₦3,628. Cash never falls below ₦2.06 million, so the business survives the cliff. You only know that because you looked.
Business Loan Formulas: Turnover, Rates and Repayments
Every formula is already in the workbook. Here is what each one does, with a number from the sample.
Genuine Turnover
Genuine Turnover = Credits on Statement - Owner Transfers - Loans and Refunds
March 2026: ₦6,450,000 in credits, less a ₦1,500,000 owner transfer, gives ₦4,950,000. That sits within 2% of recorded sales of ₦5,050,000, so it passes.
A Monthly Rate as a Yearly Rate
Quoted Yearly Rate = Monthly Rate x 12 | True Yearly Cost = (1 + Monthly IRR)^12 - 1
5.5% a month is 66% a year before compounding. Add 2.9% in upfront fees on a ₦3,000,000 loan repaid in three instalments, and the true yearly cost is 127.7%.
Instalment After a Moratorium
=PMT(Monthly Rate, Term - Moratorium, -Amount)
₦25,000,000 at 13% a year over the 36 months left after the moratorium gives ₦842,348.80 a month. During the moratorium, interest alone is ₦25,000,000 x 13% / 12 = ₦270,833.33.
Repayment Cover
Repayment Cover = (Collections - Operating Payments) / Loan Repayments
Above 1.0x, trading cash pays the loan. In month 13 of the base case it is 1.22x. In the downside case it falls to 0.96x, which is the month to plan for.
How to Prepare Your Business Loan Documents
Two weeks is a realistic run-up to gather the business loan documents Nigeria lenders expect. The tax clearance certificate and audited accounts set the pace.
1- Get the Lender's Own List
Ask for the product's current document list and mark it on the checklist. Every list in the pack is a published example; the lender in front of you is the only one that counts.
⚡ Tip: Ask what period the statements must cover and whether management accounts are accepted at your loan size.
2- Order the Slow Documents First
Request your CAC status report, tax clearance certificate and bank statements on day one. They come from other people's queues.
⚡ Tip: Ask the bank for statements stamped and signed. Some lenders refuse printouts.
3- Fill in Twelve Months of Track Record
Enter sales from your records, then credits, owner transfers, loans and POS collections from your statement. Explain every flagged month in a sentence.
⚡ Tip: Enter months oldest first and leave no gaps; the lender rules read the latest months.
4- Close Your Management Accounts
Enter two full years and the year to date on P&L and Balance Sheet, then the movements on Cash Flow. Work until every Review check reads OK.
⚡ Tip: Use reconciled figures. A difference of ₦1 still means something is missing.
5- Compare Every Offer
Enter each quote on Loan Cost exactly as written, including fees. Pick the offer for the forecast in Settings.
⚡ Tip: Ask for fees in writing. A management fee and insurance can add 2% or more on day one.
6- Test the Downside
Run the Forecast in base and downside cases and find the month repayment cover is lowest. Decide now what you would cut if it arrives. Need a longer view than 24 months? Use the pro forma cash flow statement.
⚡ Tip: If cover drops below 1.0x, ask for a longer tenor or a smaller first tranche before you sign.
7- Write the Plan From the Numbers
Use the business plan file, and copy every figure from the workbook. Summary first, two pages at most for most SME loans.
⚡ Tip: Name your largest customer's share of sales. Lenders ask anyway.
Common Business Loan Application Mistakes
Most declines are not about the business. They are about the paper.
✕ Running business sales through a personal account
Why it matters: The lender sees thin business turnover and cannot verify the rest.
Fix: Move collections into the business account months before you apply.
✕ Names that do not match
Why it matters: CAC, BVN and bank records spelled three ways stall the KYC check.
Fix: Check every document against the CAC record before you submit.
✕ An expired tax clearance certificate
Why it matters: Some lenders cannot disburse without a current one.
Fix: Request it first, and check the year it covers.
✕ Quoting a monthly rate as if it were yearly
Why it matters: 5.5% a month looks cheap next to 13% a year until you multiply it.
Fix: Compare offers on Loan Cost, fees included.
✕ Forgetting the moratorium ends
Why it matters: Repayments jump in month 13, often in the quiet season.
Fix: Run the downside case and keep a cash reserve for that month.
✕ Leaving existing loans off the declaration
Why it matters: The credit bureau shows them anyway, and trust drops.
Fix: List every loan and overdraft on the Liabilities sheet.
Importance of Preparing Your Business Loan Documents
Why do so few small Nigerian businesses borrow from banks? Part of it is price. Part of it is paperwork. PwC's July 2024 MSME survey of 567 businesses names inadequate access to finance among the issues holding them back, and notes that MSMEs make up 96.9% of businesses and 87.9% of employment in the NBS and SMEDAN 2021 survey.
So what? You cannot change interest rates. You can change how ready you are when you ask.
Faster Appraisal
A complete pack goes straight to analysis. A missing statement goes back to the bottom of the queue.
Better Terms
Clean management accounts and a tested forecast give the lender less to price for. Less uncertainty is the closest thing to a discount you control.
Fewer Surprises After You Sign
Knowing your month 13 before drawdown beats finding it in a bank alert.
Spreadsheet vs Software for Loan Records
The pack gets the business loan documents Nigeria lenders want in order once. Keeping the numbers current is a different job.
| What you need | Loan documents pack | Enerpize |
|---|---|---|
| Cost | Free | Free 14-day trial, then a paid plan; NGLOAN takes 25% off |
| Checklist and loan plan | Built in | Keep these in the pack |
| Management accounts | Typed from your books | Income statement, balance sheet and cash flow from recorded transactions |
| Sales evidence | Copied from records | Invoices, incomes and payments in one place |
How Enerpize Handles Your Loan Records
What happens when the loan officer asks for "September to date, by tomorrow"? In a spreadsheet, you rebuild it. In Enerpize, you pick the dates. The screens below use sample data for Lekki Lane Supplies.
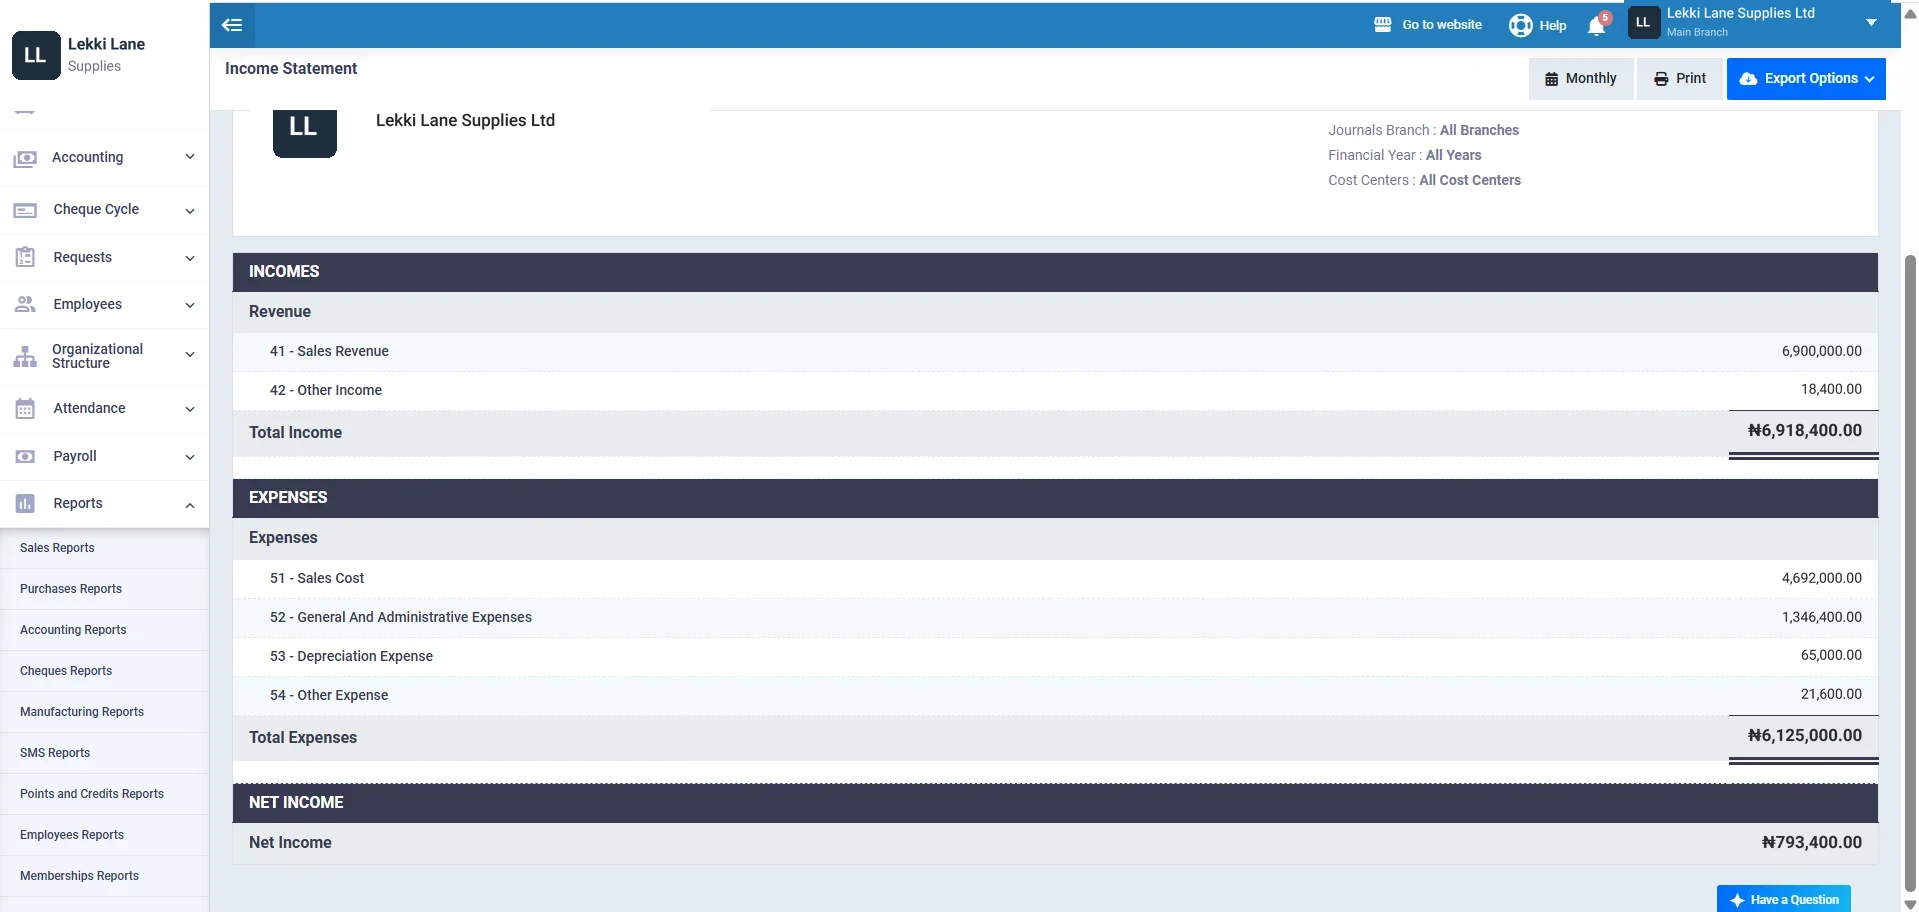
Income Statement: The Month on One Page
Pick a period and branch, and the income statement groups revenue and expenses from what you recorded. Export it or print it for the pack. It is part of Enerpize's accounting software, and in the sample October shows ₦6,918,400 of income and ₦793,400 of net income.
Incomes: Money In, Dated and Described
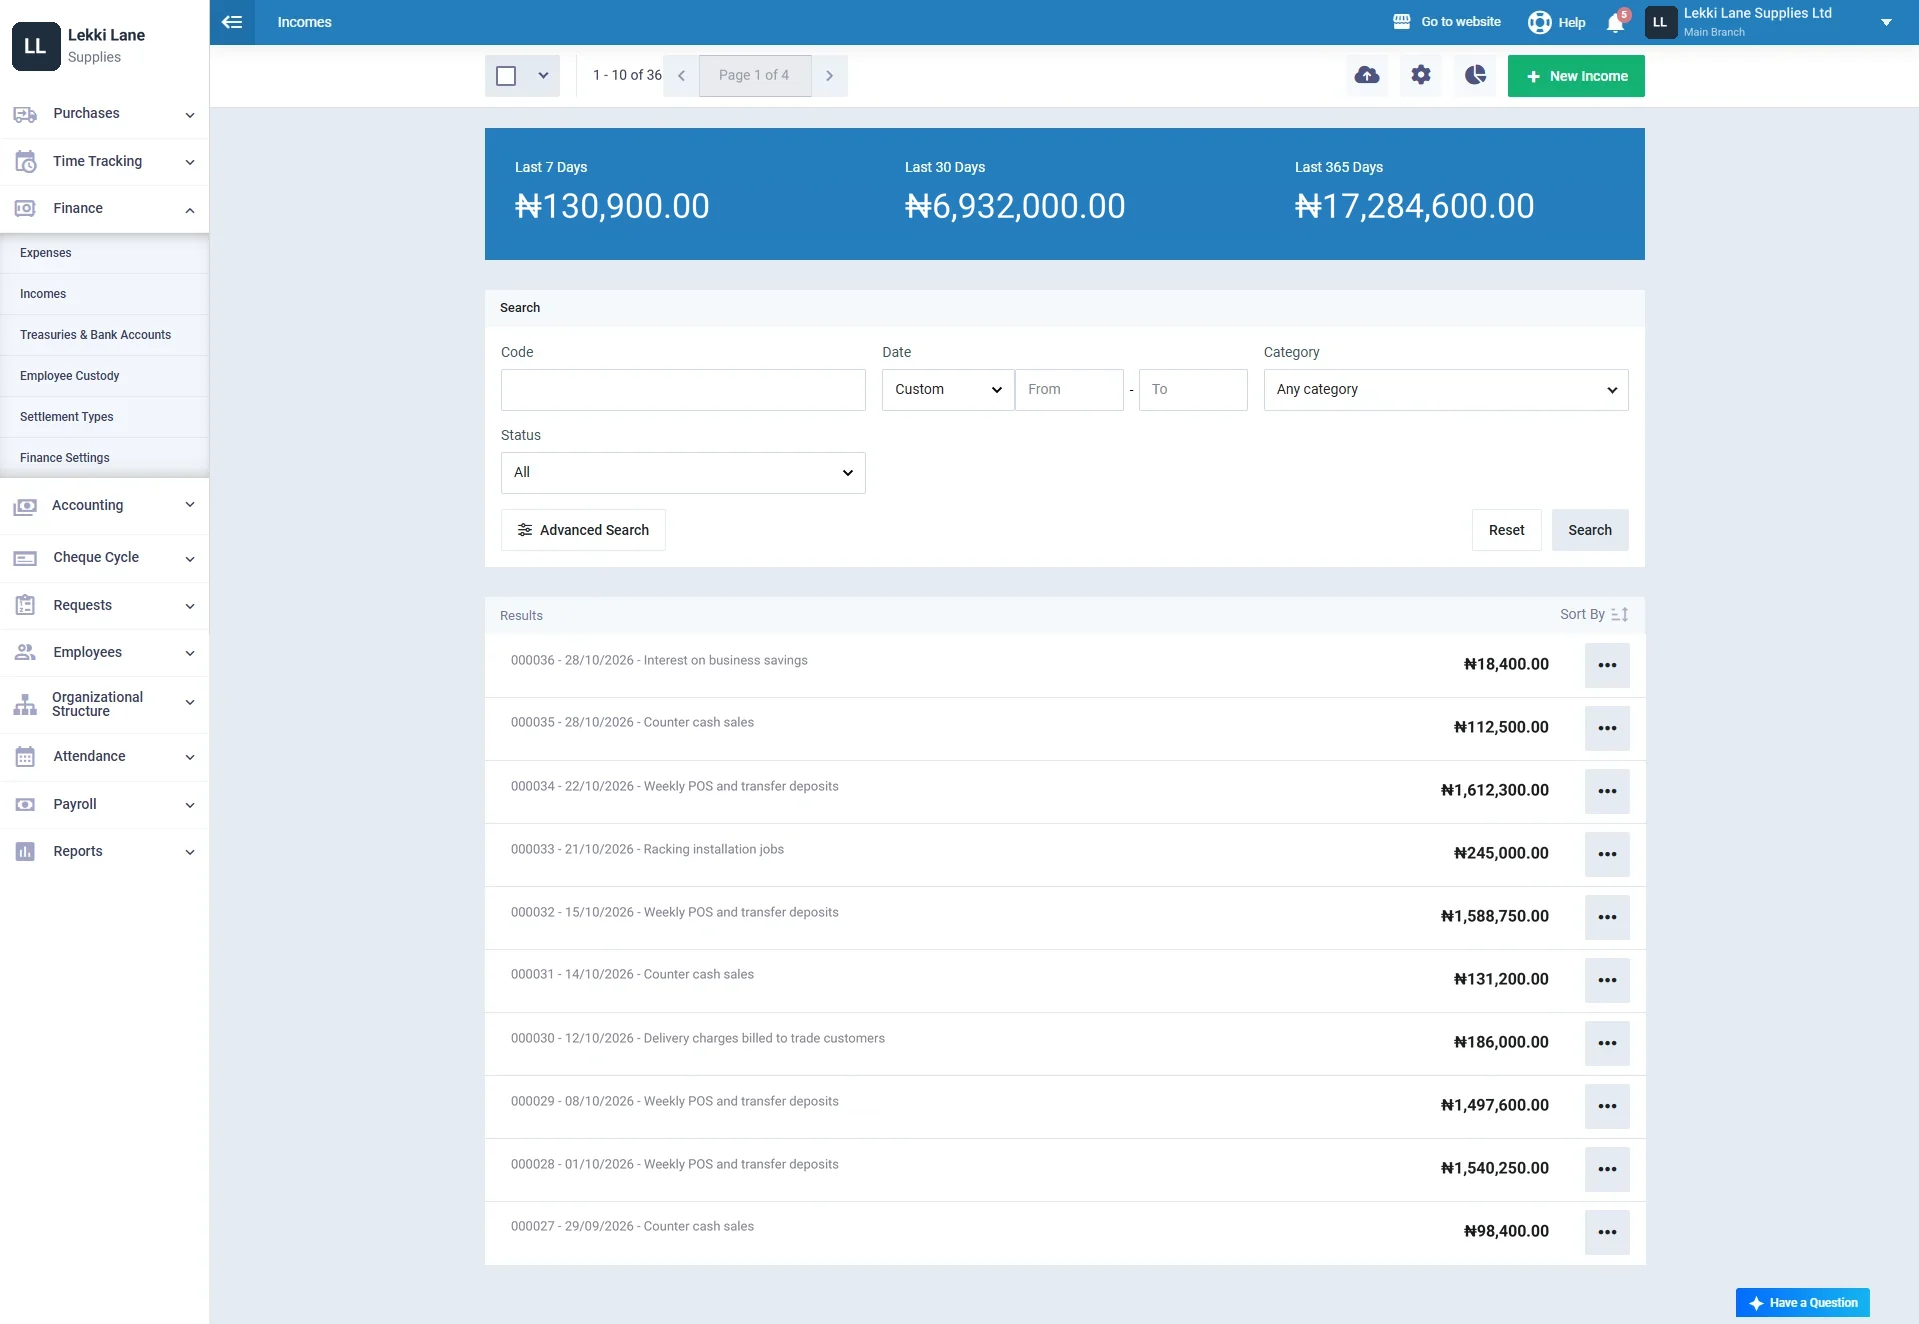
Deposits, counter sales and delivery charges each get a dated record, with 7, 30 and 365 day totals. When a lender asks about a credit, you can find it.
Expenses: Receipts Attached, Details Read
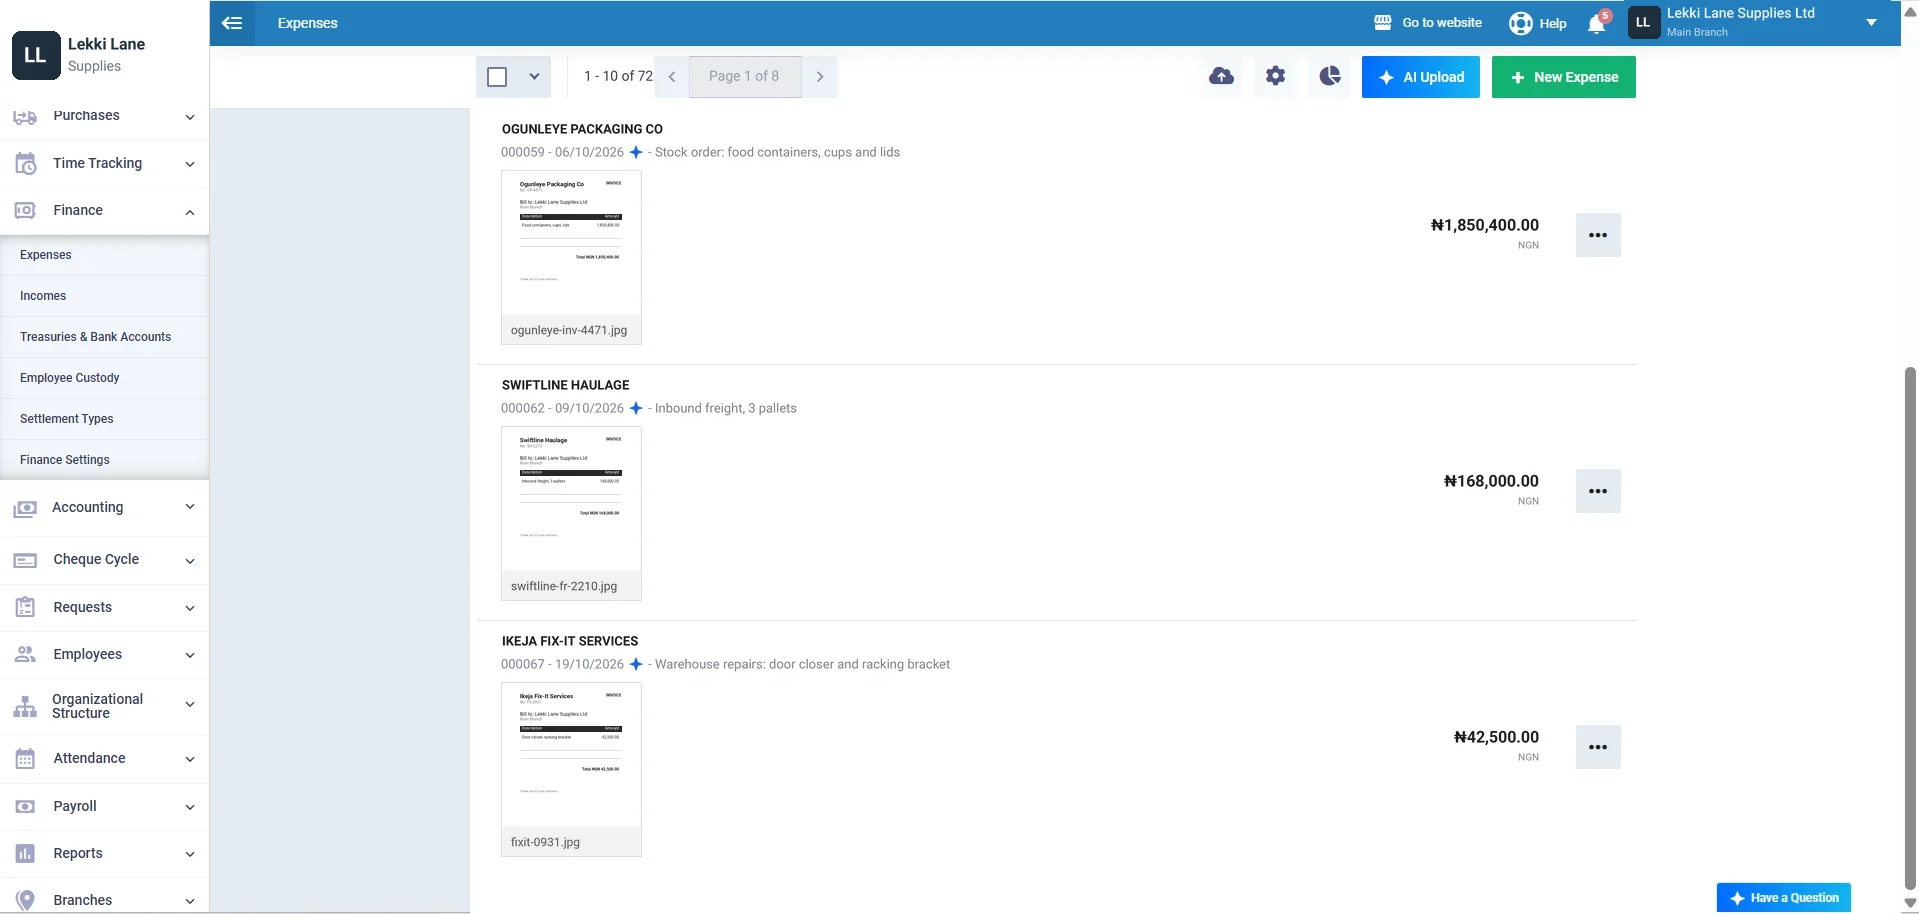
Upload a supplier invoice and the expense management module reads the details into the record, with the file attached. Review it before you approve it. Months later, the receipt is still there when a figure gets questioned.
Balance Sheet: What You Own and Owe, Today
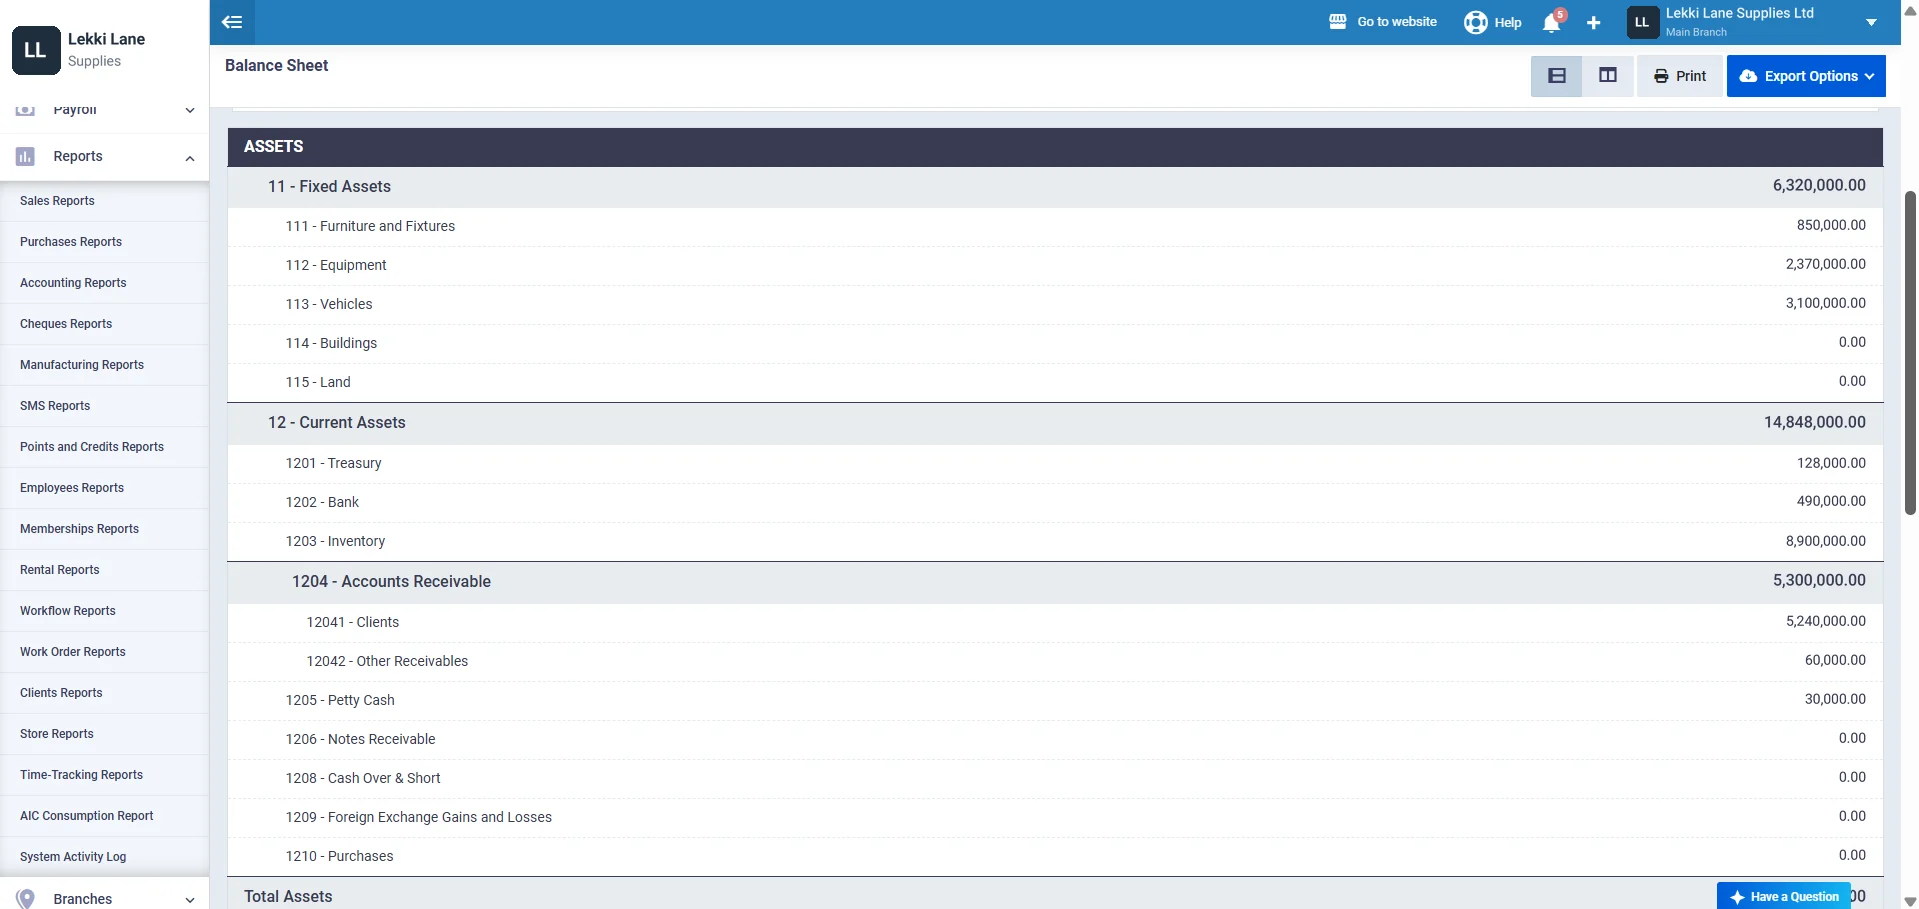
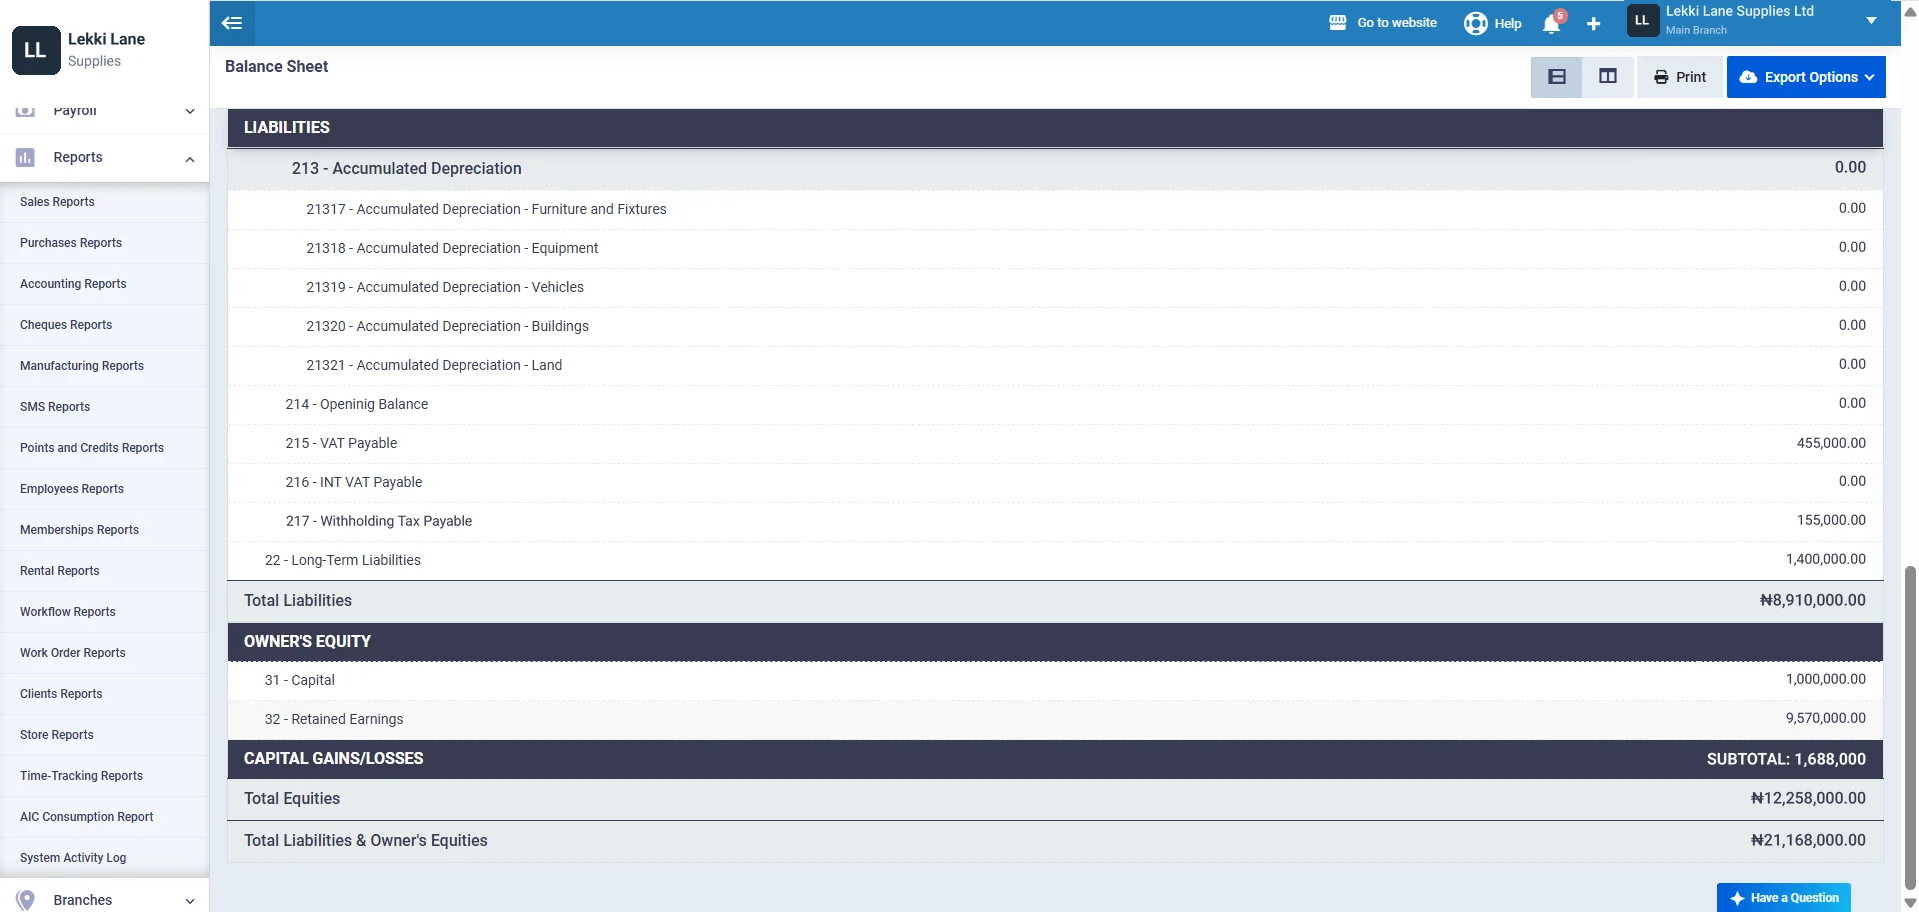
Fixed assets, inventory, receivables and cash on one side; payables, taxes, loans and equity on the other. The sample shows ₦21,168,000 of assets against ₦8,910,000 of liabilities.
Cash Flow Report: Why Cash Moved
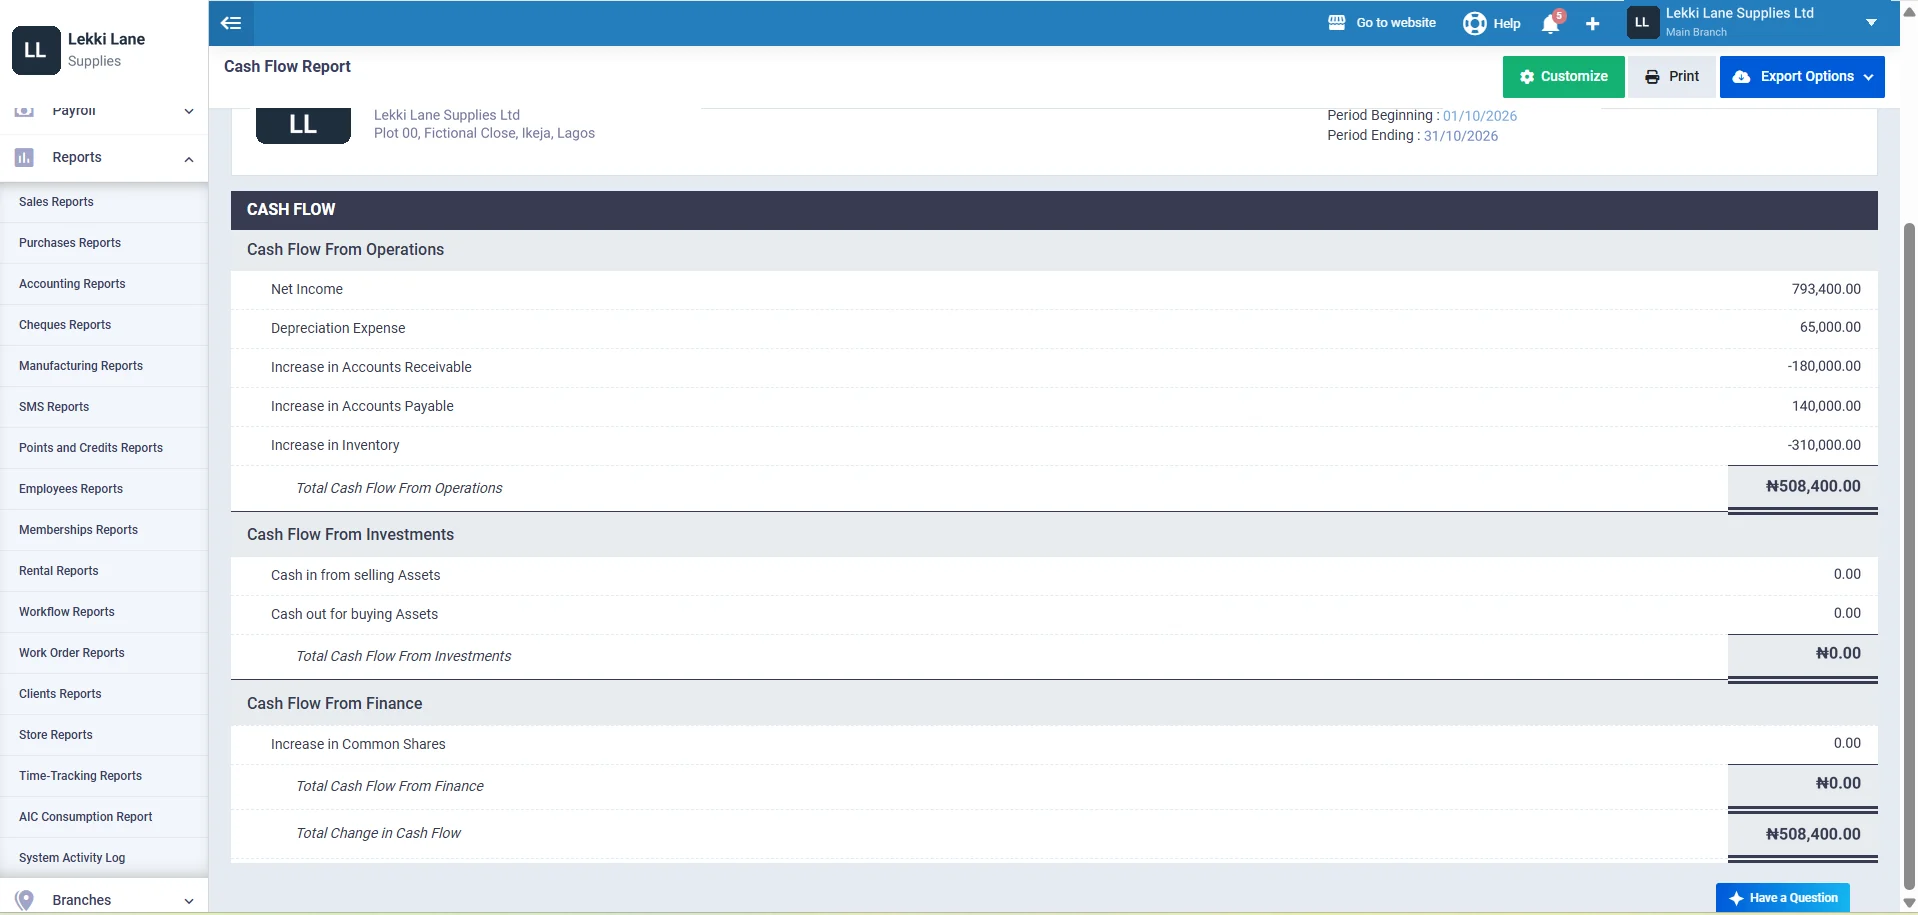
The cash flow report starts from net income and adjusts for depreciation, receivables, payables and inventory, then shows investing and financing. It answers the lender's favorite question: if you made a profit, where is the cash?
Trial Balance: The Check Your Auditor Starts With
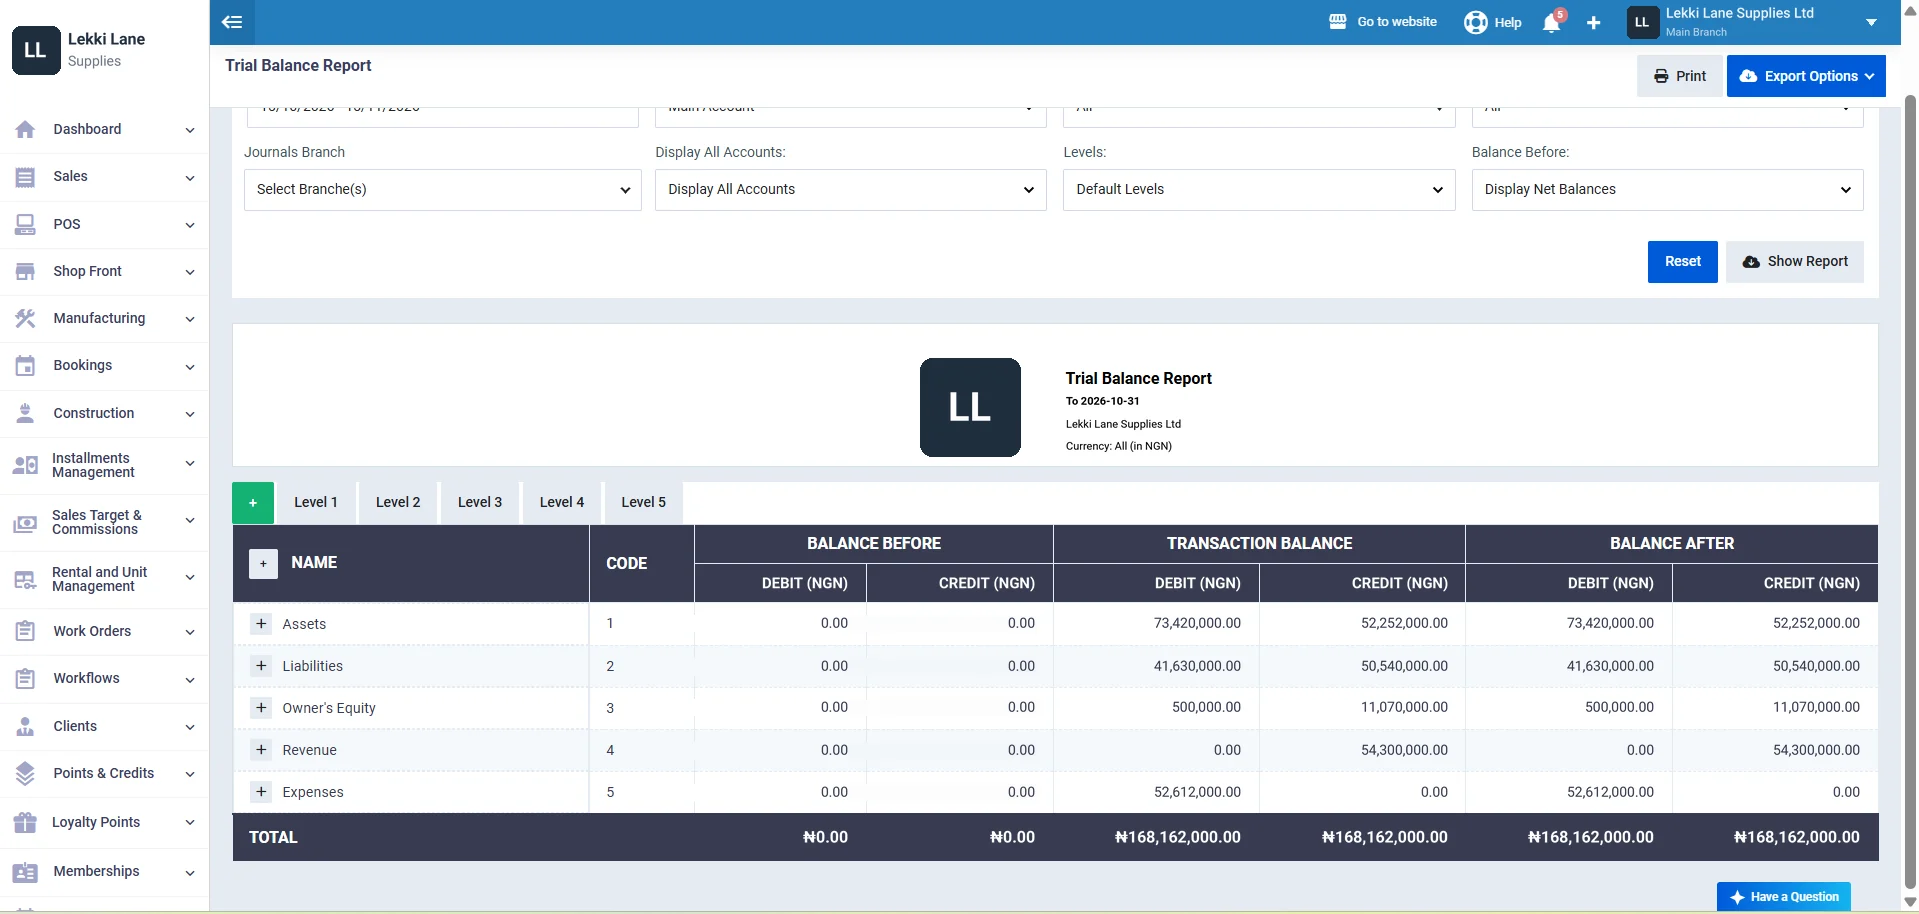
Debits equal credits, by level, for any period. If your accounts need an audit for a larger loan, this is the report your auditor will ask for first.
Your 25% loan pack discount
Code NGLOAN takes 25% off any Enerpize plan. Start your free trial, then from your dashboard click Upgrade, choose your plan, click Confirm, open Additional Options, enter NGLOAN and click Apply.
Business Loan Documents for Commercial Banks
Banks are the usual first stop for business loan documents in Nigeria, and their lists vary most by product.
Access Bank's Instant Business Loan terms ask for an active account with at least 3 months of consistent turnover, minimum POS collections of ₦500,000 in each of the last three months, a board resolution for companies, and a personal guarantee with a notarized statement of net worth. The rate is 5.5% a month on the reducing balance, with 1% management, 1% advisory and 0.9% insurance fees. Sterling Bank wants 3 years of audited accounts from an approved auditor for amounts above ₦25m, while Union Bank offers cash flow lending of up to ₦10m with no collateral, open to registered and unregistered businesses.
What to add:
- The bank's own rule as a new row in Settings, if it is not listed
- POS collections for each month on Track Record
- The monthly rate and every fee on Loan Cost
⚑ Practical note: Wema's Business Support Facility asks for undated cheques from another bank and a GSI mandate. Ask about recovery mandates early; they reach accounts beyond the lending bank.
Business Loan Documents for the Bank of Industry
BOI asks for more paper than most lenders, and rewards it with longer terms.
BOI's on-lending programme for women-owned SMEs lends through commercial banks at 13% a year, for up to 4 years including a 12-month moratorium. Its list includes three years of audited accounts and recent management accounts, or a statement of affairs for businesses under one year old, a year of company bank statements and a declaration of outstanding liabilities. For loans of ₦25m and below, BOI's checklist for limited liability companies asks for one year of audited accounts and recent management accounts from BOI-accredited auditors for existing businesses.
What to add:
- The moratorium on Loan Cost, so the forecast shows the jump
- Proforma invoices for every item you will buy
- The Liabilities sheet, printed as your declaration
⚑ Practical note: Under CAMA 2020, a qualifying small company with turnover up to ₦120m and net assets up to ₦60m need not appoint auditors. BOI and some banks still ask for audited accounts, so check before you assume the exemption covers your loan.
Business Loan Documents for LSETF in Lagos
Cheaper money, for a narrower group.
The Lagos State Employment Trust Fund charges 9% a year. Its SME loan runs from ₦500,000 to ₦5,000,000 over 24 to 36 months, with 5% equity. It asks for a LASSRA ID, a Lagos IRS tax ID, a valid ID, CAC documents, BVN, two passport photographs and 6 months of corporate bank statements, and the business must be registered and operating for at least a year.
What to add:
- 5% of the loan as your owner contribution in Settings
- The LSETF row in the lender rules, already included
- Your LASSRA and LIRS numbers on the checklist
⚑ Practical note: Micro loans up to ₦500,000 have a 12-month tenor with no moratorium. Monthly repayments start straight away, so test the first month, not month 13.
Business Loan Documents for Microfinance Banks and Fintechs
Lighter lists, faster answers, higher prices.
DavoDani Microfinance Bank's SME loan asks for a business in existence for at least a year, 6 months of statements, 10% equity, two guarantors and adequate collateral, with MEMART and a board resolution for companies. Carbon's published SME loan criteria are CAC registration, a valid TIN, at least one year in business and monthly revenue of ₦1,000,000 or more.
What to add:
- Guarantor details from the Net Worth sheet
- The monthly rate, so the true yearly cost is visible
- Your lowest monthly turnover, not your average
⚑ Practical note: Short loans at monthly rates are useful for a stock gap with a clear payback. They are expensive for anything slower. Check the true yearly cost before you borrow for equipment.
Who Can Use the Business Loan Documents Pack?
Traders and Distributors
Stock bought on credit, sold on 30-day terms. Your turnover is strong and your cash is tight, which is exactly what Track Record and the forecast explain. Running a shop as well? See retail store management.
Manufacturers and Processors
The natural BOI applicant. Add the feasibility section to the plan and attach machinery quotes. The manufacturing software page shows how production costs land in your accounts.
Clinics and Schools
Fees and patient income arrive in seasons. Run the downside case for the quiet term. Clinics can see clinic management for how patient billing feeds the books.
Businesses Under One Year Old
No history yet? Use the Balance Sheet's last column as your statement of affairs, write the forecast carefully, and apply to lenders that accept it, such as BOI.
Business Loan Glossary
| Term | What it means |
|---|---|
| BVN | Bank Verification Number, used for identity and credit bureau checks. |
| GSI | Global Standing Instruction: lets a lender recover a missed repayment from your accounts at other banks. |
| Statement of affairs | A snapshot of assets and liabilities for a business without full accounts. |
| Management accounts | Accounts you prepare from your books, usually for the months since the last audit. |
| Moratorium | A period at the start of a loan when you pay interest only, or nothing. |
| Equity contribution | The share of the project you pay yourself, often 5% to 30%. |
| Statement of net worth | A guarantor's assets minus debts, usually notarized. |
Key Takeaways
- Business loan documents in Nigeria come from several issuers: CAC, NRS or your state IRS, your bank, your auditor and you. Start with the slow ones.
- Your bank statement carries the decision. Strip out owner transfers and loans, and explain any month more than 10% from your sales records.
- Track record rules range from 3 months of turnover at Access Bank to 3 years of operation at Sterling's Business Support Facility.
- A rate of 5.5% a month is 66% a year before compounding; with 2.9% fees on a three-month loan, the true yearly cost in the sample is 127.7%.
- A 12-month moratorium on ₦25,000,000 at 13% means ₦270,833 a month, then ₦842,349 from month 13.
- Run a downside case. In the sample, 10% lower collections push repayment cover to 0.96x in month 13.
- Small companies may be exempt from audit under CAMA 2020, but BOI and some banks still ask for audited accounts.
- The pack is free in Excel, Google Sheets, Word and PDF, and code NGLOAN takes 25% off Enerpize when you are ready to keep the records in software.
Frequently Asked Questions
What documents are required for a business loan in Nigeria?
Most lenders ask for CAC documents, directors' ID and BVN, a tax ID and often a tax clearance certificate, 6 to 12 months of business bank statements, financial statements, a business plan and existing loan details. Secured loans add collateral and guarantees.
Can I get a business loan with a business name, not a limited company?
Yes, with some lenders. Union Bank's cash flow lending is open to registered and unregistered businesses, and Wema's facility is open to people trading in their own names. You skip MEMART and board resolutions, but lenders lean harder on your statements.
How many months of bank statements do I need for a loan?
Usually 6 to 12. Wema and LSETF ask for 6 months, BOI asks for a year, and Sterling asks for 6 months if you bank with it or 12 months from other banks. Access Bank's instant loan looks at the last 3 months of turnover.
Do small companies need audited accounts for a loan?
Under CAMA 2020, a qualifying small company need not appoint auditors. Lenders set their own rules, though. Sterling asks for 3 years of audited accounts above ₦25m, and BOI asks for audited accounts for existing businesses, so check with your lender.
How do I get a tax clearance certificate for a loan?
Apply to the tax authority that assesses you: the Nigeria Revenue Service, which replaced FIRS from January 1, 2026, or your state internal revenue service. File your returns first. Start early, because many lenders cannot disburse without a current certificate.
Can I get a business loan without collateral in Nigeria?
Yes, for smaller amounts. Union Bank's cash flow lending goes up to ₦10m without collateral, and Wema's facility up to ₦5m. Expect a personal guarantee, a statement of net worth and a GSI or direct debit mandate instead.
What is a statement of net worth for a loan?
A list of a guarantor's assets and debts, showing what they are worth overall. Lenders such as Access Bank, Wema and BOI ask for one, often notarized, behind a personal guarantee. The Net Worth sheet in this pack helps you prepare the figures.
Will preparing these documents guarantee loan approval?
No. A complete pack speeds up appraisal, but the lender still assesses your credit history, cash flow, security and its own policy. Preparation improves your position; it does not decide the outcome.
About the Author
Omar El Bahr is a Senior Digital Growth Specialist at Enerpize, where he leads SEO, content strategy, and organic growth across international markets. He is a Forbes Communications Council contributor and has written for Entrepreneur on business communication and digital strategy.
Disclaimer
This pack and page are general information, not financial, credit, tax or legal advice. Lender requirements, rates and fees change; the examples here were checked on November 15, 2026. Confirm terms with the lender and take qualified advice for your situation. The templates do not replace official documents or the lender's own forms.