Posted on 21 October 2025
Free Cash Reconciliation Template in Excel, Google Sheets, Word and PDF
- Available to download for free in Excel, Google Sheets, Word and PDF, with a filled sample you can copy
- Works out expected cash for each drawer from the float, cash sales, refunds, paid outs and cash drops, then marks every shift Balanced, Over, Short or Investigate
- Counts notes and coins, loose and rolled, and follows every deposit to the bank with slip numbers, credit dates and bank differences
- Totals over and short by cashier and drawer, flags repeat shortages
A cash reconciliation template is a form or spreadsheet that compares the cash a business should have, based on its opening float, cash sales, refunds and payouts, with the cash actually counted, then records any amount over or short with a reason and tracks the deposit until the bank credits it.


Last updated: November 11, 2026
What it is
A cash reconciliation template that checks the cash in each drawer against what the till says it should hold, then follows the deposit until the bank credits it.
When you need it
At the end of every shift, before the float goes back in the safe, and again at month end before you close the books.
What's inside
A daily reconciliation log for up to 6 drawers, a note and coin count, deposit tracking, a variance summary by cashier, a month-end proof and a printable daily sheet.
Formats
Excel, Google Sheets, Word and PDF. The Word and PDF files are a one-page cash drawer reconciliation form for filling in by hand.
Want to see it filled in first?
Make your own copy of the filled sample in Google Sheets.
What Is the Cash Reconciliation Template?
Closing time. The lights are half off, the last customer is gone, and the drawer is $25 short.
Was it the wrong change at 2 p.m.? A refund nobody rang up? A $20 note that walked out in someone's pocket?
Without a record, you'll never know. With one, you'll usually know before you lock the door.
A cash reconciliation template is a form or spreadsheet that compares the cash a business should have, worked out from its opening float, cash sales, refunds and payouts, with the cash actually counted. Any gap is recorded as over or short, explained, and carried through to the bank deposit.
You'll hear it called a cash reconciliation sheet, a cash reconciliation form, a cash drawer reconciliation sheet, a cash register reconciliation or simply a cash count sheet. Same job, every time: prove that the money in your hand matches the money in your records.
cash in at the start
cash taken in
what should be there
what is there
the gap, explained
to the bank
Here's what it isn't. It isn't a bank reconciliation, which compares your books with a bank statement. It isn't a daily cash report, which logs every receipt and payment by category. And it isn't petty cash, which is a separate fund for small purchases. A cash reconciliation is the checkpoint between the till and the bank.
Cash Reconciliation vs Bank Reconciliation vs Petty Cash Reconciliation
Ask an accountant and a shop manager what "cash reconciliation" means, and you may get two different answers. Both are right. They just sit at different points on the same road.
| Document | What it compares | When it's done | Who usually does it |
|---|---|---|---|
| Cash reconciliation | Counted cash in a drawer against expected cash from sales and payouts | Every shift or every day | Cashier and a second counter |
| Bank reconciliation | Your cash book against the bank statement | Monthly | Bookkeeper or accountant |
| Petty cash reconciliation | A small office fund against its vouchers | At each count or top up | The fund custodian |
| Daily cash report | Every receipt and payment of the day, by category | Daily | Store or office manager |
| Cash flow statement | Cash in and out across the whole business | Monthly or quarterly | Accountant |
A cash reconciliation proves the drawer, a bank reconciliation proves the bank, and the deposit slip is the bridge between them.
A drawer can balance to the cent while the deposit still arrives $20 short. The bank reconciliation template picks up from there.
Which Cash Reconciliation Format Fits Your Business?
A florist with one till and a pharmacy with four registers need the same daily cash reconciliation logic, not the same file. Start from where your cash lives. Need something else entirely? Browse all free business templates.
| If your situation is... | Use this | Where to find it |
|---|---|---|
| One or more registers, cash counted at the end of each shift | Daily cash reconciliation log | Daily Reconciliation sheet |
| You want to count the drawer note by note and coin by coin | Cash count with loose and rolled coins | Cash Count sheet |
| Staff count on paper at the counter | One-page cash drawer reconciliation form | Word and PDF files |
| You need to see which cashier keeps coming up short | Variance summary by cashier and drawer | Variance Summary sheet |
| You keep a small office fund for stamps and parking | A dedicated petty cash reconciliation form | A separate download |
| You want a full log of the day's receipts and payments | A dedicated daily cash report | A separate download |
What Does the Cash Reconciliation Template Contain?
Every field on the cash reconciliation sheet answers one question an owner, an auditor or a tired cashier will eventually ask.
| Field | What goes in it | Why it matters |
|---|---|---|
| Date, shift, drawer and cashier | Who held which drawer, and when | Puts a name on every shortage |
| Opening float | The cash counted into the drawer at the start | A wrong float makes a perfect shift look short |
| Cash sales (Z report) | The cash total from the register report | The POS is the source, not memory |
| Cash refunds and paid outs | Cash that left the drawer for a reason | Unrecorded paid outs look exactly like theft |
| Cash drops to safe | Cash pulled out during the shift | Forget a drop and the drawer reads $500 short |
| Expected cash | What the drawer should hold | The benchmark for the count |
| Counted cash | The physical count, by two people | The only number that's real |
| Over (short) and reason | Counted minus expected, with a reason | Turns a gap into a fact you can act on |
| Deposit, slip and bank credit | What went to the bank, and when it arrived | Closes the loop with the bank |
The field people forget is cash drops. On a busy Saturday, a manager pulls $500 to the safe at 3 p.m. If that drop isn't on the sheet, the drawer reads $500 short at close, and an honest cashier spends an hour feeling accused.
What the Enerpize Cash Reconciliation Template Includes
The old version of this page offered a simple sheet with an opening balance, cash in, cash out and a difference. Every one of those fields is still here. What we added are the questions that come after the difference: who, how often, and did the money actually reach the bank? It runs on formulas only, with no macros, and yellow cells are the only ones you type in.
Two Counts, One Signature
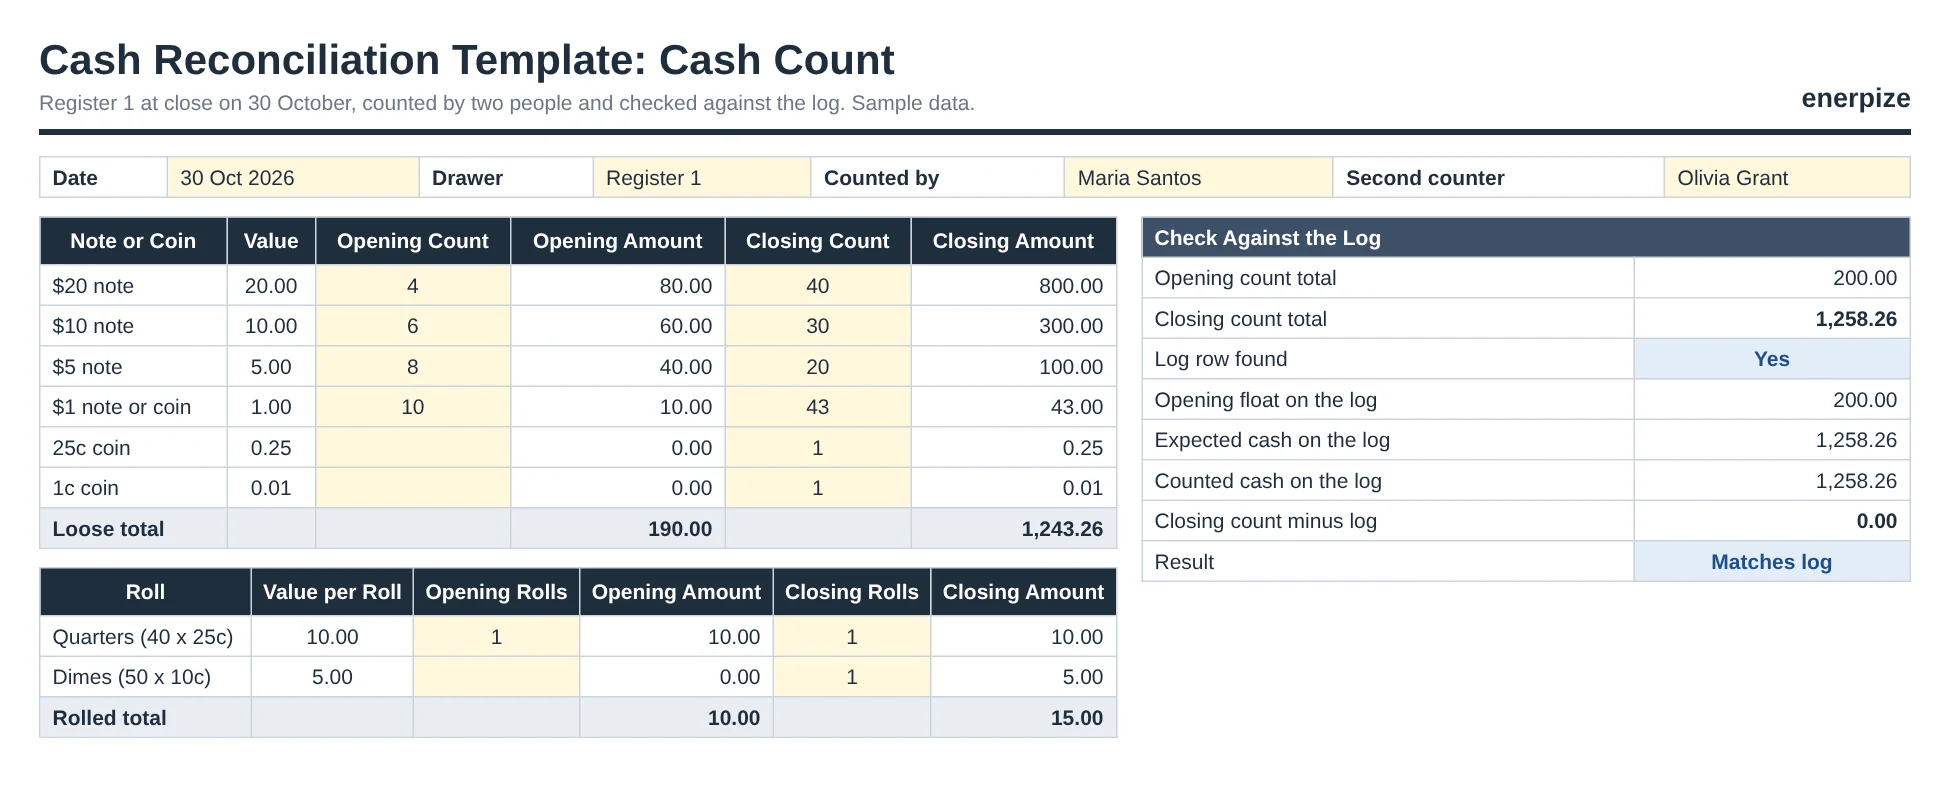
The Cash Count sheet takes the drawer note by note, with loose and rolled coins counted separately and the opening and closing counts side by side. Pick the date and drawer, and it checks the count against the log. In the sample, Register 1 closes at 1,258.26 on October 30 and the sheet says "Matches log".
A Tolerance Band, Not a Witch Hunt
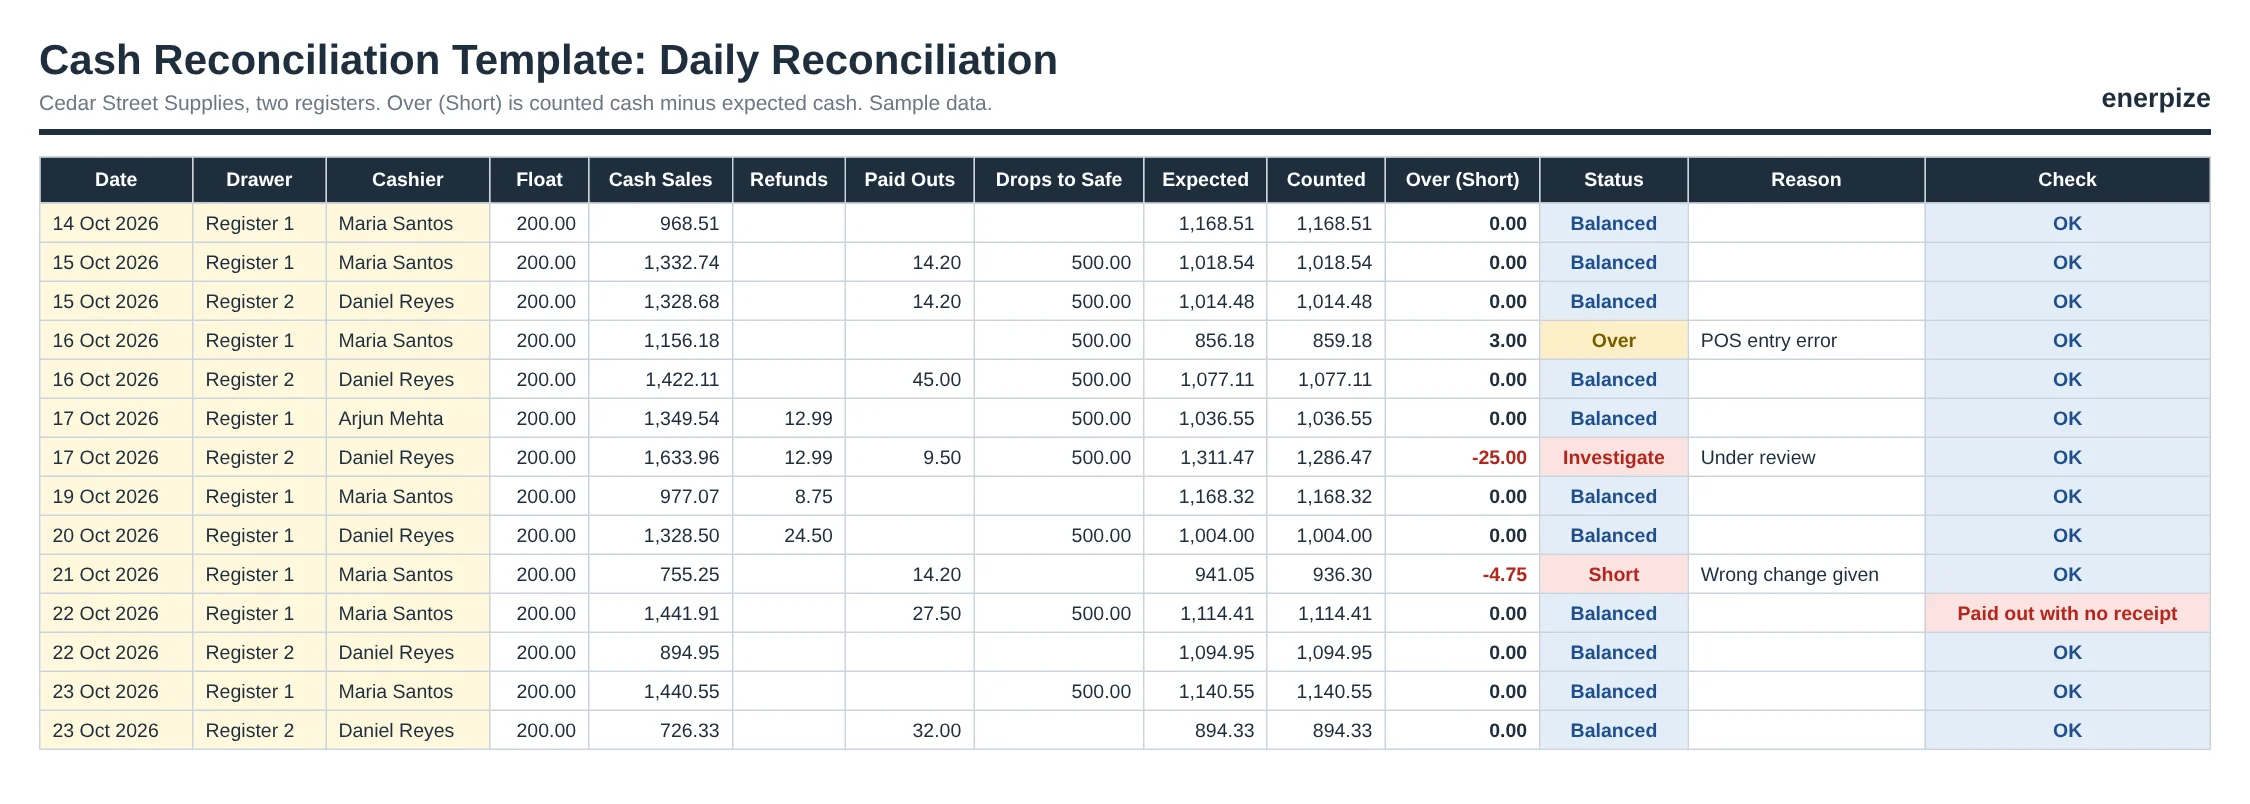
Not every cent deserves a meeting. You set a tolerance, $2 in the sample, and an investigate amount, $20. A 1.50 overage shows Within Tolerance. A 4.75 shortage shows Short. A 25.00 shortage shows Investigate, so the recount happens before the cashier leaves.
Every Deposit Gets a Tracking Number
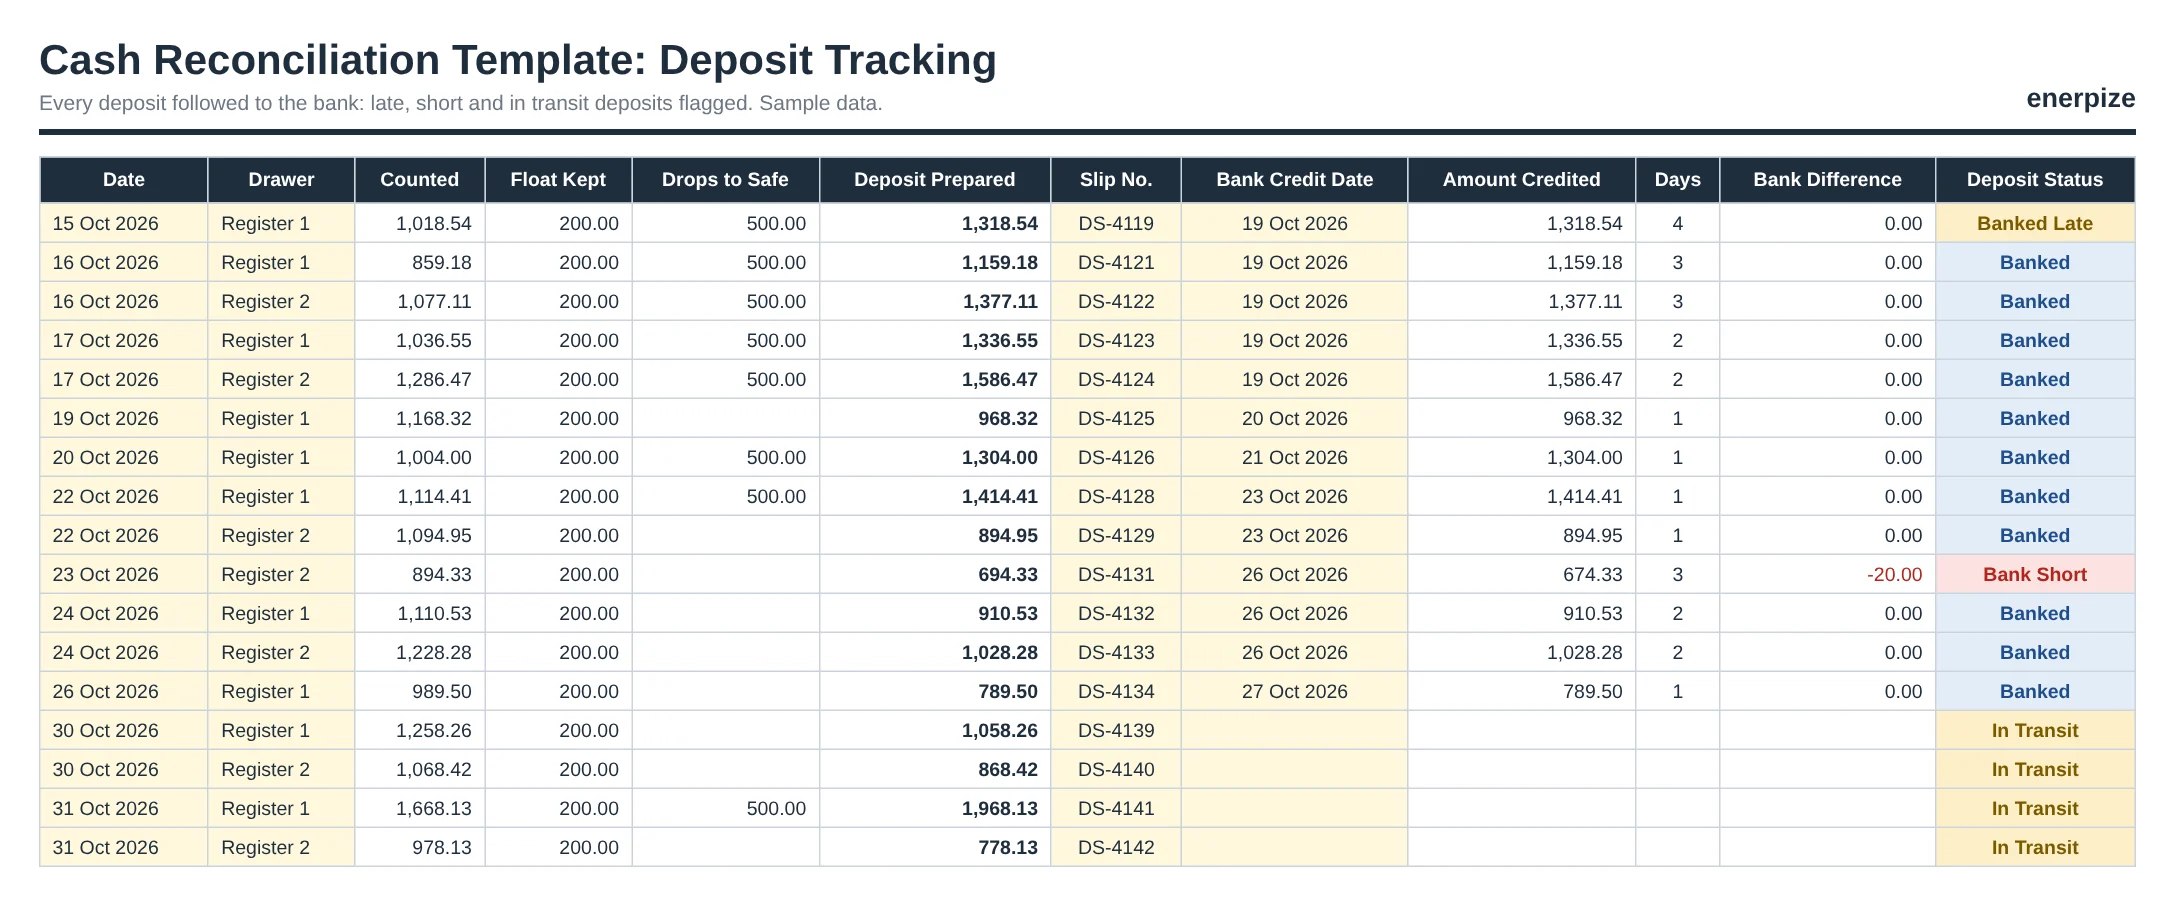
Each row works out the deposit: counted cash, minus the float you keep, plus any cash drops. Add the slip number and the date the bank credited it, and the sheet counts the days in transit. Late deposits, missing deposits and short credits all get a flag.
Patterns Don't Hide in Monthly Totals
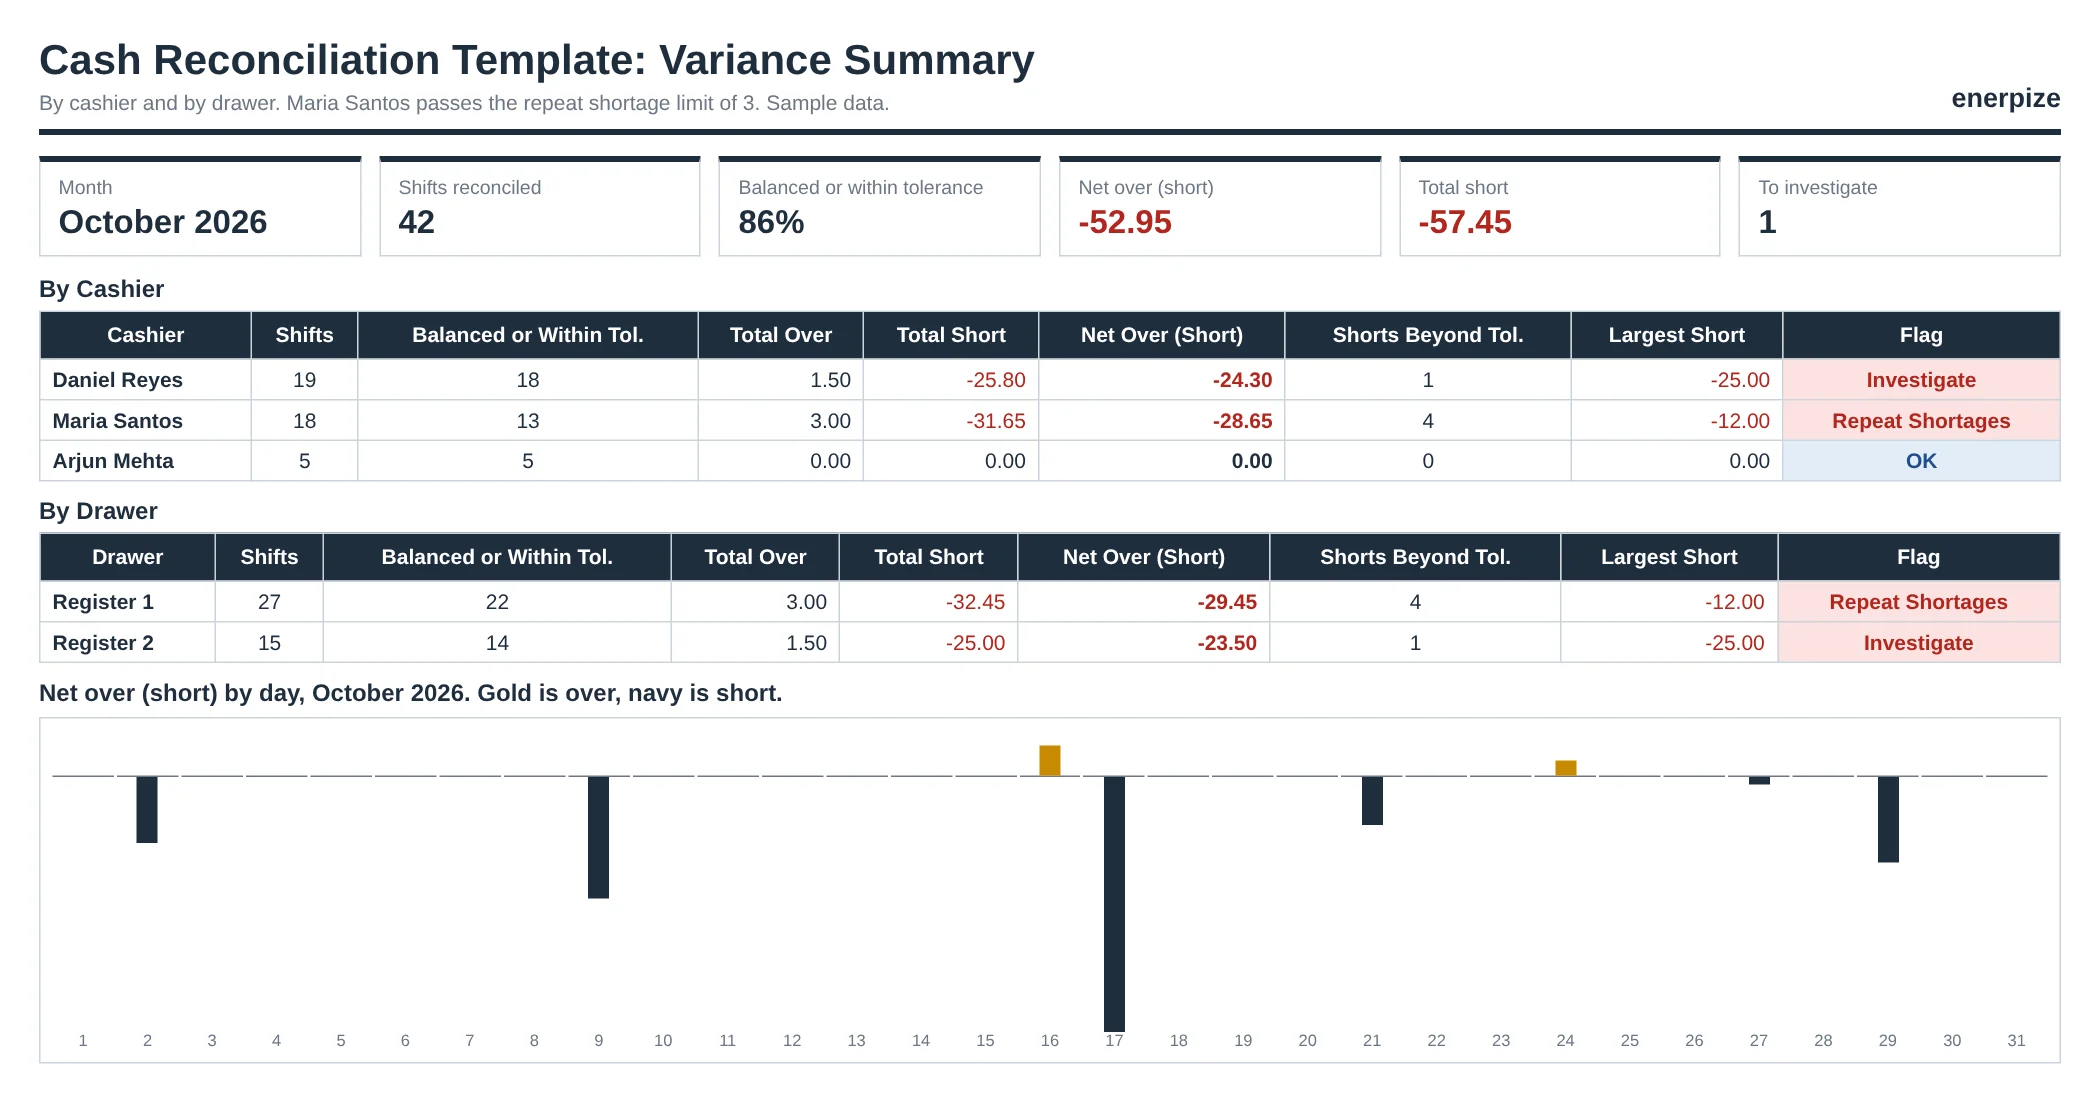
A net shortage of 52.95 for the month sounds small. Split it by cashier and one name holds 4 shortages beyond tolerance. Set a repeat limit, 3 in the sample, and the Variance Summary flags Repeat Shortages, with a day by day chart beside it.
The Month Closes on a Proof
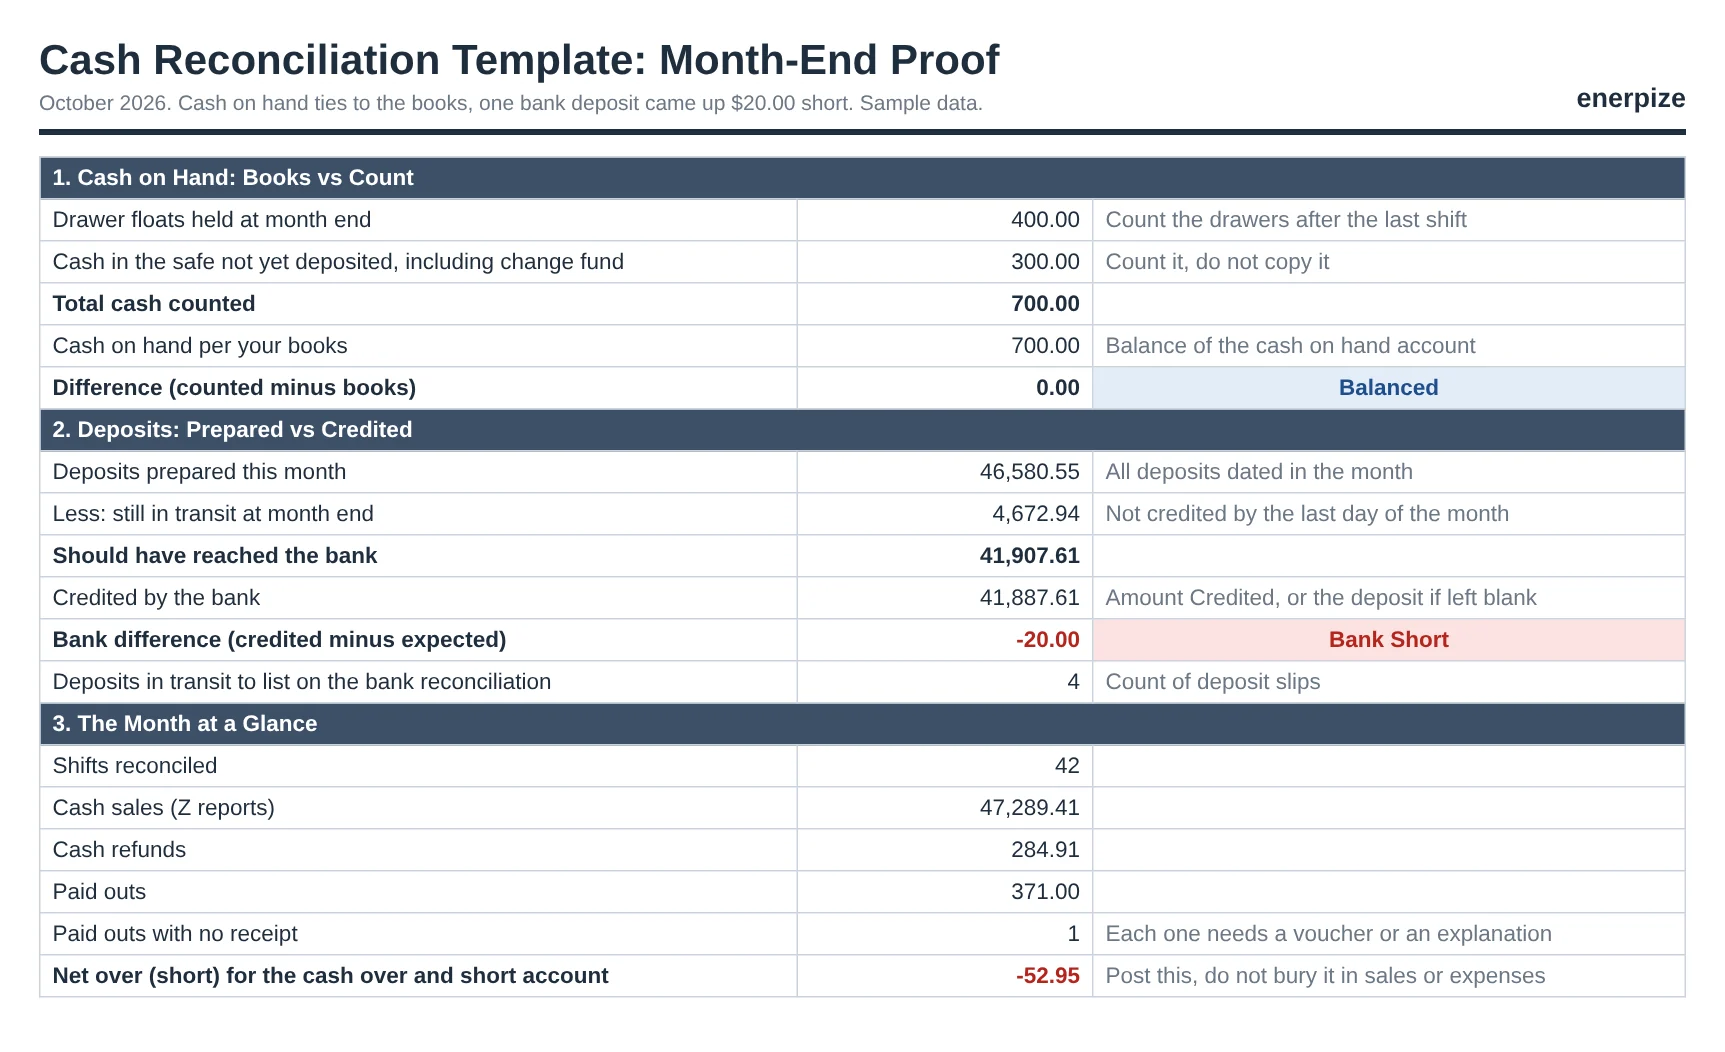
Month-End Proof does two checks. First, the cash on hand in your books against floats and safe cash you actually counted. Second, deposits prepared against deposits the bank credited, with the ones still in transit listed for your bank reconciliation.
The Excel cash reconciliation template does all the math. The Word and PDF versions give you the same count on paper, and the Google Sheets copy works like the Excel file.
Over, Short or Investigate: Reading the Status Colors
Agree on what each word means before the first count. Otherwise "short" means a crisis to one manager and a rounding error to another.
| Status | What it means | What to do |
|---|---|---|
| Balanced | Counted cash matches expected cash to the cent | File the sheet |
| Within Tolerance | Off by no more than your tolerance | Record it and move on |
| Over | More cash than expected, above tolerance | Look for an unrung sale or a missed refund |
| Short | Less cash than expected, above tolerance | Pick a reason before the sheet is signed |
| Investigate | Over or short by your investigate amount or more | Recount with a second person, now |
| Banked Late | The bank credited it after your deposit limit | Ask who held the bag, and where |
| Bank Short | The bank credited less than you deposited | Check the slip and contact the bank |
| Repeat Shortages | A cashier or drawer hit your repeat limit this month | A private conversation, and a training check |
Cash Reconciliation Example (Filled Sample)
Want to see a cash reconciliation example before you enter your own numbers? Make your own copy of the filled sample in Google Sheets. It follows a fictional store, Cedar Street Supplies, through October 2026: 2 registers, 27 trading days, 42 shifts and 47,289.41 in cash sales. The screens on this page use the same sample data.
How to Read the Sample
Start with the Variance Summary. 36 of 42 shifts, or 86%, balanced or came within the $2 tolerance. The month ended 52.95 short. Now pick one day and follow the money.
200.00
+1,633.96
-22.49
-500.00
1,311.47
1,286.47
That's Register 2 on Saturday, October 17. The drawer came up 25.00 short, past the $20 investigate line, so it's marked Investigate and Under review. The deposit, 1,586.47, still reached the bank two days later.
Then look at Maria Santos. Her shortages, 6.50, 12.00, 4.75 and 8.40, would each pass unnoticed alone. Together they make 4 shortages beyond tolerance in one month, and the sheet flags her for repeat shortages. Finally, open the deposits: one banked a day late, one credited $20 short, and 4 still in transit on October 31, totaling 4,672.94.
Cash Reconciliation Formulas
Every formula is built into the Excel file. Here's what each one does, using the October 17 drawer as a worked cash reconciliation example.
Expected Cash
Expected Cash = Opening Float + Cash Sales − Cash Refunds − Paid Outs − Cash Drops + Cash Added
200.00 + 1,633.96 − 12.99 − 9.50 − 500.00 = 1,311.47. This is what the drawer should hold at close.
Over (Short)
Over (Short) = Counted Cash − Expected Cash
1,286.47 − 1,311.47 = -25.00. Negative means short. One rule, used everywhere, so nobody argues about the sign.
Deposit Prepared
Deposit = Counted Cash − Float Kept + Cash Drops to Safe
1,286.47 − 200.00 + 500.00 = 1,586.47. The drop goes to the bank with the rest, so it belongs in the deposit.
Bank Difference
Bank Difference = Amount Credited − Deposit Prepared
On October 23, Register 2 deposited 694.33 and the bank credited 674.33. Bank difference: -20.00, the sample's Bank Short.
How to Use the Cash Reconciliation Template?
Five minutes at close, two people, one cash reconciliation sheet. Here's the daily cash reconciliation routine.
1- Set Your Rules in Settings
Enter your standard float, tolerance, investigate amount, deposit limit in days and repeat limit, then list drawers and the people who count. Every dropdown reads from here.
⚡ Tip: Start with a $2 tolerance and a $20 investigate line. Adjust after a month, once you know your normal.
2- Count the Float In
Count the opening float with a second person before the first sale. Enter it on the Cash Count sheet and as the Opening Float on the log.
⚡ Tip: Use a fixed round float, such as 200.00, so any change to it stands out.
3- Log Every Drop and Paid Out
When cash leaves the drawer mid shift, write it down then and there. Mark Paid Out Receipts as Yes only if the receipt is in the drawer.
⚡ Tip: Staple paid out receipts to the printed daily sheet. Loose receipts vanish.
4- Run the Z Report First
At close, print the register report and copy the cash sales and refunds from it. Count after, not before, so the number you expect is fixed.
⚡ Tip: Never total sales from memory. The Z report is the source.
5- Count the Drawer Twice
Count notes and coins on the Cash Count sheet, the cash register reconciliation at its most basic, with a second counter, then enter the counted cash on the log. The status updates as you type.
⚡ Tip: If the status says Investigate, recount before anyone leaves the building.
6- Prepare and Track the Deposit
Keep the float, bag the rest, and write the slip number on the row. When the bank credits it, add the date and amount.
⚡ Tip: Have someone other than the cashier take the deposit to the bank.
7- Review the Month
Pick the month on Variance Summary and read the Flag column first. Then complete Month-End Proof and hand the deposits in transit to your bank reconciliation.
⚡ Tip: Look at repeat shortages by drawer too. A sticky drawer or a faulty scale can look like a person.
Common Cash Reconciliation Mistakes
Most shortages aren't theft. They're process. Here's where the process usually breaks.
✕ Counting before the Z report
Why it matters: The expected figure moves while you count, so the gap means nothing.
Fix: Print the register report first, then count.
✕ Forgetting the cash drop
Why it matters: The drawer reads $500 short and an honest cashier takes the blame.
Fix: Log every drop to the safe as it happens.
✕ Flipping the sign
Why it matters: Half the team writes shortages as positive numbers, and the monthly total cancels out.
Fix: Always counted minus expected. Negative means short.
✕ Ignoring small shortages
Why it matters: A few dollars a shift adds up, and a pattern stays invisible.
Fix: Record every gap, then review it by cashier each month.
✕ One person counts alone
Why it matters: There's no check on the count, and no protection for the cashier.
Fix: Two counters, two sets of initials, every time.
✕ Stopping at the drawer
Why it matters: The drawer balances, but the bag arrives at the bank $20 light.
Fix: Track the deposit until the bank credits it.
Why Cash Reconciliation Matters
Who notices a missing $20? Usually nobody, unless a form asks.
The ACFE studied 1,921 cases of occupational fraud for its Occupational Fraud 2024 report. 32% happened because of a lack of internal controls, and another 19% because existing controls were overridden. Tips uncovered 43% of cases, more than three times the next most common method.
So what? A cash reconciliation is an internal control in its simplest form. It won't catch everything, but it makes a quiet loss loud on the same day.
It Puts a Name and a Date on Every Gap
A 52.95 monthly shortage is a shrug. Four shortages from one cashier in one month is a conversation you can actually have.
It Protects Honest Cashiers
Dual counts and logged drops mean a missing $500 drop shows as a missing drop, not a missing person.
It Catches the Bank's Mistakes Too
Banks make errors, and counterfeit notes get caught at the counter. The sample's $20 Bank Short would vanish into a monthly total without a deposit row to check it against.
It Gives You Records You'll Need Anyway
Tax authorities in all four countries below ask you to keep the records behind your sales. A signed daily sheet with the Z report attached is exactly that.
Cash Reconciliation Spreadsheet vs Software
A spreadsheet is a great place to learn the routine. The weak spot is the gap between the till and the file: someone has to copy the numbers across.
| What you need | Cash reconciliation template | Enerpize |
|---|---|---|
| Cost | Free | Free trial, then a paid plan |
| Expected cash | Typed from the Z report | Worked out by the POS session |
| Counted cash | Typed after the count | Entered when you validate the session |
| Over and short | Calculated on the sheet | Shown as the difference at validation |
| Where the cash goes | Tracked by slip number | Delivered to the treasury or staff member you pick |
| Shortage and overage entries | Posted by hand | Posted to loss or profit accounts with auto adjustment on |
How Enerpize Handles Cash Reconciliation
What if the expected cash was already waiting for you when you closed the till? In Enerpize, the POS session keeps that number, so the reconciliation starts from the record instead of from a printout. The screens below use sample data.
POS Sessions: One Record per Drawer per Day
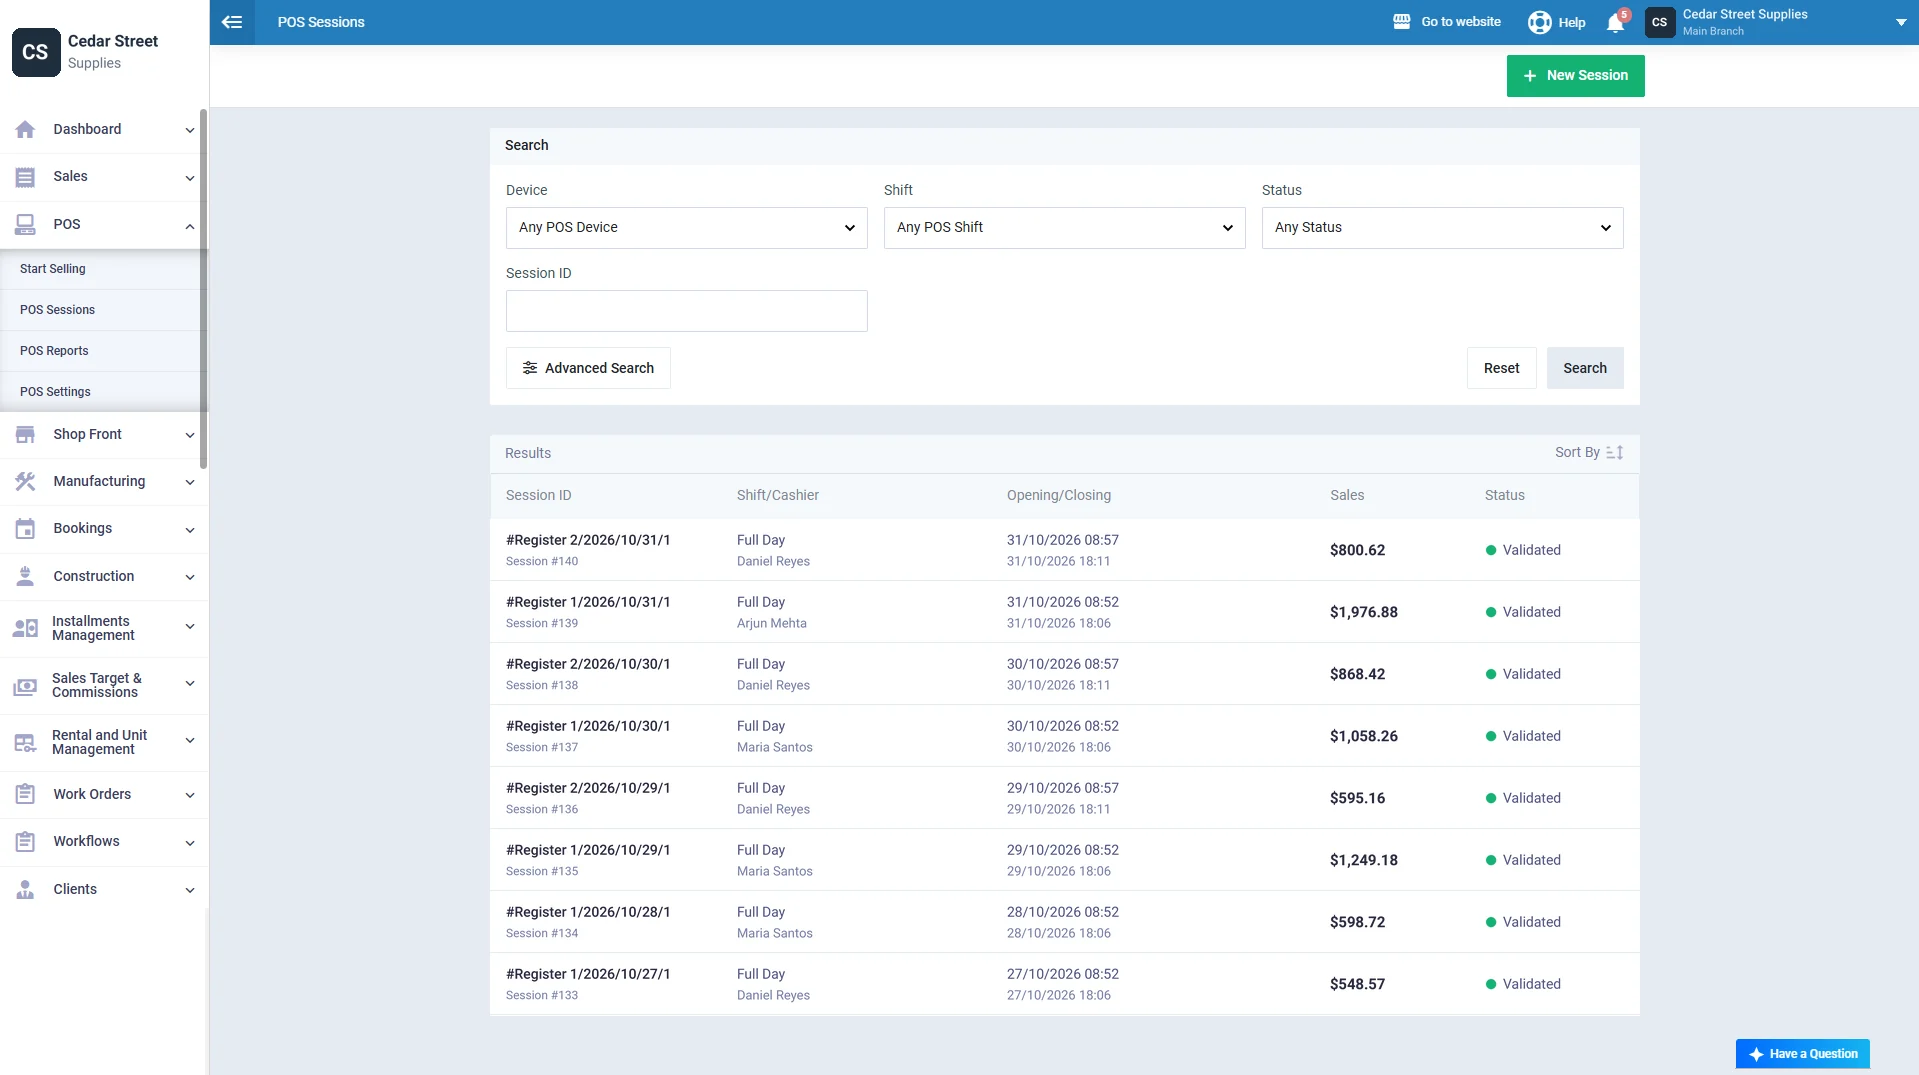
Each session shows its ID, shift and cashier, opening and closing times, sales and status. Search by device, shift or status to find the drawer you need. It's part of Enerpize's POS software, which also keeps selling in offline mode and syncs when the connection returns.
Opening a Session: Shift, Device, Cashier
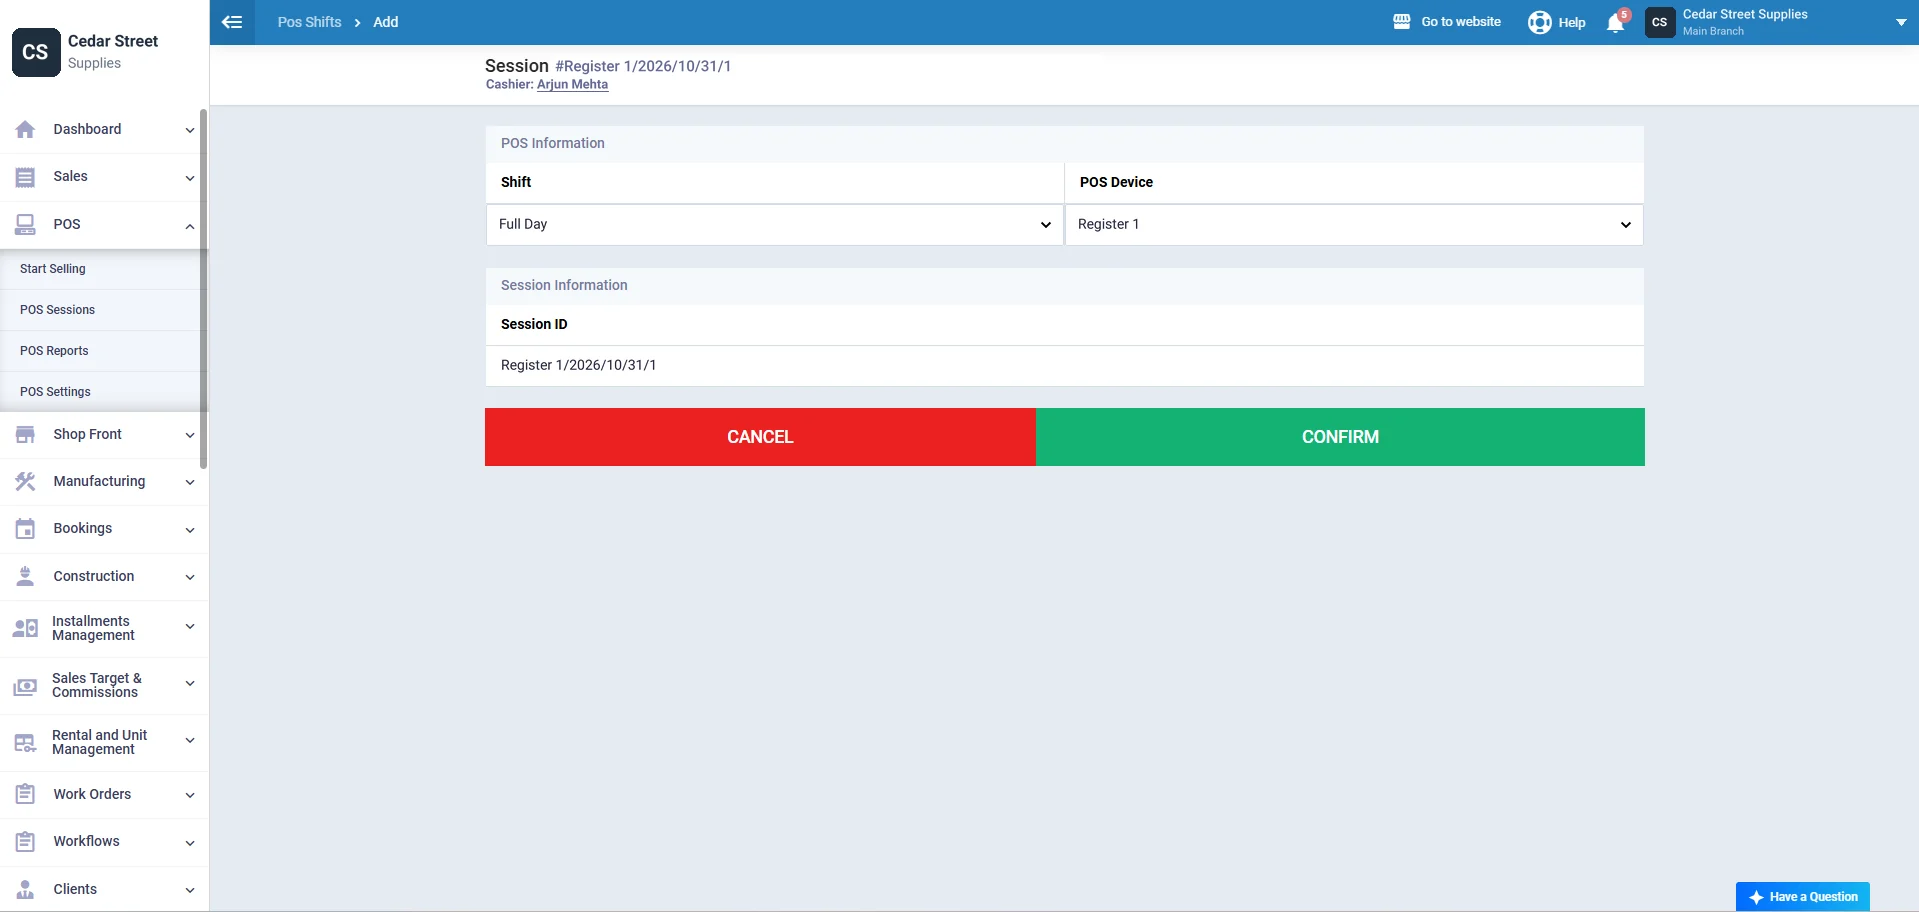
Starting a session ties the cash to a shift, a POS device and a cashier, with a session ID built from the device and date. That's the who and when your spreadsheet asks for, captured at the start.
The Sale Itself: Cash Recorded at the Counter
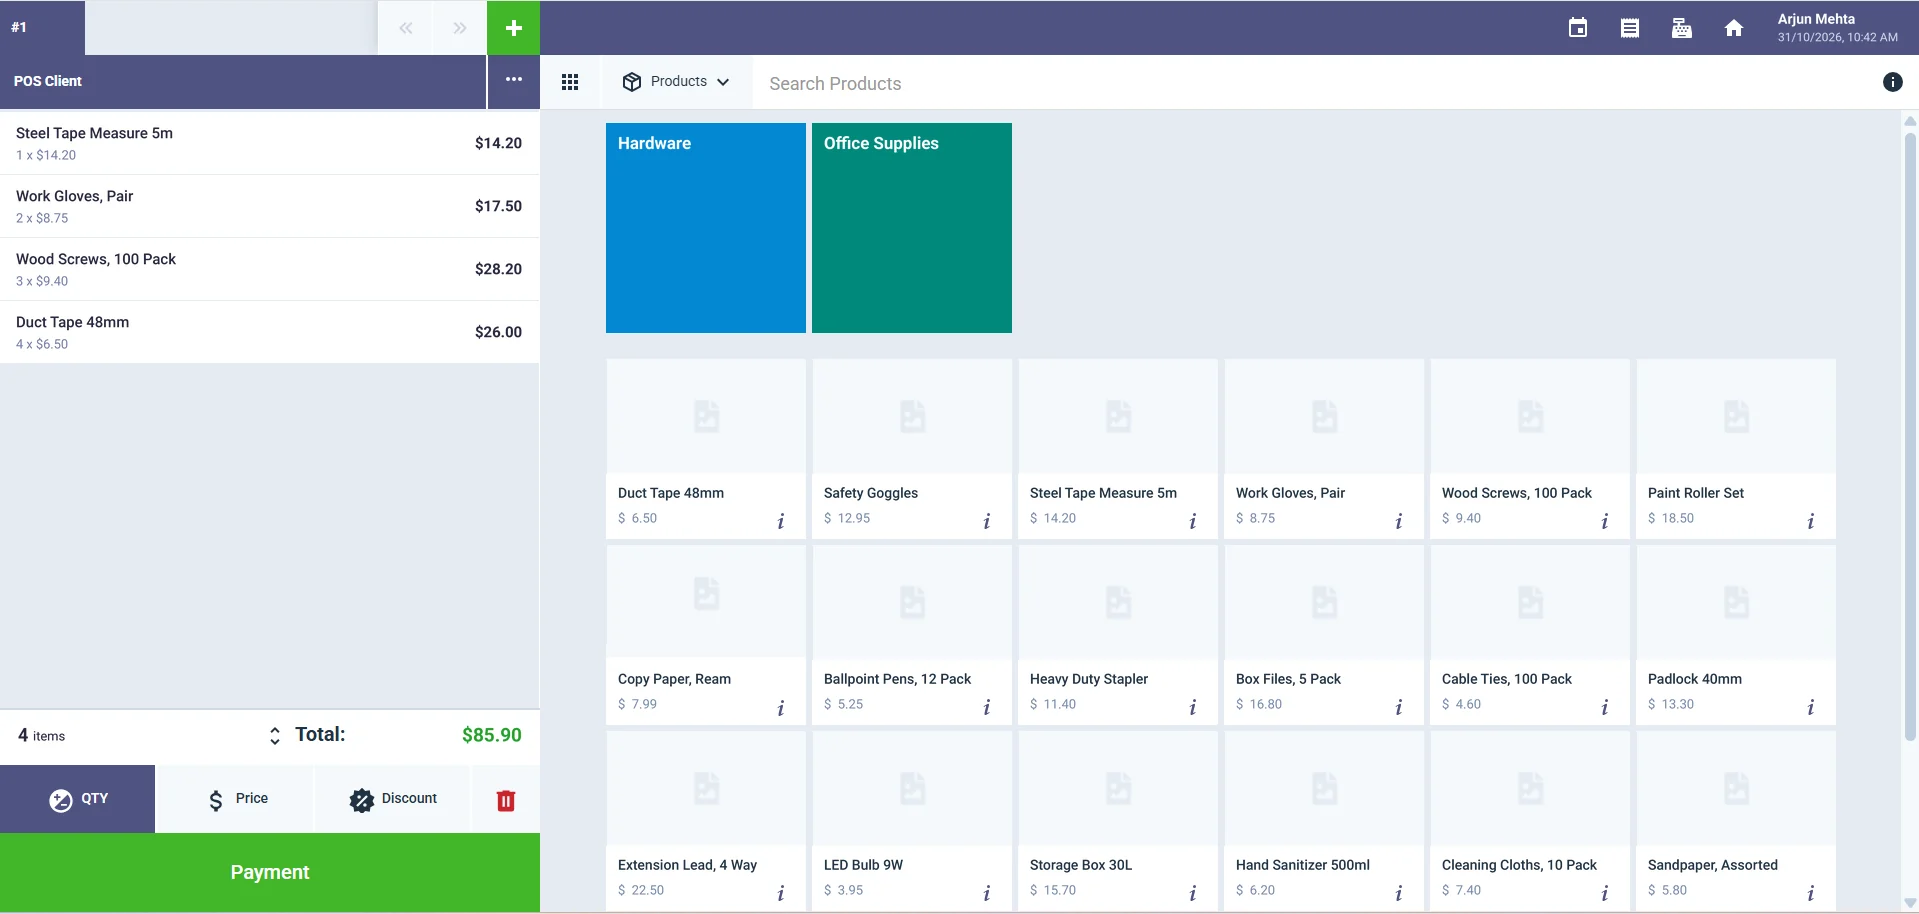
Every sale on the POS screen lands in the session, with payment methods recorded as you go. Cash in and cash out during the shift have their own actions, so a drop to the safe isn't a scribble on a sticky note.
Validation: Expected, Counted, Difference
When you close and validate a POS session, Enerpize shows the expected amount for each payment method. You enter what you counted, and it shows the difference as a shortage or overage. Choose who receives the cash, and the journal entries are created, with shortages posted to a loss account and overages to a profit account when auto adjustment is on.
POS Reports: Shifts, Sales and Profit
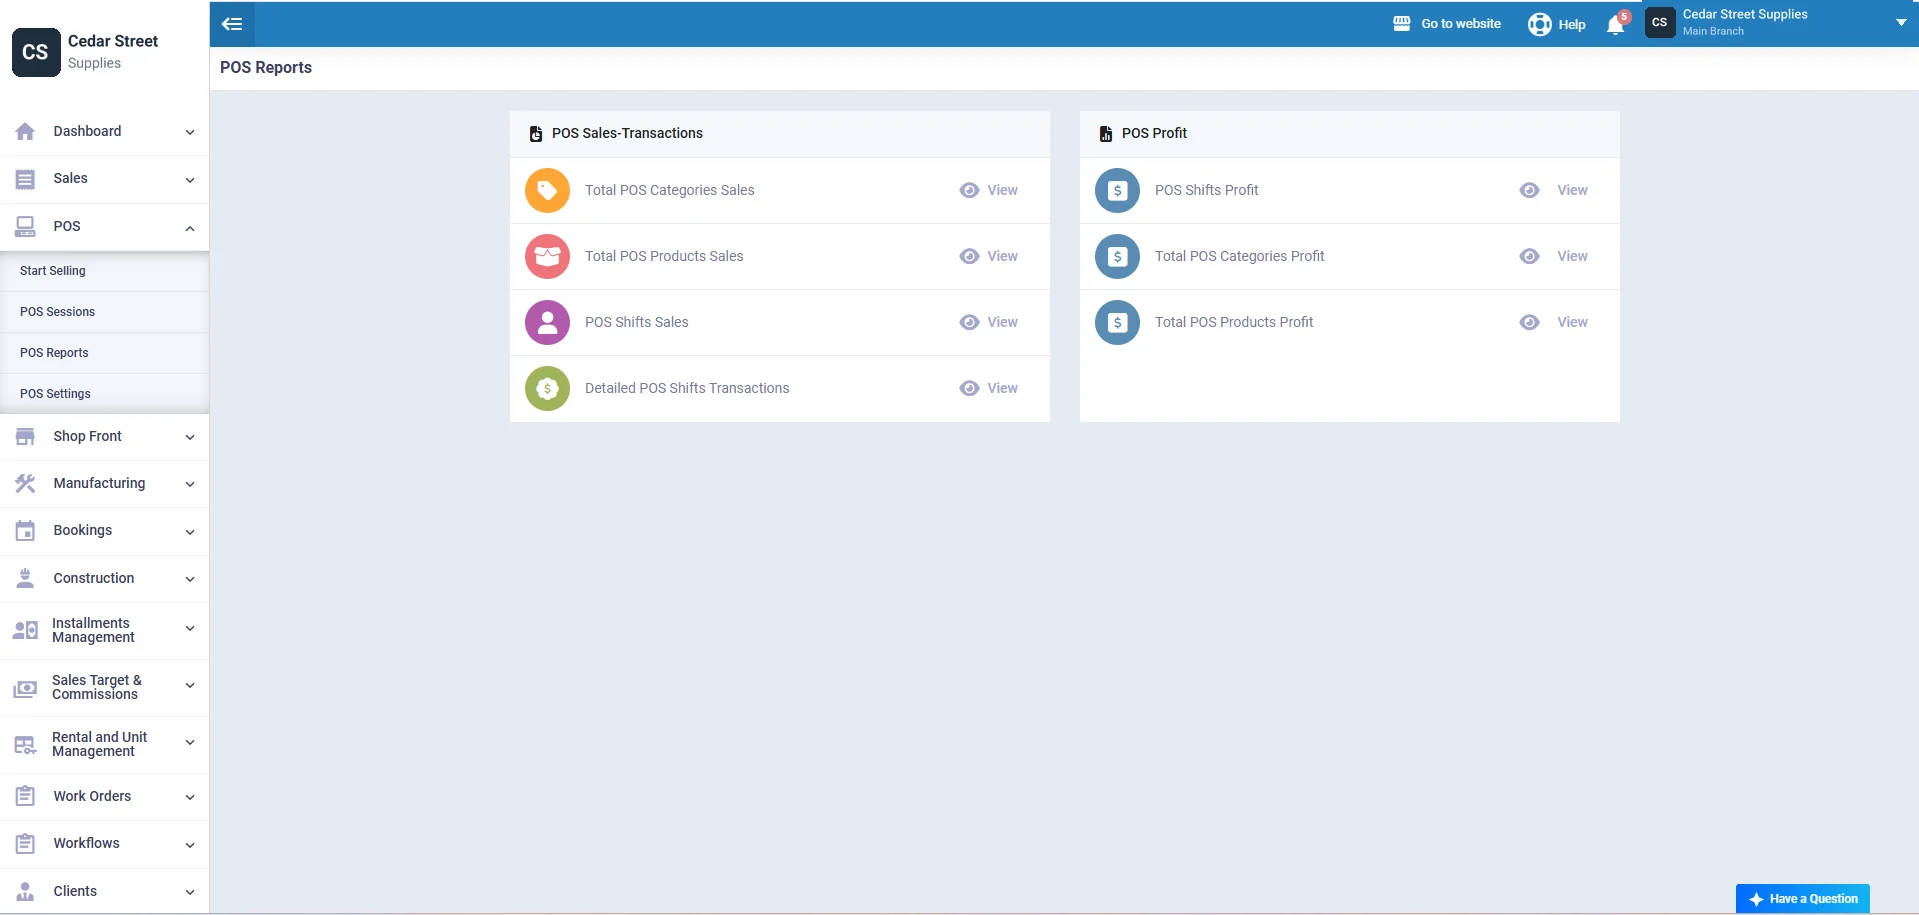
POS Reports gathers sales by category and product, POS shift sales, detailed shift transactions and profit by shift. That's where a repeat shortage on one shift starts to look like a pattern.
Treasuries: Where the Counted Cash Lands
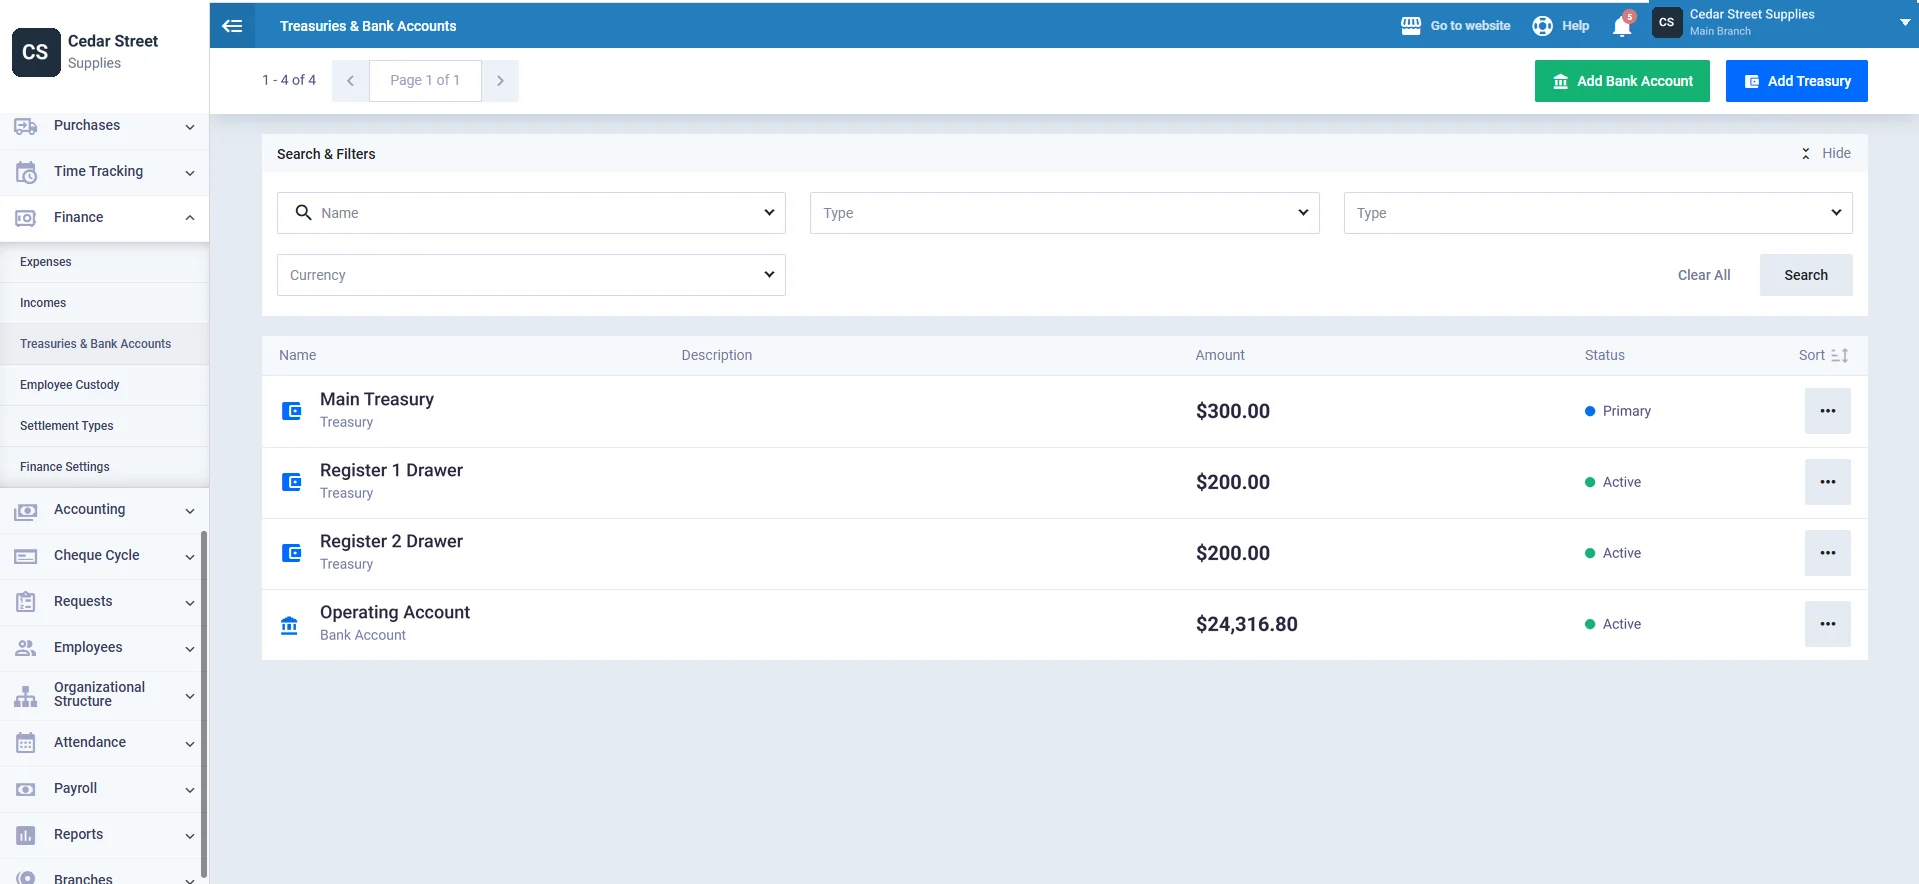
Treasuries and bank accounts sit side by side, each with its own balance. In the sample, the two drawer treasuries hold their 200.00 floats and the main treasury holds the 300.00 change fund, the same 700.00 as the month-end proof. Running a store? See how it fits retail store management.
Cash Reconciliation Template for the United States
In the US, the register tape you throw away tonight may be the record you need in an audit.
The IRS lists cash register tapes and deposit information for cash and credit sales among the supporting documents for gross receipts. Its guidance on how long to keep records sets the general period at 3 years, with longer periods in certain situations. Separately, a business that receives more than $10,000 in cash in one transaction or in related transactions must report it on Form 8300.
What to add:
- The Z report stapled to every printed daily sheet
- Deposit slip numbers on every row, so tapes tie to deposits
- A note in Reason whenever one customer pays more than $10,000 in cash
⚑ Practical note: Form 8300 is about one buyer's cash, not your daily takings. A busy day that totals $12,000 from many small sales isn't a Form 8300 event on its own. Ask your tax adviser if a single customer's payments get close.
Cash Reconciliation Template for the United Kingdom
A UK shop may call it "cashing up", but HMRC still wants the record behind it.
GOV.UK tells sole traders to keep records for at least 5 years after the 31 January submission deadline of the relevant tax year. And from 6 April 2026, Making Tax Digital for Income Tax applies if your total annual income from self-employment and property is over £50,000, which means digital records and quarterly updates through compatible software.
What to add:
- The till Z reading on each daily sheet
- £ notes and coins in Settings, from £50 to 1p
- A retention date on each month's file
⚑ Practical note: A spreadsheet can hold your daily cash records, but Making Tax Digital submissions need compatible software. Check with your accountant how your records will reach HMRC. For a full day of receipts and payments, the daily cash report covers the cash up in detail.
Cash Reconciliation Template for Canada
Canadian retailers have a longer memory to keep than their US neighbors.
The CRA says records must be kept for a period of six years from the end of the last tax year they relate to. A cash sheet from December 2026 belongs to the 2026 tax year, so it stays until the end of 2032.
What to add:
- C$ notes and coins in Settings, including $2 coins and no pennies
- The tax year on each monthly file name
- A scanned copy of each signed sheet and Z report
⚑ Practical note: Canada stopped distributing pennies in 2013, so cash sales are rounded to the nearest 5 cents. Small overs and shorts from rounding are normal, which is exactly what your tolerance setting is for.
Cash Reconciliation Template for India
In India, the size of one cash receipt can matter as much as the day's total.
The Income-tax Act, 2025 came into force on 1 April 2026, replacing the 1961 Act. It carries forward the rule known as section 269ST: no person may receive ₹2 lakh or more in cash from one person in a day, in a single transaction, or for transactions relating to one event or occasion. TaxGuru's summary of the new Act also covers the rule that cash expenses above ₹10,000 to one person in a day are generally not deductible.
What to add:
- ₹ notes and coins in Settings
- A note in Reason for any single customer paying ₹2 lakh or more in cash
- Paid outs above ₹10,000 moved to bank or UPI payments
⚑ Practical note: The ₹2 lakh limit is about what you receive, not what you bank. A jeweler or electronics store can break it with one sale. Check the current section numbers under the 2025 Act with your chartered accountant.
Who Can Use the Cash Reconciliation Template?
Retail Stores
Two registers, a weekend rush and a cash drop at 3 p.m. That's the sample, and most small shops. A cash register reconciliation by drawer shows which register went short, not just which day.
Restaurants and Cafes
Several servers, one drawer, cash tips. A cash drawer reconciliation per shift stops a busy dinner from hiding a short lunch.
Pharmacies and Clinics
Co-pays and walk-in sales arrive in cash all day. A daily cash reconciliation sheet keeps the front desk accurate without slowing the queue.
Schools, Clubs and Events
Ticket booths and fundraisers run for a day and then vanish. The printable cash drawer reconciliation form gives volunteers one page, two counters and a signature line.
Bookkeepers and Accountants
Send it to a client who still deposits cash. The deposit rows and the month-end proof make their bank reconciliation a matching job.
Cash Reconciliation Glossary
| Term | What it means |
|---|---|
| Opening float | The cash counted into a drawer before the first sale, used to give change. |
| Z report | The register report printed at close, with total sales by payment method. |
| Paid out | Cash taken from the drawer for a business expense during the shift. |
| Cash drop | Cash moved from the drawer to the safe during the shift. |
| Over (short) | Counted cash minus expected cash. Negative means short. |
| Tolerance | The difference you accept without an investigation. |
| Deposit in transit | A deposit made but not yet credited by the bank. |
| Treasury | A cash location in your accounts, such as a drawer or a safe. |
Key Takeaways
- A cash reconciliation template compares expected cash with counted cash for each drawer and shift, then follows the deposit to the bank.
- Expected cash is the float plus cash sales, minus refunds, paid outs and cash drops. In the sample, 200.00 + 1,633.96 − 22.49 − 500.00 = 1,311.47.
- Use one sign rule: counted minus expected. A negative number, like -25.00, means short.
- Set a tolerance and an investigate line. With $2 and $20, 36 of the sample's 42 shifts, or 86%, balanced or came within tolerance.
- Read shortages by cashier, not just by month. A 52.95 monthly shortage hid 4 shortages from one cashier.
- Track every deposit. The sample had one late deposit, one $20 short credit and 4,672.94 in transit at month end.
- Keep the records behind your cash: 3 years generally in the US, 5 years after the filing deadline for UK sole traders and 6 years in Canada.
- In India, receiving ₹2 lakh or more in cash from one person in a day breaks the cash receipt rule.
Frequently Asked Questions
How do you do a cash reconciliation?
Count the opening float, record cash sales, refunds, paid outs and drops during the shift, then work out expected cash. Count the drawer with a second person, subtract expected cash from counted cash, and record the difference with a reason. Finally, track the deposit until the bank credits it.
What is the format for a cash reconciliation?
A cash reconciliation format has a header with the date, drawer and cashier, an expected cash section, a note and coin count, the over or short amount with a reason, the deposit and signatures from two counters. Our Word and PDF cash reconciliation form puts all of it on one page.
What is an example of a cash reconciliation?
A drawer opens with a 200.00 float, takes 1,633.96 in cash sales, pays 22.49 in refunds and paid outs, and drops 500.00 to the safe. Expected cash is 1,311.47. The count is 1,286.47, so the drawer is 25.00 short.
What is the difference between cash reconciliation and bank reconciliation?
A cash reconciliation compares the physical cash in a drawer or safe with your records, usually every shift. A bank reconciliation compares your cash book with the bank statement, usually monthly. The deposit links them, since every deposit you prepare should appear on the statement.
What is an acceptable cash variance?
Pick a small tolerance, such as $2 per drawer, and investigate anything past a higher line, such as $20. The right numbers depend on your volume. Whatever you choose, record every variance, because a small repeated shortage is often the warning sign.
How often should cash be reconciled, and who should count it?
Do a daily cash reconciliation at the end of every shift, and a full check at month end. Two people should count: the cashier and a manager or second counter. Someone other than the cashier should take the deposit to the bank.
What should you do if the cash drawer is short?
Recount first with a second person. Then check the Z report, paid out receipts, refunds and cash drops for anything missed. If the gap remains, record it with a reason, sign the sheet, and review the cashier's and drawer's history at month end.
How long should you keep cash reconciliation records?
As long as your tax authority asks. Generally 3 years in the US, at least 5 years after the 31 January deadline for UK sole traders, and 6 years from the end of the tax year in Canada. Keep the Z reports and deposit slips with them.
About the Author
Omar El Bahr is a Senior Digital Growth Specialist at Enerpize, where he leads SEO, content strategy, and organic growth across international markets. He is a Forbes Communications Council contributor and has written for Entrepreneur on business communication and digital strategy.
Disclaimer
The template and the information on this page are general guidance, not accounting, tax or legal advice. Record keeping periods and cash rules differ by country and change over time, so confirm what applies to your business with a qualified adviser. The cash reconciliation template is not a statutory form.