Posted on 19 December 2024
Free General Ledger Template Download for Excel, Google Sheets, Word and PDF
- Available to download in Excel, Google Sheets, Word and PDF
- Enter each transaction once, and every account ledger builds itself
- Running balances in the Dr or Cr column, never a minus sign
- Trial balance that flags unbalanced vouchers and unknown account codes
A general ledger template is a ready-made spreadsheet that groups every journal entry by account and keeps a running balance for each one, from the balance brought forward to the closing balance. It is the book you prepare a trial balance from, and the record your balance sheet and income statement rest on.


Last updated: November 8, 2026
What it is
A general ledger template that sorts every journal entry by account and keeps a running balance for each one.
When you need it
When you want to know what is really in the bank, what you owe a supplier, or why the books won't balance.
What's inside
A chart of accounts, a journal, a ledger for any account you pick, and a trial balance with error checks.
Formats
Excel, Google Sheets, Word and PDF. The Word and PDF files are a printable account page.
Want to see it filled in first?
Make your own copy of the filled sample in Google Sheets.
What Is a General Ledger Template?
Your bank says one number. Your spreadsheet says another. Somewhere in between, 150 dollars went missing.
Where do you even start looking?
You start in the ledger.
A general ledger template is a ready-made spreadsheet that groups every journal entry by account and keeps a running balance for each one, from the balance brought forward to the closing balance. It is the book you prepare a trial balance from, and the record your balance sheet and income statement rest on.
It goes by several names. An accounting ledger template. A ledger sheet. A GL template. In India and Pakistan, a general ledger format with a J.F. column. Same job every time: show every account's history and where it stands today.
invoice, receipt, bill
one entry, two sides
sorted by account
debits = credits
profit and position
What it isn't matters just as much. It isn't the journal, where entries land in date order. It isn't the trial balance, which only lists closing balances. And it isn't a customer statement, although the same ledger can print one.
General Ledger vs Journal vs Trial Balance vs Ledger Statement
Four documents, one set of numbers. Each one answers a different question.
| Document | Question it answers | Order | Who reads it |
|---|---|---|---|
| Journal | What happened, and when? | By date | The bookkeeper |
| General ledger | What is each account's balance, and how did it get there? | By account, then date | Owner and accountant |
| Trial balance | Do total debits equal total credits? | One line per account | Accountant and auditor |
| Ledger statement | What does this one customer or supplier owe? | One account, one period | The customer or supplier |
The journal tells the story, the ledger keeps the score, and the trial balance checks the math.
New to the idea itself? Our guide to what a general ledger is covers the theory. This page is about keeping one.
Which Ledger Template Fits Your Situation?
Start with the question you're trying to answer, then pick the file.
| If your situation is... | Use this | Where to find it |
|---|---|---|
| You want every account in one file, with a trial balance | General ledger template in Excel | Excel or Google Sheets |
| You post by hand and want a page per account | Printable account page | Word and PDF files |
| You track one bank account and nothing else | Bank ledger | The bank ledger template |
| A customer wants to see what they owe you | Ledger statement for one account | General Ledger sheet, or a statement of account |
| Your ledger balance doesn't match the bank | Reconciliation | The general ledger reconciliation template |
| You only need to record entries, not balances | Journal | The journal entry template |
What Does the General Ledger Template Contain?
Every general ledger format, on paper or in Excel, comes down to the same handful of columns. Here's what each one does.
| Field | What goes in it | Why it matters |
|---|---|---|
| Account code and name | 1000 Cash at Bank, 2000 Accounts Payable | Keeps one account from blurring into another |
| Account type | Asset, liability, equity, revenue or expense | Decides the side a balance normally sits on |
| Date | When the transaction happened | Puts the history in order |
| Post reference | The voucher number, such as JV-007 | Traces every line back to its journal entry |
| Particulars | A short description, plus the party | Tells you what the money was for |
| Debit and credit | One amount, on one side | Moves the balance up or down |
| Running balance | The balance after each line, in Dr or Cr | Shows the position on any date |
| Balance b/f and c/f | Brought forward and carried forward | Links this period to the last one |
The column people get wrong is the running balance. Write a loan as minus 9,000 and you've already lost half your readers. A liability normally carries a credit balance, so it belongs in the Cr column as 9,000.00.
What the Enerpize General Ledger Template Includes
Our old template was a single sheet: business details, date, description, post reference, debit, credit and two totals. It worked for one account. It didn't help with the second.
So we rebuilt it around how bookkeepers actually work. You type each transaction once in a journal, and the ledgers, the statement and the trial balance follow. It runs on formulas with no macros, and only the yellow cells are yours to type in.
One Entry, Every Ledger
Enter a sale on the Journal sheet: debit Cash at Bank, credit Sales Revenue, credit Sales Tax Payable. All three accounts update. There's room for 1,000 journal lines and 100 accounts, which covers a year of books for many small businesses.
Balances That Know Their Side
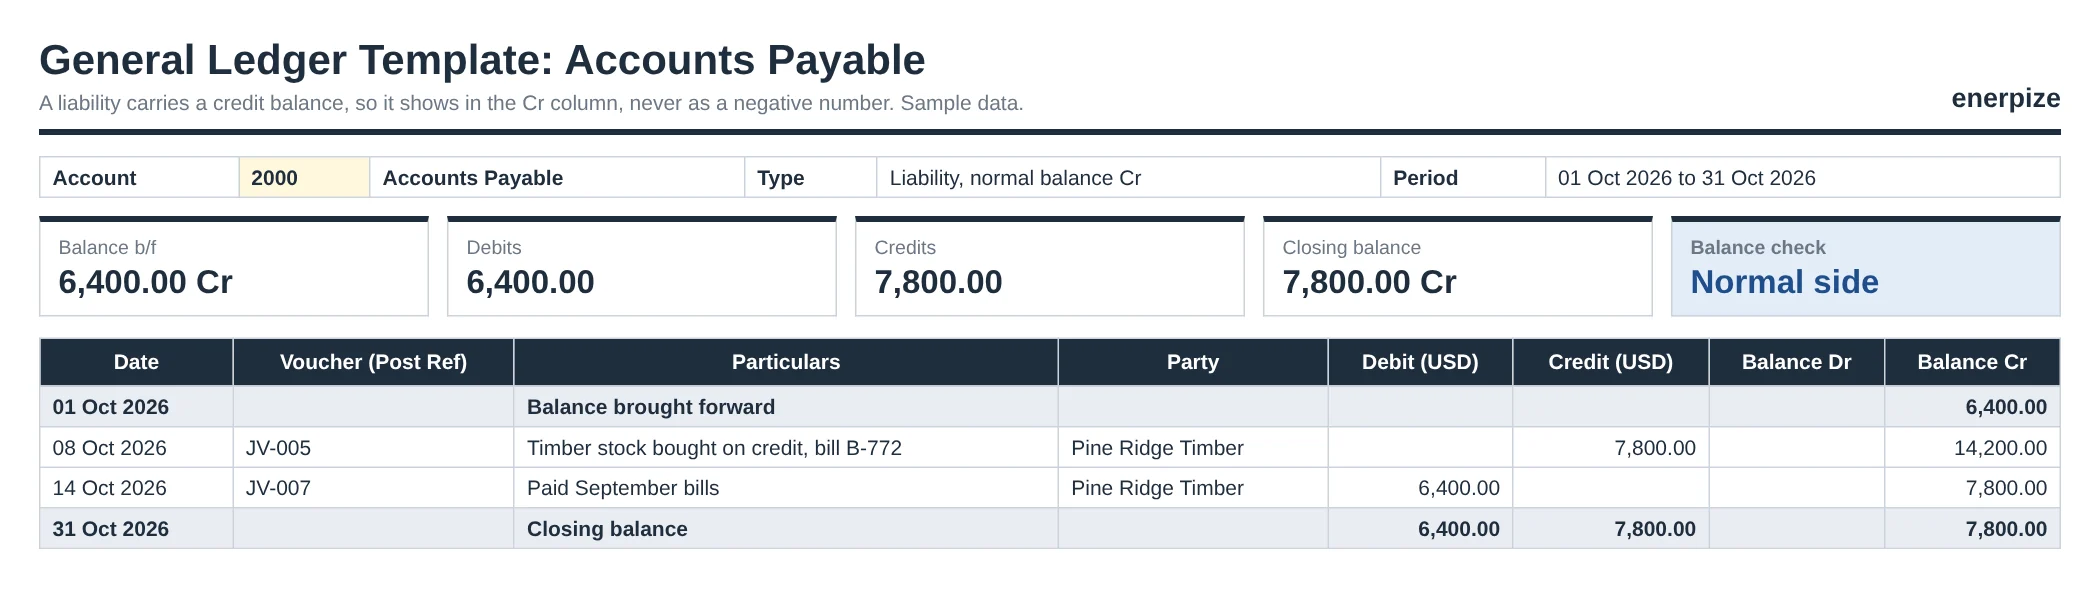
Most spreadsheets use one formula for every account, so a supplier you owe 7,800 shows up as minus 7,800. Ours reads the account type and puts the balance where an accountant expects it: 7,800.00 in the Cr column. If a balance lands on the wrong side, like an overdrawn bank account, the ledger says so.
A Statement on Demand
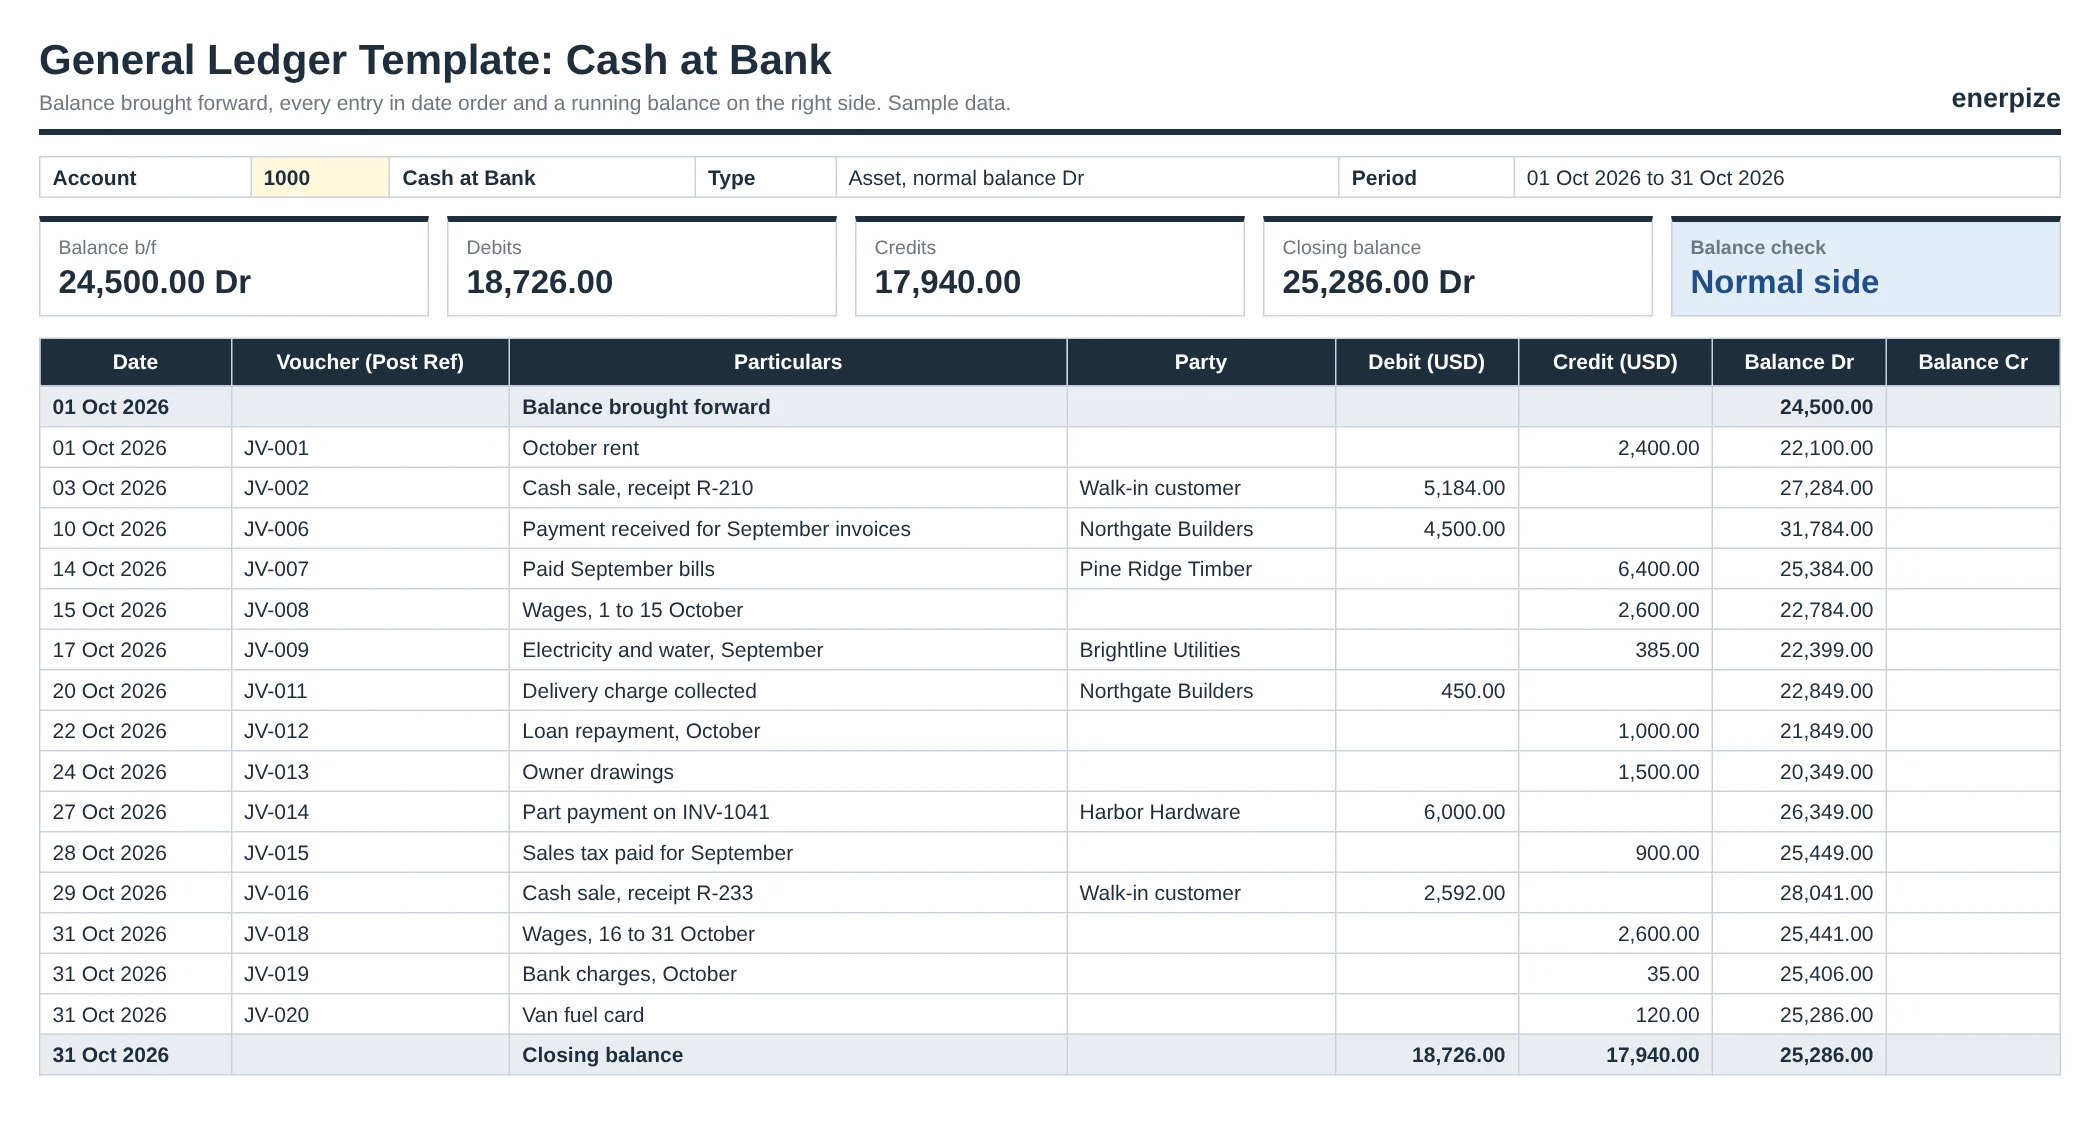
Pick an account and, if you like, two dates. The General Ledger sheet works out the balance brought forward, lists every entry in date order and closes with the period totals. Print it, and that's your ledger statement. Give each customer their own code and it doubles as a party ledger.
A Smoke Alarm for Your Books
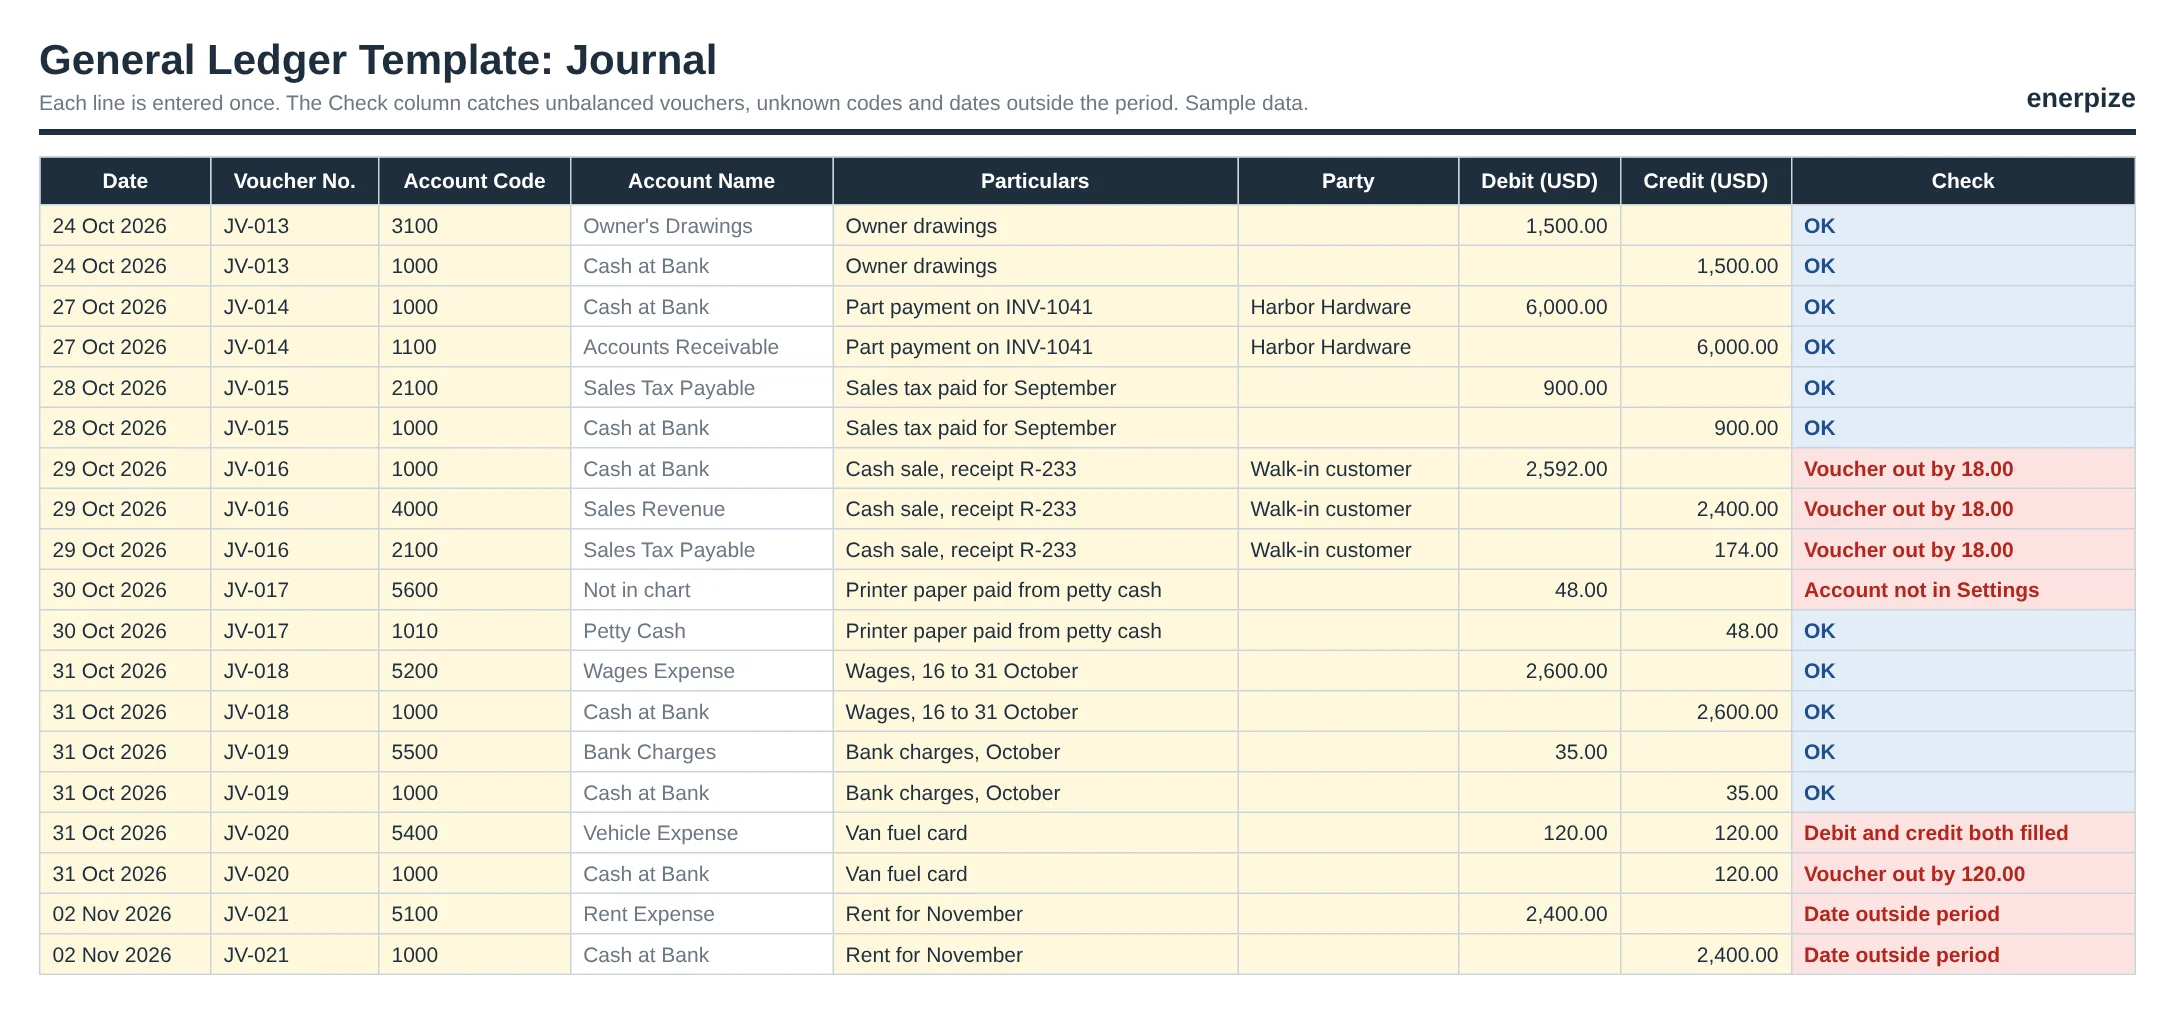
Every journal line gets a check. Voucher out of balance. Account not in Settings. Debit and credit both filled. Date outside the period. The trial balance then tells you the total gap and how much never posted, so you know the size of the problem before you go looking for it.
A Chart That Sets the Rules
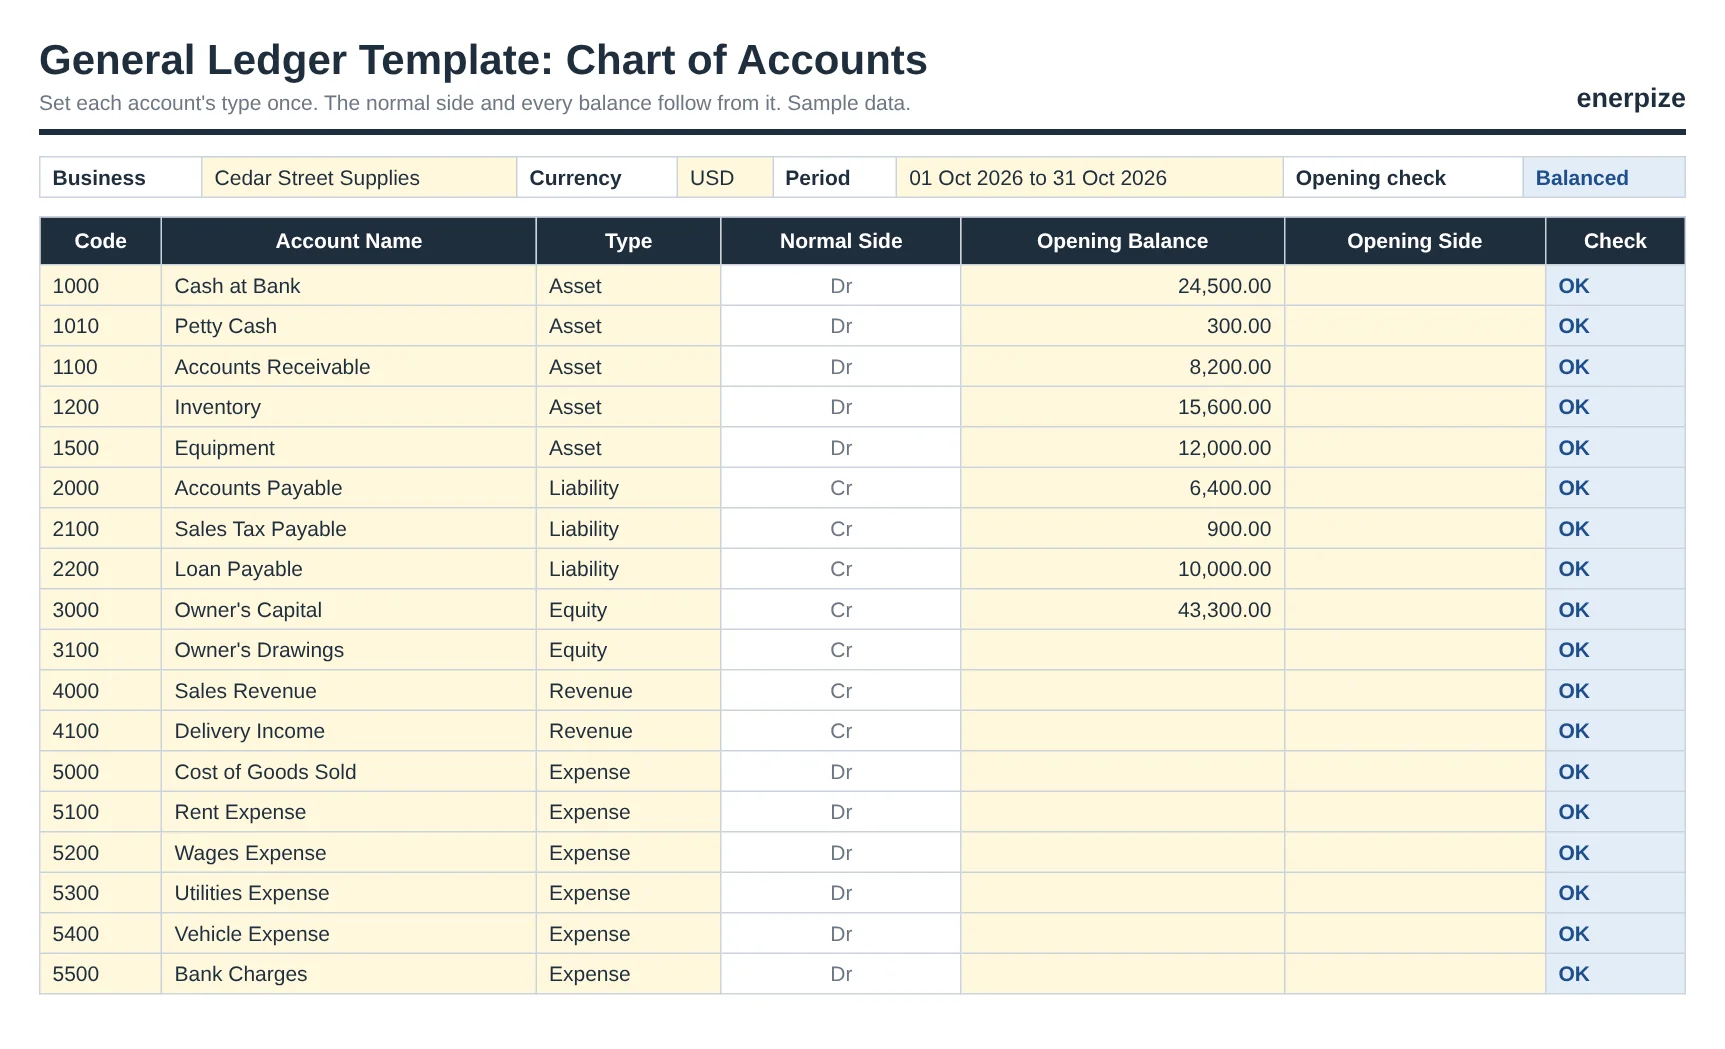
Your chart of accounts lives on Settings: a code, a name, a type and an opening balance for each account. Set the type once and everything else follows from it. An opening check tells you whether your opening debits and credits agree before you post a single line.
General Ledger Format: T-Account vs Columnar Ledger
Ask a teacher to draw a general ledger format and you'll get a T. Ask a bookkeeper and you'll get columns. Both are correct. They just answer different questions.
T-account format
Debits on the left, credits on the right. Each side has its own date, particulars, journal folio and amount. You total both sides at the end of the period and carry the difference down. It's the ledger sheet most students learn on, and Indian textbooks add a J.F. column to each side.
Columnar format
One line per entry, with debit and credit side by side and a running balance after every line. You can see the position on any date without totaling anything. That's the general ledger format our template, and most accounting software, uses.
The same three entries from our sample, drawn as a T-account for Cash at Bank:
| Dr | Amount | Cr | Amount |
|---|---|---|---|
| Balance b/f | 24,500 | Rent | 2,400 |
| Cash sale | 5,184 | Paid supplier | 6,400 |
| Received | 4,500 | Balance c/f | 25,384 |
The columnar version of the same lines reads 24,500.00, then 22,100.00, 27,284.00 and 31,784.00 down the balance column, before the payment to the supplier takes it to 25,384.00. Same numbers, no adding up at the end.
General Ledger Example: A Filled Sample
Want to see it working before you type a thing? Make your own copy of the filled sample in Google Sheets. This general ledger example follows a fictional business, Cedar Street Supplies, through October 2026: 18 accounts, 21 vouchers and 45 journal lines, in US dollars. Every screen on this page uses the same sample data.
How to Read the Sample
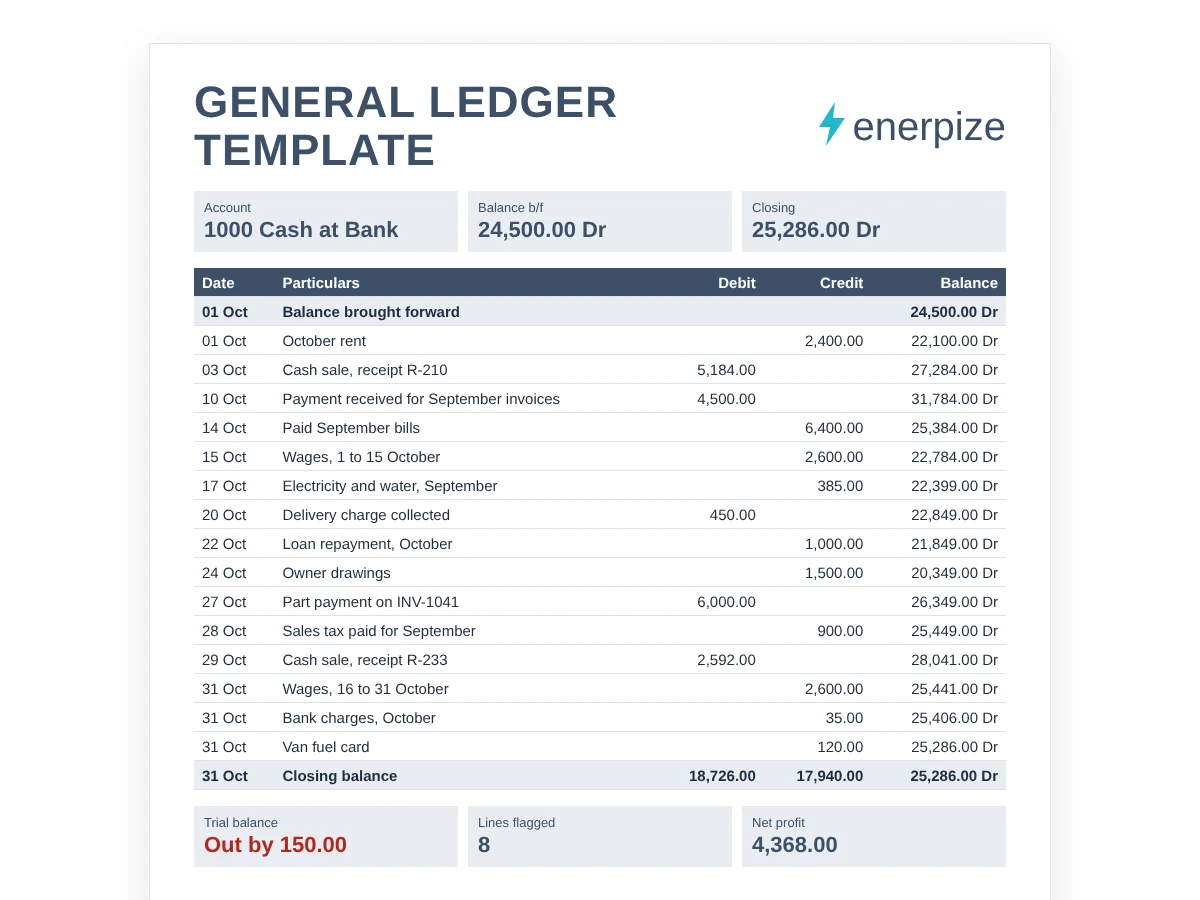
Open the General Ledger sheet, already set to account 1000, Cash at Bank.
24,500.00 Dr
18,726.00
17,940.00
25,286.00 Dr
Fifteen entries moved the bank account this month, and it closed 786.00 higher than it opened. So far, so normal.
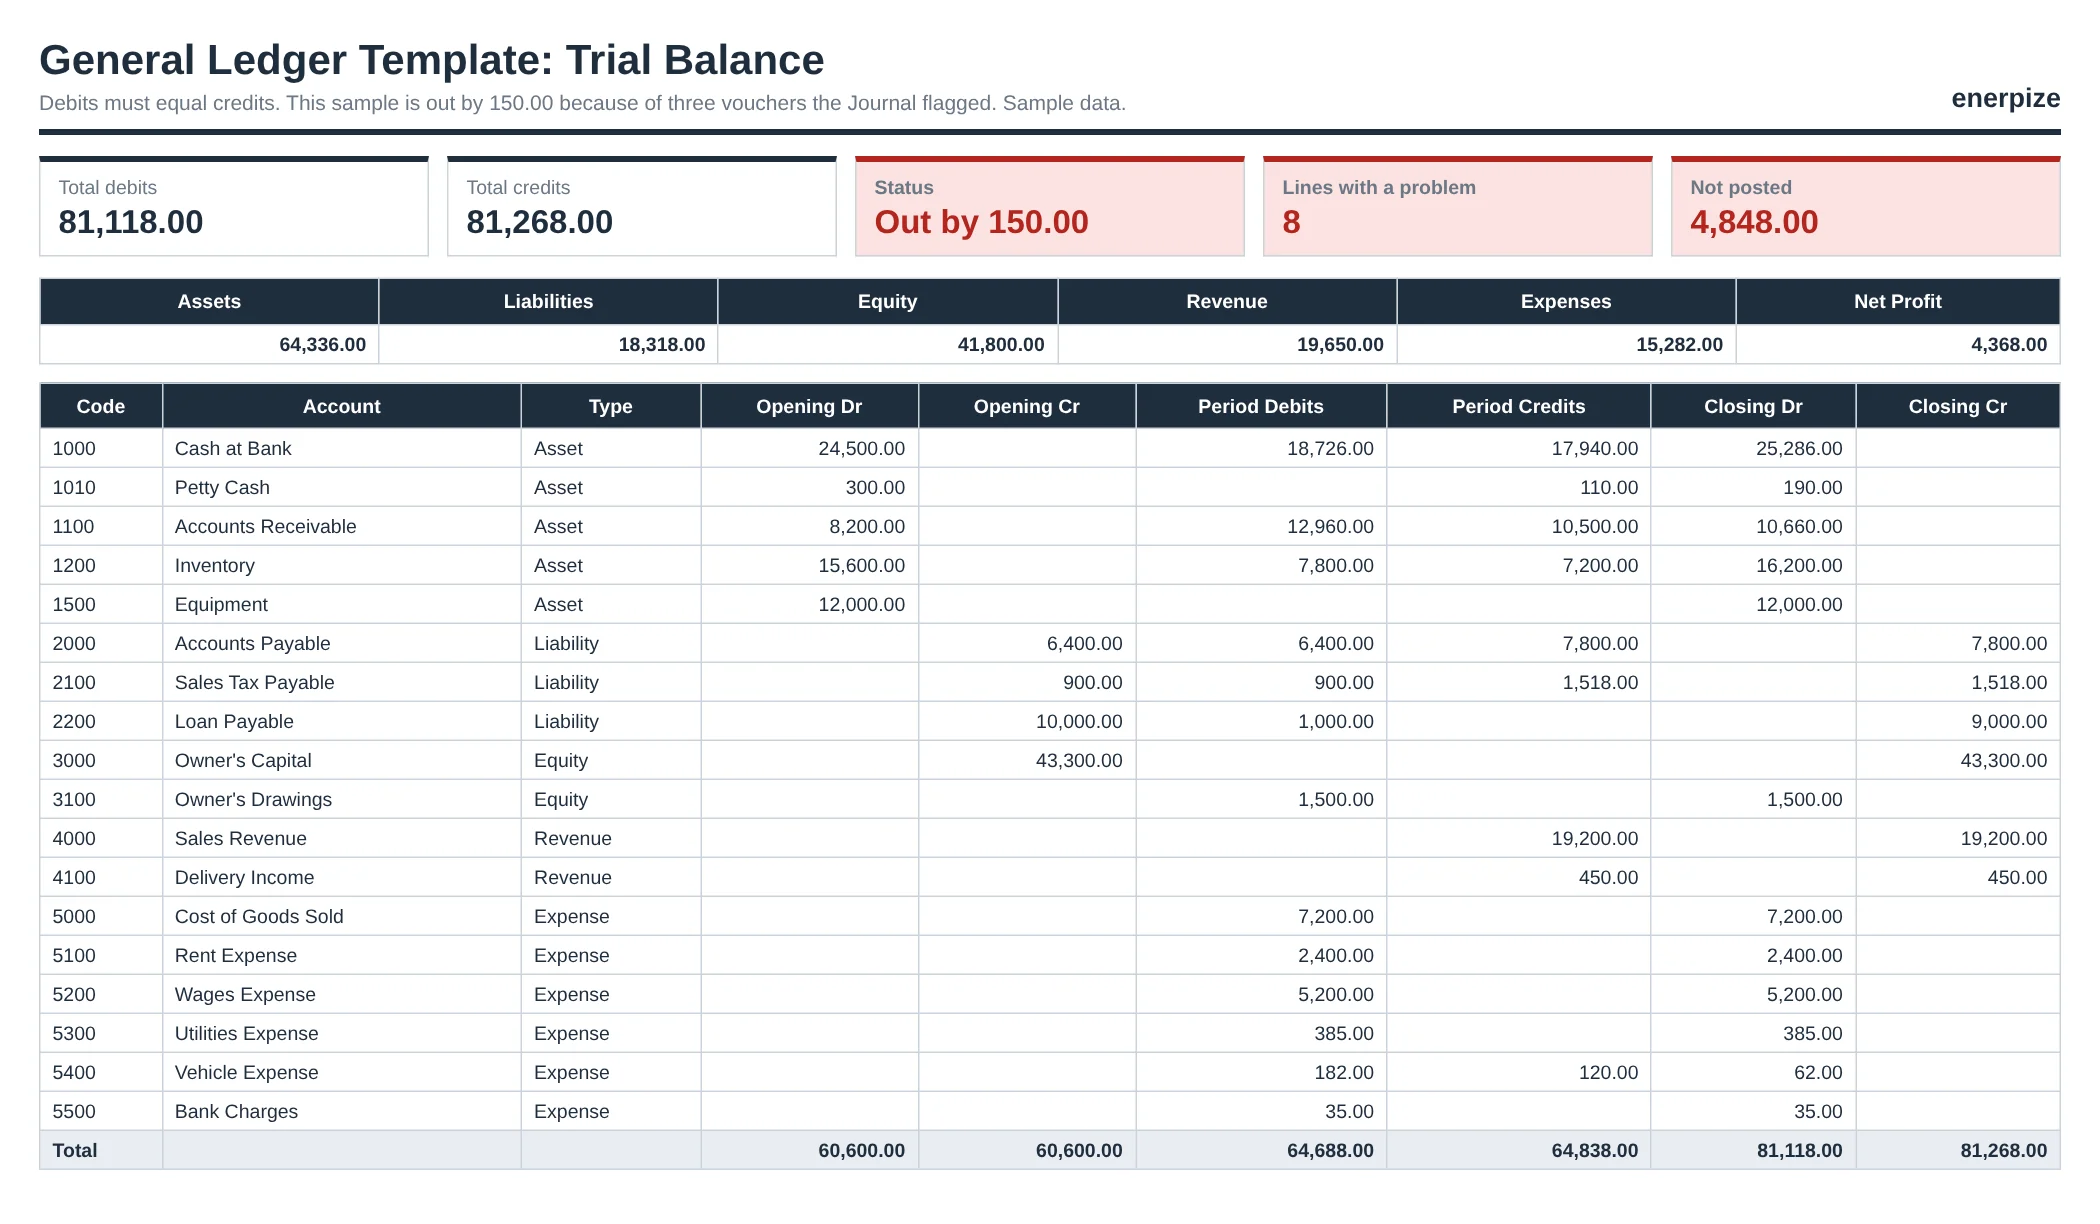
Now open the Trial Balance. Total debits 81,118.00, total credits 81,268.00. Out by 150.00.
Where did it go? The Journal answers in red. Voucher JV-016 is out by 18.00 because the sales tax was typed as 174.00 instead of 192.00. JV-017 uses account 5600, which isn't in the chart, so its 48.00 debit never posted. JV-020 has 120.00 in both columns on the same row. Add them up: 18 minus 48 minus 120 is minus 150.
One more line, JV-021, is dated 2 November. It's outside the period, so it's flagged and sits in the 4,848.00 that didn't post. That's the point of the sample. A ledger that never shows you a mistake isn't checking anything.
General Ledger Formulas
Every formula is already in the file. If you're building a general ledger template in Excel yourself, these four do the heavy lifting. Each worked number comes from the general ledger example in our sample.
Running Balance
Balance = Previous Balance + Debit − Credit
Cash at Bank opens at 24,500.00. October rent is a 2,400.00 credit, so the next balance is 22,100.00.
Which Column It Goes In
If Balance > 0, show it under Balance Dr. If Balance < 0, show its value under Balance Cr.
Accounts Payable opens at 6,400.00 Cr. A 7,800.00 bill takes it to 14,200.00 Cr, and a 6,400.00 payment brings it back to 7,800.00 Cr. No minus signs anywhere.
Balance Brought Forward for Any Date
=Opening + SUMIFS(Debits, Account, Code, Date, "<"&From) − SUMIFS(Credits, Account, Code, Date, "<"&From)
Pick 15 October as the start date and Cash at Bank brings forward 25,384.00, the balance after the 14 October payment.
Trial Balance Difference
Difference = Total Closing Debits − Total Closing Credits
81,118.00 minus 81,268.00 gives minus 150.00. Anything other than zero means at least one voucher needs fixing.
How to Use the General Ledger Template
Set up the general ledger template in Excel or Google Sheets once, then it's a few minutes a day. Here's the routine.
1- Set Up Your Chart of Accounts
Enter your business name, currency and period on Settings. Then list your accounts with a code, a name, a type and the opening balance on the first day of the period.
⚡ Tip: Number by type: 1000s for assets, 2000s for liabilities, 3000s for equity, 4000s for revenue, 5000s for expenses. New accounts then slot in without a rethink.
2- Check Your Opening Balances
Look at the opening check before posting anything. Opening debits must equal opening credits, or every balance after that is built on sand.
⚡ Tip: Copy the closing balances from last period's trial balance. They should agree to the cent.
3- Record Each Transaction in the Journal
Add one row per account line, with the date, voucher number, account code, particulars and the amount in Debit or Credit. A sale with tax is three rows under one voucher.
⚡ Tip: Same voucher number on every line of the entry. That's how the sheet knows which lines have to balance.
4- Fix Anything the Check Column Flags
Clear every red message before you trust a balance. Each message names the problem, so the fix is usually one cell.
⚡ Tip: Sort or filter the Check column to see only the lines that aren't OK.
5- Review Each Account in the Ledger
Pick an account on the General Ledger sheet and read it top to bottom. Does the closing balance sit on its usual side? Does the bank figure match your statement?
⚡ Tip: Run the bank account weekly. Small gaps are easy to find when the week is still fresh.
6- Close the Period With the Trial Balance
When the status says Balanced and nothing is waiting to post, use the closing balances to prepare your balance sheet and income statement.
⚡ Tip: Carry each closing balance into next period's Settings as its opening balance, on the same side.
Common General Ledger Mistakes
Ledger mistakes rarely shout. They sit quietly until year end, then cost you a weekend.
✕ Posting one side of an entry
Why it matters: The trial balance goes out, and you can't tell which account is wrong.
Fix: Give every entry a voucher number and check that its lines balance.
✕ Showing balances as negatives
Why it matters: A credit balance reads like an error, and nobody trusts the report.
Fix: Show balances in Dr and Cr columns based on the account type.
✕ Inventing accounts as you go
Why it matters: "Office stuff" and "Office supplies" split one cost in two.
Fix: Add accounts to the chart first, then post to them by code.
✕ Mixing personal and business spending
Why it matters: Drawings end up as expenses and your profit looks smaller than it is.
Fix: Post owner withdrawals to a drawings account in equity.
✕ Skipping the opening balances
Why it matters: Every balance is wrong by the same amount, forever.
Fix: Start from last period's closing trial balance.
Importance of General Ledger Template
Is a ledger really worth the effort for a small business? Look at what happens without one. The ACFE's 2024 Report to the Nations studied 1,921 occupational fraud cases and found that organizations with fewer than 100 employees suffered a median loss of USD 141,000. A lack of internal controls was the most common weakness, at 32% of cases, and the typical fraud ran for 12 months before anyone noticed.
So what? A ledger won't catch a thief by itself. But a balance you review every month is the cheapest internal control there is.
Accurate Financial Reporting
Your balance sheet and income statement are only summaries of the ledger. In our sample, the 4,368.00 net profit comes straight from the closing balances of eight revenue and expense accounts.
Spot and Prevent Errors
Spreadsheets get it wrong more than people think. Raymond Panko's review of spreadsheet audits reports that the more careful audits since 1997 found errors in at least 86% of the spreadsheets audited. That's why every journal line here carries a check.
Facilitate Tax Preparation
Your accountant wants account balances, not a shoebox. Hand over a trial balance that agrees, and the tax return starts from numbers instead of questions.
Balance Your Books With Confidence
Out by 150.00 is a riddle until the ledger shows you three vouchers. Then it's a ten minute fix.
General Ledger Template vs Accounting Software
An accounting ledger template is a fine place to learn double entry and keep a small set of books. It starts to strain when entries come from many places.
| What you need | Spreadsheet template | Enerpize |
|---|---|---|
| Cost | Free | Free to start, then a paid plan |
| How entries arrive | Typed into the Journal by hand | Created from invoices and expenses, or added manually |
| Chart of accounts | Up to 100 accounts on one sheet | Main and sub accounts with balances shown in the tree |
| Ledger for one account | Pick a code and dates | Ledger report for one or more accounts, by date range |
| Sharing the result | Print or save as PDF | Print, or export to PDF, Excel or CSV |
Plenty of businesses start with the template and move when typing becomes the job. Either way, the ledger works the same.
How Enerpize Handles the General Ledger
What if nobody had to type the sale twice? In Enerpize's accounting software, invoices and expenses post their own journal entries, and the ledger report reads straight from them. The screens below use sample data.
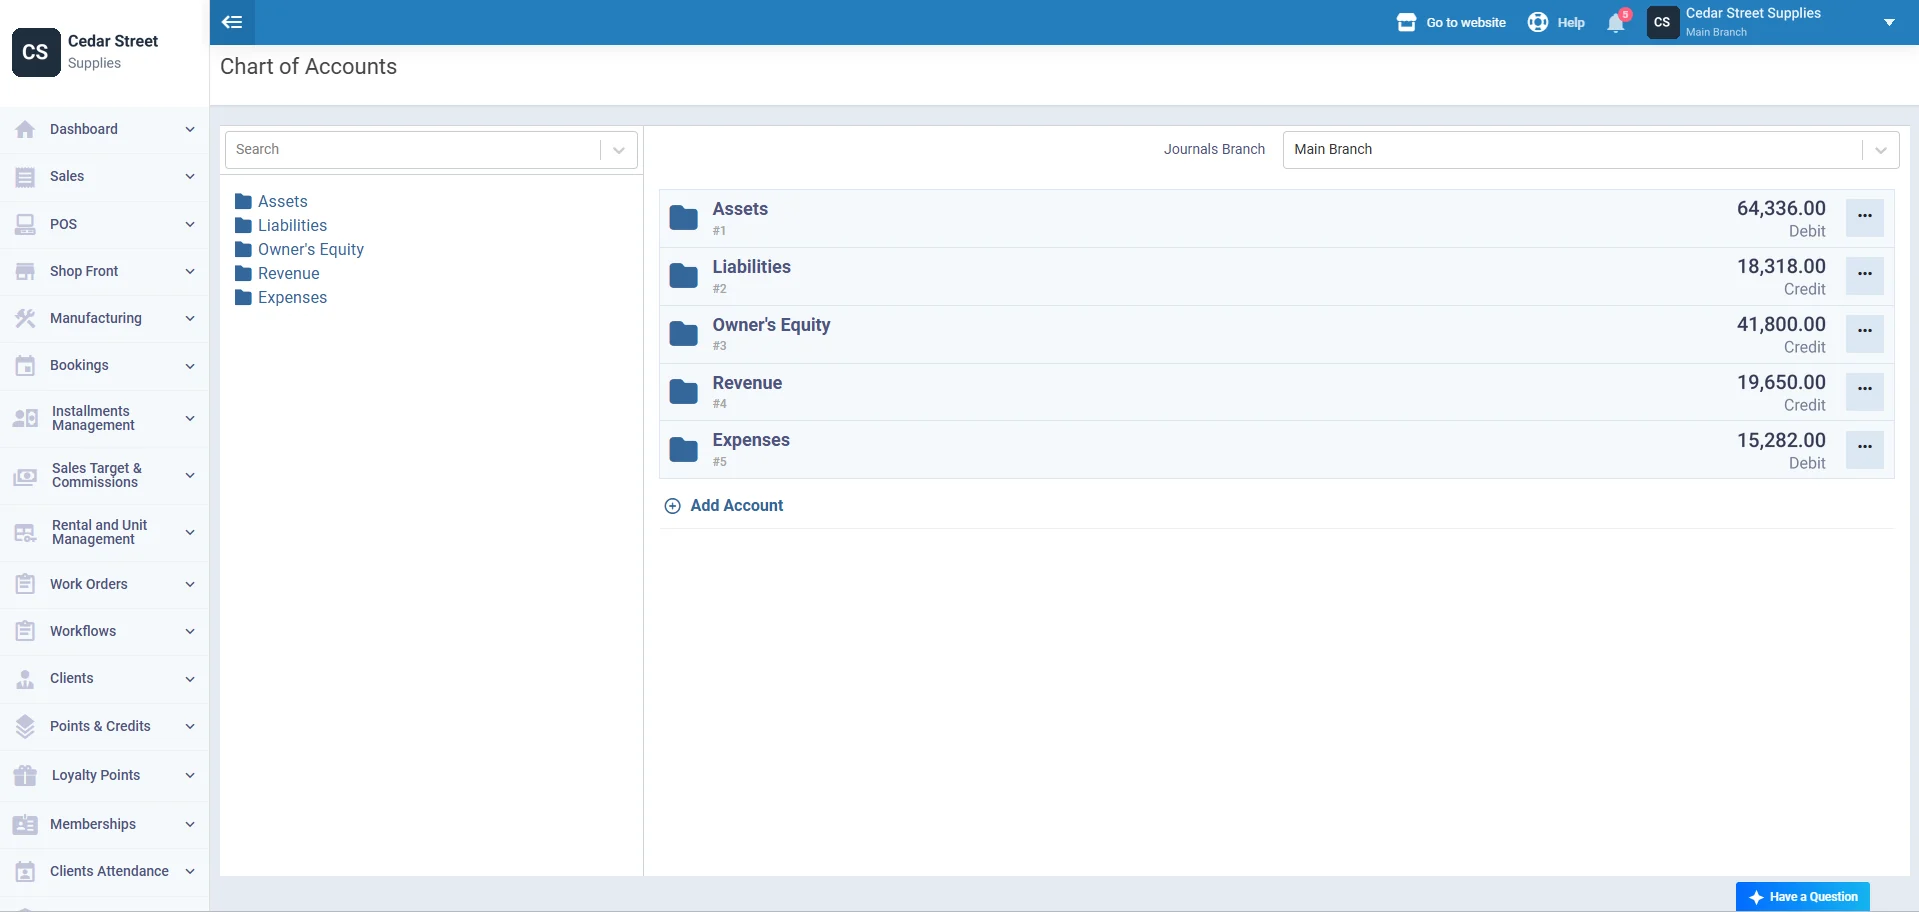
Chart of Accounts: The Tree Behind Every Balance
Accounts sit under five main groups: Assets, Liabilities, Owner's Equity, Revenue and Expenses. Each group shows its balance and whether it's a debit or a credit, and you can filter the view by journals branch. The chart of accounts is also where you open any account's ledger with one click.
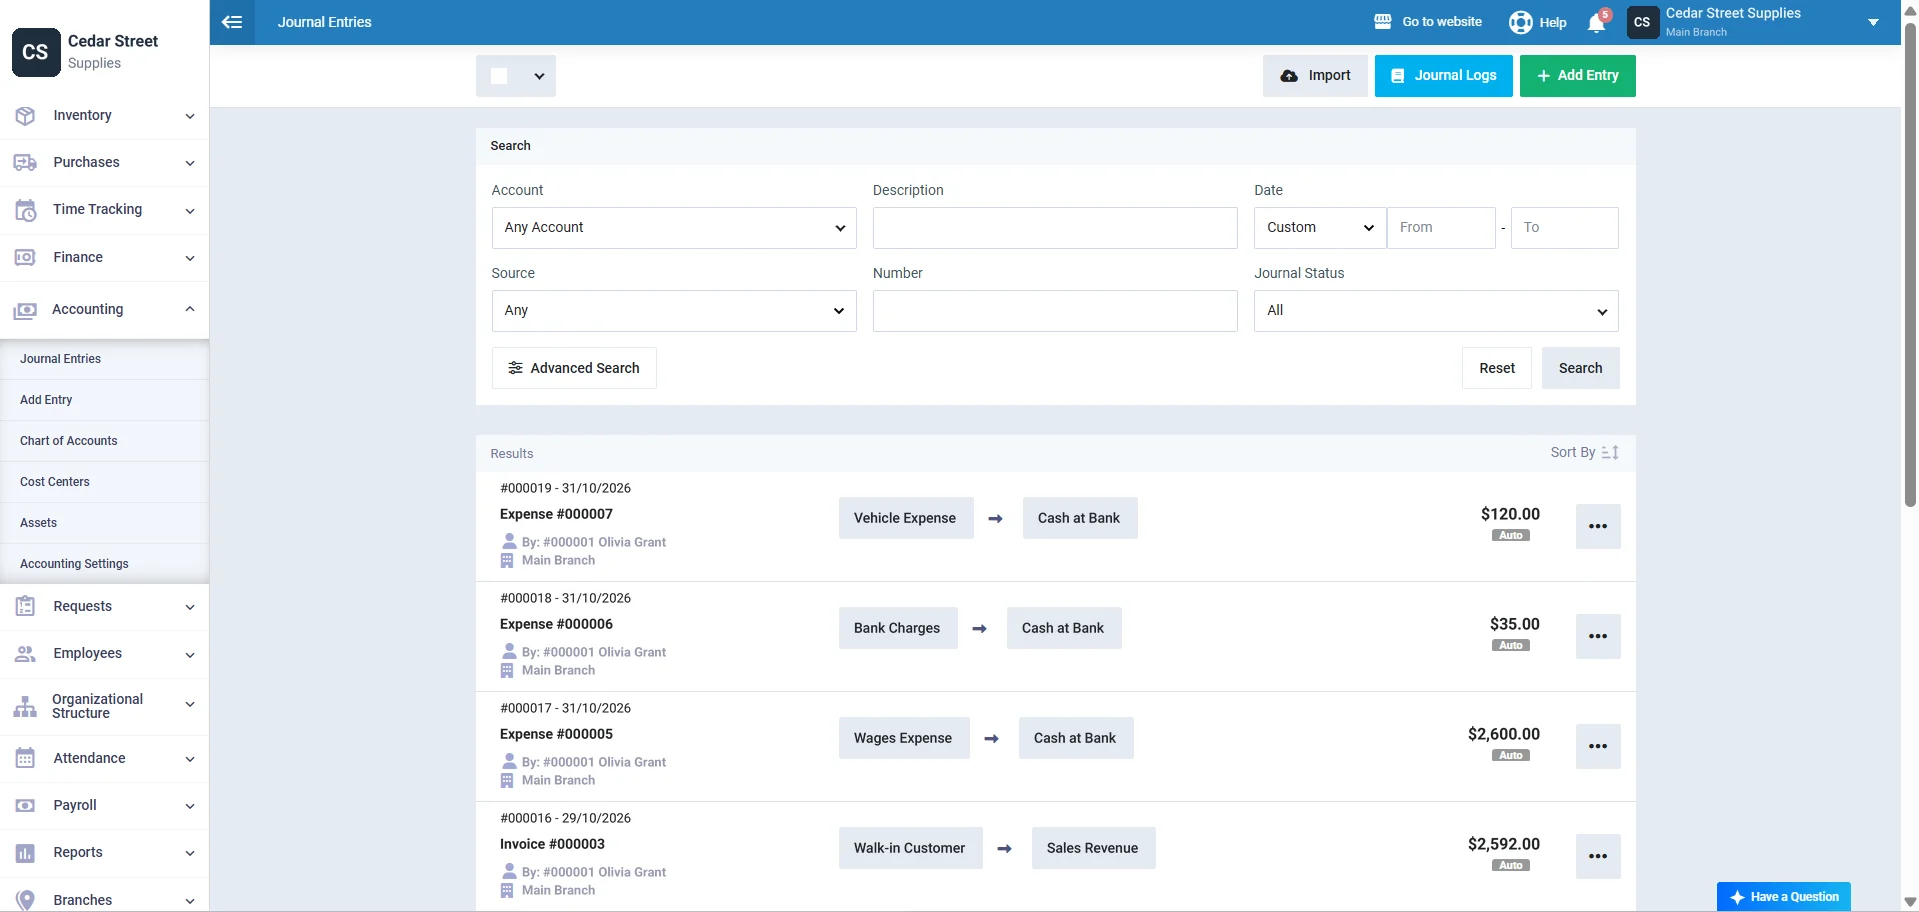
Journal Entries: Posted for You, Marked Auto
Each entry shows its number, date, source, the accounts it moved and the amount. Entries created by an invoice or an expense carry an Auto label. You can still add an entry by hand, import entries, and search by account, description, source, number or status.
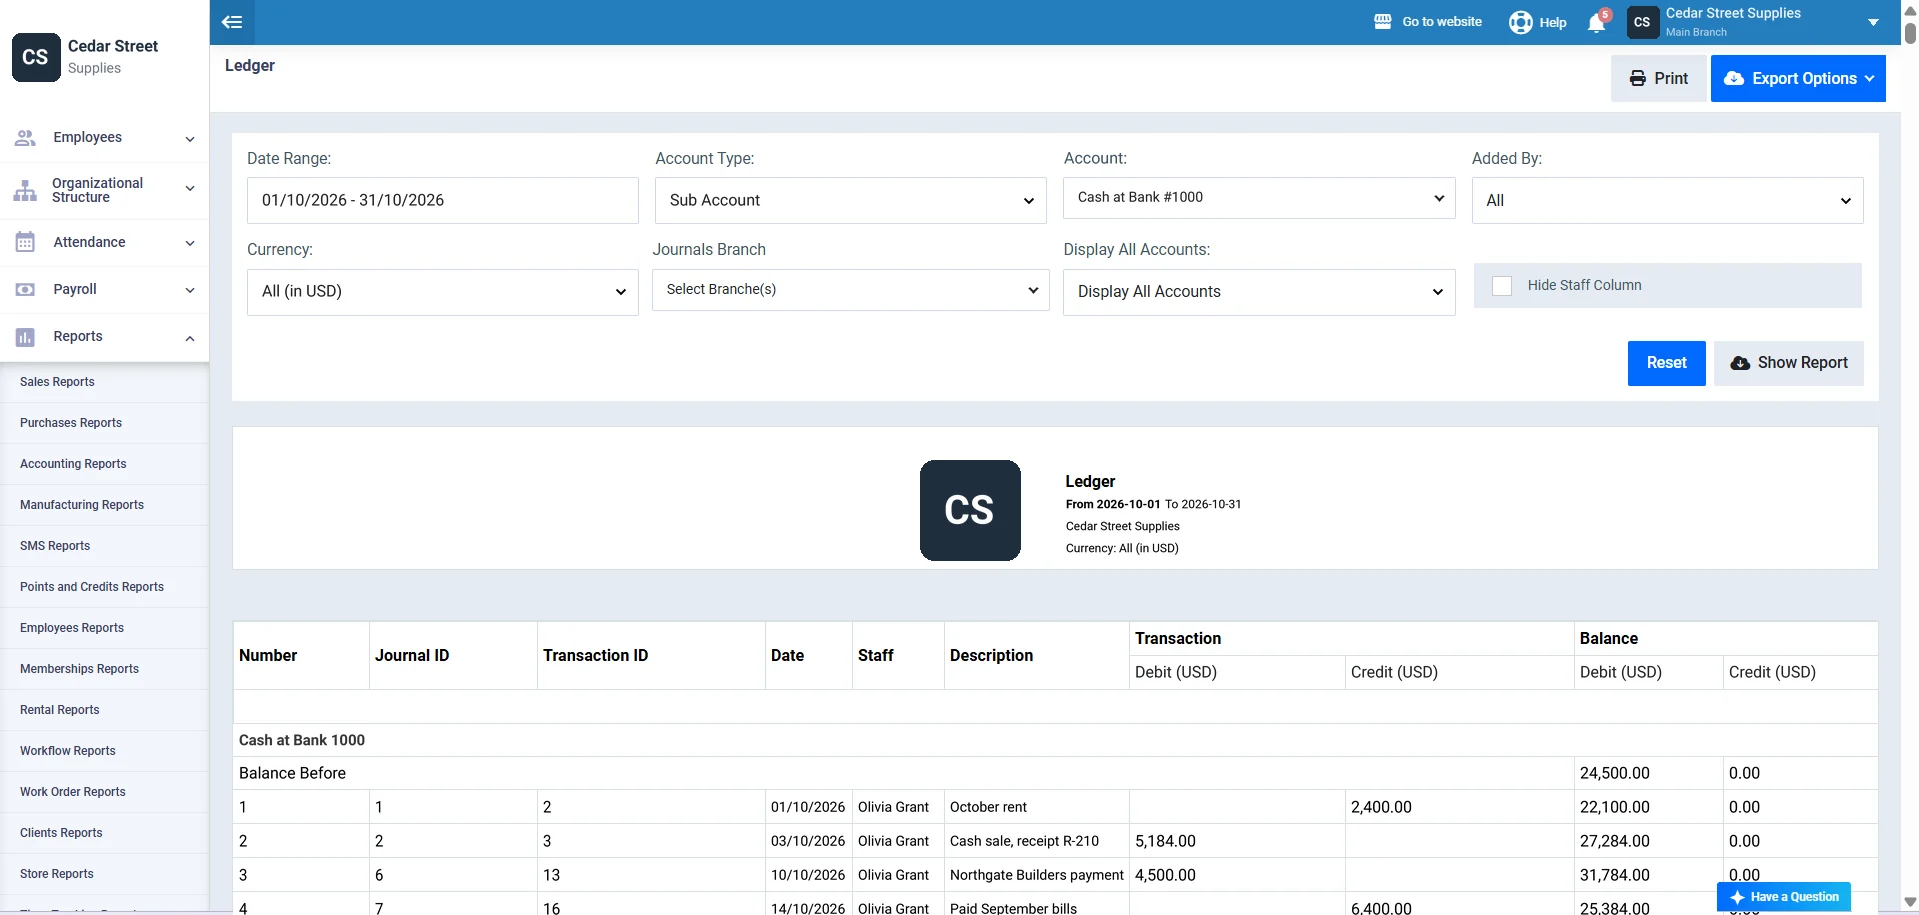
Ledger Report: Every Account, Line by Line
Choose a date range and one or more accounts. The ledger report starts each account with its balance before the period, then shows the balance after every transaction and a subtotal. Click a journal ID to open the entry, filter by branch, cost center or currency, and export to PDF, Excel or CSV. It's also how you print a bank statement from your own books.
Keeping a General Ledger in India
In India, "ledger" isn't just good practice for a company. It's written into the Companies Act.
Section 128 of the Companies Act, 2013 says books of account must give a true and fair view and be kept on an accrual basis under the double entry system. They must be kept for at least eight financial years, together with the vouchers for each entry. For tax, section 62 of the Income-tax Act, 2025 requires books for a business once income tops Rs. 1,20,000 or turnover tops ten lakh rupees in any of the three preceding years, rising to Rs. 2,50,000 and twenty-five lakh rupees for individuals and HUFs.
The Income-tax Rules, 2026 add detail. A Taxmann summary of Rule 46 says books must be kept for 7 tax years from the end of the relevant year, and electronic books must be backed up daily on servers in India.
What to add:
- INR as the currency, and 1 April to 31 March as the period
- Voucher numbers that match your vouchers, since they act as the J.F. column
- A party ledger for each major customer and supplier, as its own account code
⚑ Practical note: A spreadsheet saved on a laptop won't meet a daily backup rule by itself. If your books are electronic, ask your CA how Rule 46 applies to you.
Keeping a General Ledger in Pakistan
A party ledger format in Excel is how many Pakistani businesses track who owes what. The tax law cares about how long you keep it.
Section 174(3) of the Income Tax Ordinance, 2001 obliges a taxpayer to keep records for six years. In 2022, Business Recorder reported that the Supreme Court ruled a taxpayer can't be forced to produce records for a tax year beyond that six-year period.
What to add:
- PKR as the currency, and 1 July to 30 June as the period if that's your tax year
- Separate account codes for each party ledger you send out
- Sales tax payable as its own liability account
⚑ Practical note: Six years runs per tax year, so keep the whole file, journal included, not just the trial balance. Confirm current rules with your tax adviser.
Keeping a General Ledger in the United States
The IRS won't tell you which ledger to use. It will tell you how long to keep it.
IRS Publication 583 says you can choose any recordkeeping system suited to your business that clearly shows your income and expenses. It describes a journal as the book where you record each transaction, and a ledger as the book that holds the totals from your journals. Its period of limitations table lists 3 years in most cases, 6 years if you leave out income of more than 25% of the gross income shown, and 7 years for a bad debt or worthless securities claim. Employment tax records must be kept for at least four years after filing the fourth quarter.
What to add:
- USD as the currency, and your tax year as the period
- A sales tax payable account for each state you collect for
- Payroll liability accounts if you have employees
⚑ Practical note: Keep the receipts and invoices behind each voucher. A ledger shows the totals; the source documents prove them.
Keeping a General Ledger in the Philippines
The rule on keeping your books changed recently, so an older checklist may be wrong.
Under Revenue Regulations No. 7-2024, which implements the Ease of Paying Taxes Act, preservation of books of accounts falls under Section 235 of the Tax Code. Grant Thornton Philippines notes that books must now be preserved for five years, counted from the day after the filing deadline, or from the filing date if the return was late.
What to add:
- PHP as the currency, and your taxable year as the period
- Output VAT and input VAT as separate accounts if you are VAT registered
- Withholding tax payable as its own liability account
⚑ Practical note: A spreadsheet ledger is a working record. Check with the BIR or your accountant whether your official books must be manual, loose-leaf or computerized before relying on it.
Who Can Use the General Ledger Template?
Small Business Owners
You don't need an accountant to know your bank balance. You need one when the balance surprises you. A monthly ledger review keeps those surprises small.
Bookkeepers and Accounting Firms
One clean file per client, with checks that catch slips before the review. Accounting firms can hand clients the same accounting ledger template every month.
Startups Before Their First Software
Twenty entries a month doesn't need a system yet. It does need double entry, so the move to software later is a copy, not a rebuild.
Accounting Students
Type a textbook exercise into the Journal and watch the ledgers and trial balance respond. It's a general ledger example you can break on purpose.
Club and Association Treasurers
Dues in, venue costs out, and a committee asking where the money went. A printed ledger statement answers in one page.
General Ledger Glossary
| Term | What it means |
|---|---|
| Debit (Dr) | The left side of an entry. Increases assets and expenses. |
| Credit (Cr) | The right side of an entry. Increases liabilities, equity and revenue. |
| Normal balance | The side an account usually sits on: Dr for assets and expenses, Cr for the rest. |
| Post reference | The journal or voucher number a ledger line came from. Also called J.F. |
| Balance b/f | Balance brought forward from the previous period. |
| Chart of accounts | The list of every account a business uses, with codes. |
| Subsidiary ledger | A detailed ledger, such as one per customer, that totals into one general ledger account. |
Key Takeaways
- A general ledger template sorts journal entries by account and keeps a running balance for each one.
- Enter each transaction once. In our sample, 45 journal lines feed 18 account ledgers and one trial balance.
- Show balances on their side. Accounts Payable closes at 7,800.00 Cr, not minus 7,800.
- Running balance = previous balance + debit − credit, so 24,500.00 less 2,400.00 rent gives 22,100.00.
- A trial balance out by 150.00 traced back to three vouchers: 18.00, 48.00 and 120.00.
- Small organizations lost a median USD 141,000 per fraud case in the ACFE's 2024 study, and 32% of cases involved weak controls.
- Keep books for as long as local law says: 8 years under India's Companies Act, 6 in Pakistan, 5 in the Philippines.
- In the US, the IRS lets you pick your recordkeeping system, but keep most records for at least 3 years.
Frequently Asked Questions
What is the format of a general ledger?
A general ledger format has a page for each account, with columns for the date, post reference, particulars, debit, credit and running balance. It opens with the balance brought forward and closes with the period totals and closing balance. Students often draw it as a T-account, with debits on the left and credits on the right.
What is the difference between a general ledger and a ledger statement?
The general ledger holds every account in the business. A ledger statement is one account, often a customer or supplier, printed for a set period. You run a ledger statement from the general ledger, so the two always agree.
What is the difference between a journal and a ledger?
The journal records each transaction in date order, showing both sides of the entry. The ledger takes those entries and sorts them by account, so you can see each account's balance. You write in the journal first and post to the ledger second.
How do you calculate a running balance in a ledger?
Take the previous balance, add the debit and subtract the credit on that line. Copy the formula down and every row shows the balance at that point. Show a positive result in the Dr column and a negative one in the Cr column, without a minus sign.
What is a post reference in a general ledger?
The post reference is the number of the journal entry or voucher a ledger line came from. In India and Pakistan it's often called J.F., short for journal folio. It lets anyone trace a ledger balance back to the original entry.
Can I keep a general ledger in Excel or Google Sheets?
Yes. A general ledger template in Excel or Google Sheets works well for a small business, as long as it uses double entry and checks that debits equal credits. Our template has no macros, so it opens in both without a warning.
How often should a general ledger be updated?
Post entries daily or weekly, while the documents are still in front of you. Review each key account and run a trial balance at least once a month. Waiting until year end turns small gaps into long searches.
What is the difference between a general ledger and a subsidiary ledger?
A subsidiary ledger holds the detail for one type of account, such as one ledger per customer. Its total feeds a single control account in the general ledger, such as Accounts Receivable. The two totals should always match.
About the Author
Omar El Bahr is a Senior Digital Growth Specialist at Enerpize, where he leads SEO, content strategy, and organic growth across international markets. He is a Forbes Communications Council contributor and has written for Entrepreneur on business communication and digital strategy.
Disclaimer
Our template and the information on this page are for general guidance only and are not accounting, tax or legal advice. Record keeping rules differ by country and change over time, so confirm your position with a qualified accountant or your tax authority. A spreadsheet ledger is not a registered or prescribed book of accounts.